VIX 22.91 against 23.02 three months out; Nvidia reports at 21:20 UTC
 Ahoy there, Trader! ⚓️
It’s Phil…
Monday had three good excuses and arrived too early for all of them.
Today’s three questions:
- How much of Monday’s fall was done before the opening bell?
- Did any of the day’s headlines come early enough to explain it?
- What does a VIX this close to VIX3M say about the mood?
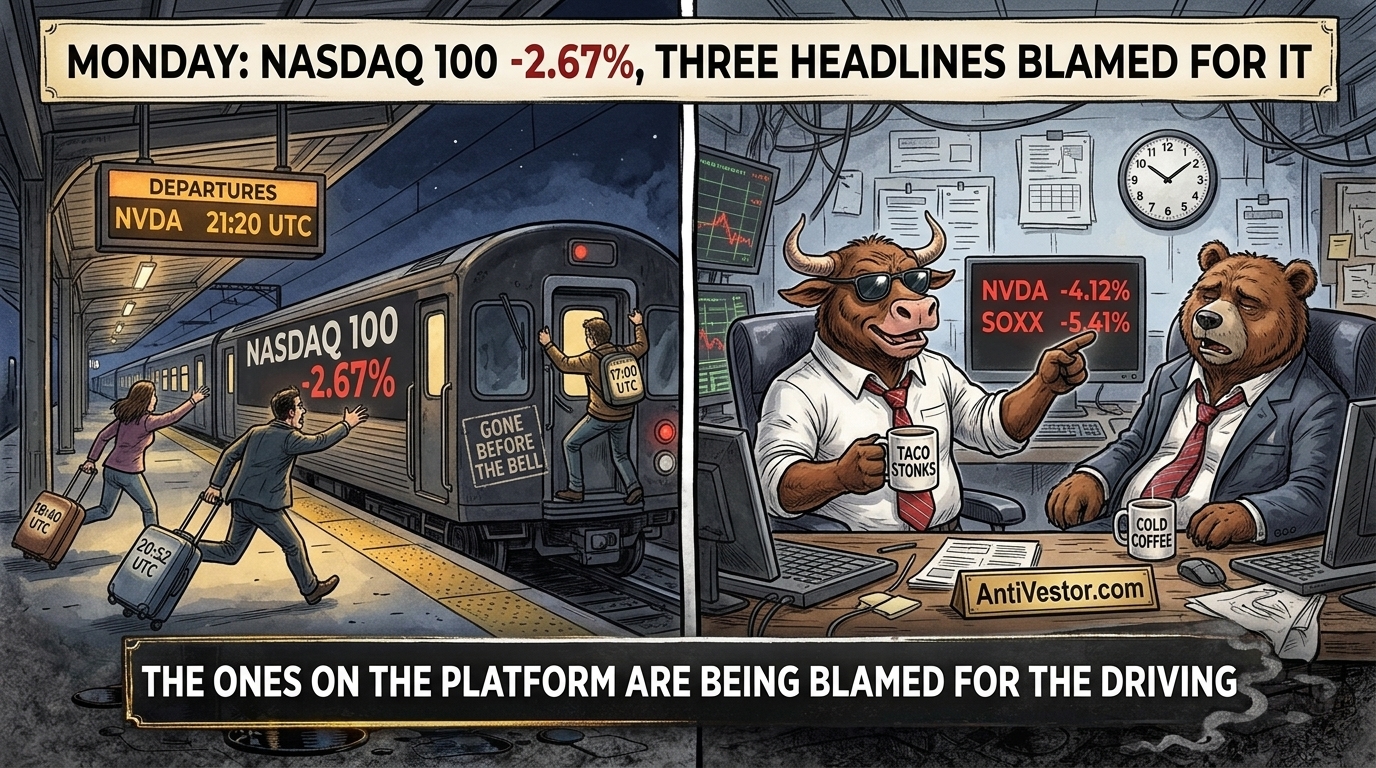
Start with the bell. The Nasdaq 100 closed Friday at 27,943.74, opened Monday at 27,543.64 and closed at 27,197.15, down 2.67%. The opening gap was 54% of the day’s fall. In other words, most of the damage was done by the overnight futures slide that yesterday’s letter described and declined to explain, in the Asian session, with nothing on record before it. That slide turned out to be the main event. The S&P 500 was a slower burn: it gapped about a third of its 1.92% fall and sold the rest during the day, closing at 7,416.59.
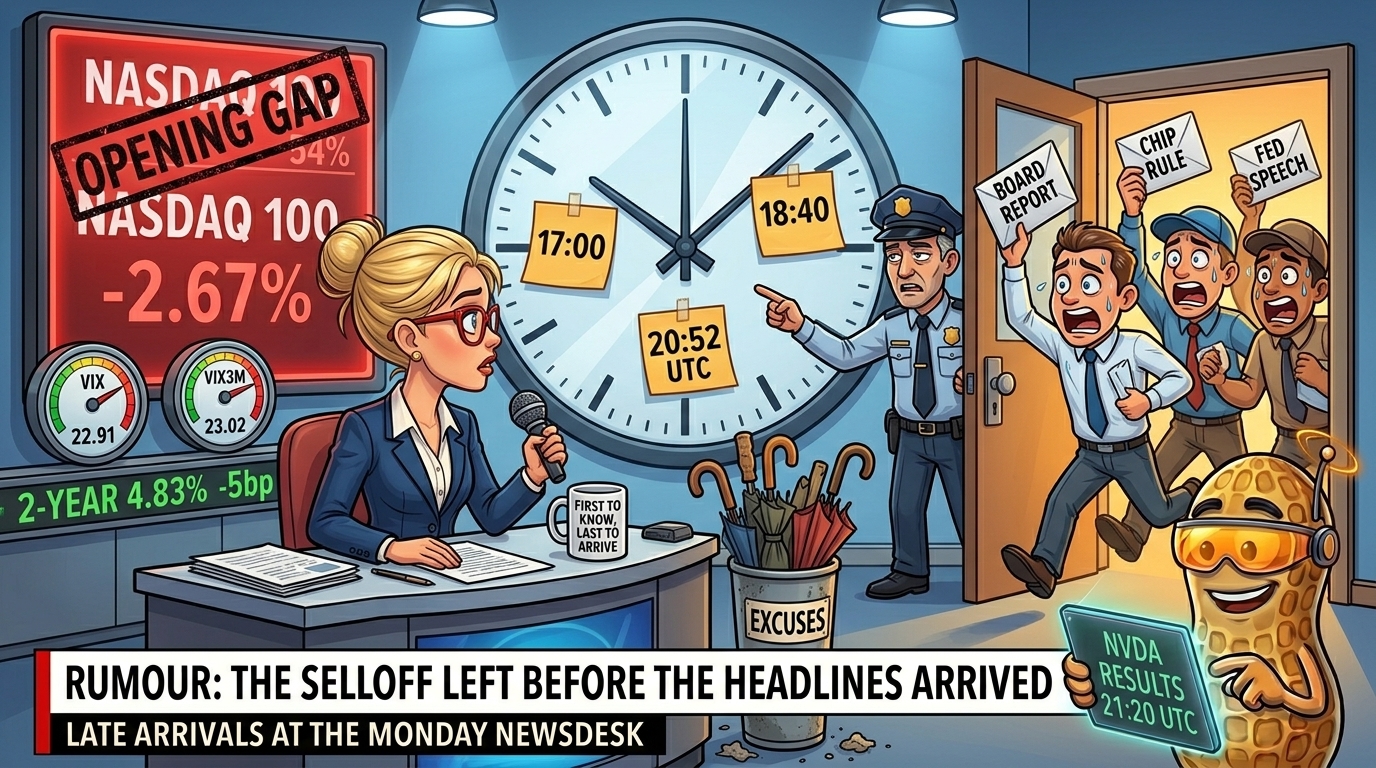
Now the excuses, in the order they arrived. Warsh opened a San Francisco Fed conference at 17:00 UTC with a prepared text that said nothing about rates; by then 61% of the S&P 500’s fall was done. A report that Nvidia’s board is not considering reinstating its founder came at 18:40 UTC. By 18:30 UTC the S&P 500 stood at 7,424.38, with 95% of its fall behind it, so the report arrived in time to attend the close and not much else. Coverage of a new Commerce Department rule on AI chip exports appeared at 20:52 UTC, eight minutes before the bell and after the day’s low at 20:15 UTC. The evening wraps reached for all three. The clock allows none of them, so none is named. Three good stories; no culprit. Nothing on record explains the S&P 500’s slide during the session either.
Nvidia itself fell 4.12% to $156.14, which is less than the chip funds: SOXX lost 5.41%, SanDisk 8.58% and Micron 7.62%. The stock that has the leadership crisis had a better day than the stocks that do not.
Meanwhile the bond market behaved like a bond market. The 2-year fell 5bp to 4.83%, the 10-year 3bp to 5.12%. Stocks fell, bonds rallied, and a December hike is still priced as near certain. The selling in stocks and the hike priced for December sat side by side, unbothered by each other.
Which brings us to the gauge. The VIX rose 18.70% to 22.91. Its three-month sibling, VIX3M, closed at 23.02. On Friday spot volatility sat 1.32 below the three-month; on Monday it sat 0.11 below.
How it works: The VIX prices the next 30 days of S&P 500 swings and VIX3M the next three months. Usually the longer one costs more, because more can go wrong in three months than in one. When near-term fear rises faster → the gap narrows → once the VIX is higher, the curve has inverted, and traders are paying more to insure this month than this quarter.
This month has Nvidia tonight, the Fed minutes tomorrow and Anthropic’s listing on Thursday. The gap is 0.11.
The One That Mattered
Twenty-two point nine one against twenty-three point zero two. The VIX closed 0.11 below the three-month measure, from 1.32 below on Friday, after a day when the Nasdaq 100 fell 2.67% and more than half of it was done before the bell. Three headlines competed for the blame and all three turned up after most of the selling. The option market did not wait for an explanation either: it marked near-term protection almost level with the quarter’s. Tonight’s Nvidia numbers are the first event this week with a time the market has to wait for. The case against: a near-flat curve ahead of three dated events (Nvidia tonight, the minutes, Anthropic) is ordinary, and the VIX was higher still at 28.18 on 5 Nov, so this may be a calendar more than a scare.
Hot News: Nvidia, the Chip Rule and the Week’s Tests
The board is reportedly not considering the founder’s return; staff have written in
Nvidia. New since Monday morning: a report at 18:40 UTC, followed by the WSJ at 02:11 UTC, said the board is not considering reinstating Jensen Huang and is focused on its own investigation. At 02:38 UTC the WSJ reported an employee letter to the board calling him irreplaceable. Shares fell 4.12% to $156.14. Results arrive at 21:20 UTC, with the call at 22:00 UTC. Reuters frames tonight as the main test for the AI trade this week. Not yet known: a permanent chief executive, and whether the results carry the usual guidance.
The chip-export rule. New: the Commerce Department will require licences to ship advanced AI chips to Indonesia, Malaysia, Singapore, Thailand and Brazil, aimed at Chinese firms renting capacity abroad. First coverage was stamped 20:52 UTC on Monday; the release time is not on record. Asian markets fell overnight, led by Korea and Taiwan; Reuters tied the fall to the rule, but no stamp establishes that link.
Anthropic. The share sale prices on Wednesday and trades on Thursday under ANT, with terms unchanged. Reports of how much demand there is conflict.
Fed hike bets. Warsh’s prepared text had nothing on rates; the 2-year fell 5bp anyway. Retail sales at 13:30 UTC and Waller, on payments, at 14:10 UTC today; minutes on Wednesday.
Our Top Trader Uses This 9:50 AM Secret to Target $500 Per Day Regardless Of Which Direction The Market Moves https://antivestor.com/ppp-webinar
Stock Market Edge
The market got its selling done early and spent the afternoon finding reasons
Premarket snapshot:
| Market | Close | Day |
|---|---|---|
| S&P 500 | 7,416.59 | 🔴 -1.92% |
| Nasdaq 100 | 27,197.15 | 🔴 -2.67% |
| 2-year Treasury yield | 4.83% | 🟢 -5bp |
| WTI December | $85.72 | 🔴 -3.21% |
| Gold spot | $3,855.98 | 🔴 -0.55% |
| Bitcoin (UTC close) | $64,849.02 | 🔴 -0.72% |
| Nvidia | $156.14 | 🔴 -4.12% |
| VIX | 22.91 | 🔴 +18.70% |
On the 07:40 to 07:45 UTC bar, read twice, December S&P 500 futures were 7,420.25, down 0.29% on Monday’s 16:00 ET mark, and December Nasdaq 100 futures 27,297.25, up 0.02%. Dow futures were down 0.47%, Russell 2000 futures down 0.48%. The Nasdaq contract spent the night between 0.41% below the mark and 0.76% above it, and ended the night roughly where it began.
Sector rotation:
Chips and AI infrastructure took the worst of it: SOXX down 5.41%, SMH 5.11%, AMD 5.58%, Nebius 7.55% and CoreWeave 6.12%. Technology fund XLK lost 3.24%. Staples rose 0.27% and utilities 0.18%, the only two sector funds to finish higher, and Costco added 0.68%. On the NYSE 2,013 stocks fell and 668 rose, and 76% of volume traded in fallers. Nobody hid in the Dow, which still lost 1.41%.
Earnings or guidance:
Nvidia at 21:20 UTC. Home Depot reports before the open. No large company reported after Monday’s close that we found. Telus rose 12.19% after Quebecor proposed a combination, which Telus called undervalued; the proposal came before the open, so this one has its cause.
Cross-asset nuance:
The 2-year fell 5bp to 4.83%, the 10-year 3bp to 5.12% and the 30-year 1bp to 5.46%. The 20-year, at 5.51%, still tops the curve. Bond volatility, the MOVE index, rose to 101.29 from 98.78. The dollar index closed at 103.59 and the yen at 159.43. December WTI settled at $85.72, down 3.21%; it expires on Friday and still leads January on volume. Spot gold fell 0.55% and December silver 4.60%.
What it means: Cheaper short-term money is mild good news for anyone fixing a loan this week, and a pension with a big chip weighting has a results night to sit through.
Crypto Market Edge
Bitcoin had a nap; the people who own lots of it did not
Price snapshot:
Bitcoin closed Monday’s UTC day at $64,849.02, down 0.72%, and was $64,549.79 at 07:40 UTC. Ether closed at $1,819.81, down 0.80%, and read $1,826.19 this morning.
Flows and positioning:
Farside returned errors on four attempts, so no fund-flow figure is printed. Strategy’s 8-K shows 485 bitcoin bought for $33.4m at an average of $68,887, holdings 850,849, and $244.7m raised from share sales. The firm that once said it would never sell has still sold twice, and this week only bought.
Leadership and rotation:
Strategy fell 7.70% to $103.03 and Coinbase 6.11% to $119.84, on a day the coin itself barely moved. ICP topped the Stocktwits crypto board with an 11.55% gain and no news we could find.
Catalysts and roadmap:
Nvidia tonight, Fed minutes Wednesday at 19:00 UTC, Anthropic on Thursday. The crypto shares have the same diary as everyone else.
What it means: Holding bitcoin was a quiet day; holding the companies that hold bitcoin cost several times as much.
TL;DR
- The Nasdaq 100 fell 2.67% and 54% of it was the opening gap. Yesterday’s unexplained overnight futures slide turned out to be the main event.
- The board story arrived at 18:40 UTC and the chip-export rule at 20:52 UTC. By then 95% of the S&P 500’s fall was done.
- The VIX rose 18.70% to 22.91, just 0.11 below VIX3M at 23.02. On Friday the gap was 1.32.
- Stocks fell and bonds rallied: the 2-year dropped 5bp to 4.83% with a December hike still priced as close to certain.
- Nvidia reports at 21:20 UTC tonight with a founder ruled out by his board. Strategy bought 485 bitcoin and its shares fell 7.70%.
Rebuilt in 2003 The fear gauge changed its diet once
The first VIX, in 1993, was built from S&P 100 options. In 2003 Cboe rebuilt it on S&P 500 options, and the old version lived on as VXO.
Meme of the Day:
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
p.s. There are 3 ways I can help you…
- Option 1: Collect Morning Income
A complete guide to the Premium Popper system.
Written to be clear, concise, and immediately actionable.
>> Learn More Here
- Option 2: Collect Weekly Income
A complete guide to the Tag ‘n Turn system.
>> Learn More Here
- Option 3: Join the Fast Forward Mentorship
>> Join the Fast Forward Mentorship – trade live, twice a week, with me and the crew.
PLUS Monthly on-demand 1-2-1’s
No fluff. Just profits, Tag ‘n Turn Pulse bars, Poppers, and Patterns that actually work.