A 2.35% equity rally, cheaper fuel and a dearer front end, hours before the inflation print
⚓ Weathervane. The wind is coming from the long end. The policy rate has been frozen for most of the year whilst the term premium does the tightening, and the price of long money is set by deficits, issuance supply and a synchronised global duration bid rather than by the committee. Higher-for-longer stopped being a Fed decision and became a bond-market fact. The cruise ship is holding this heading.
 Ahoy there, Trader! ⚓️
It’s Phil…
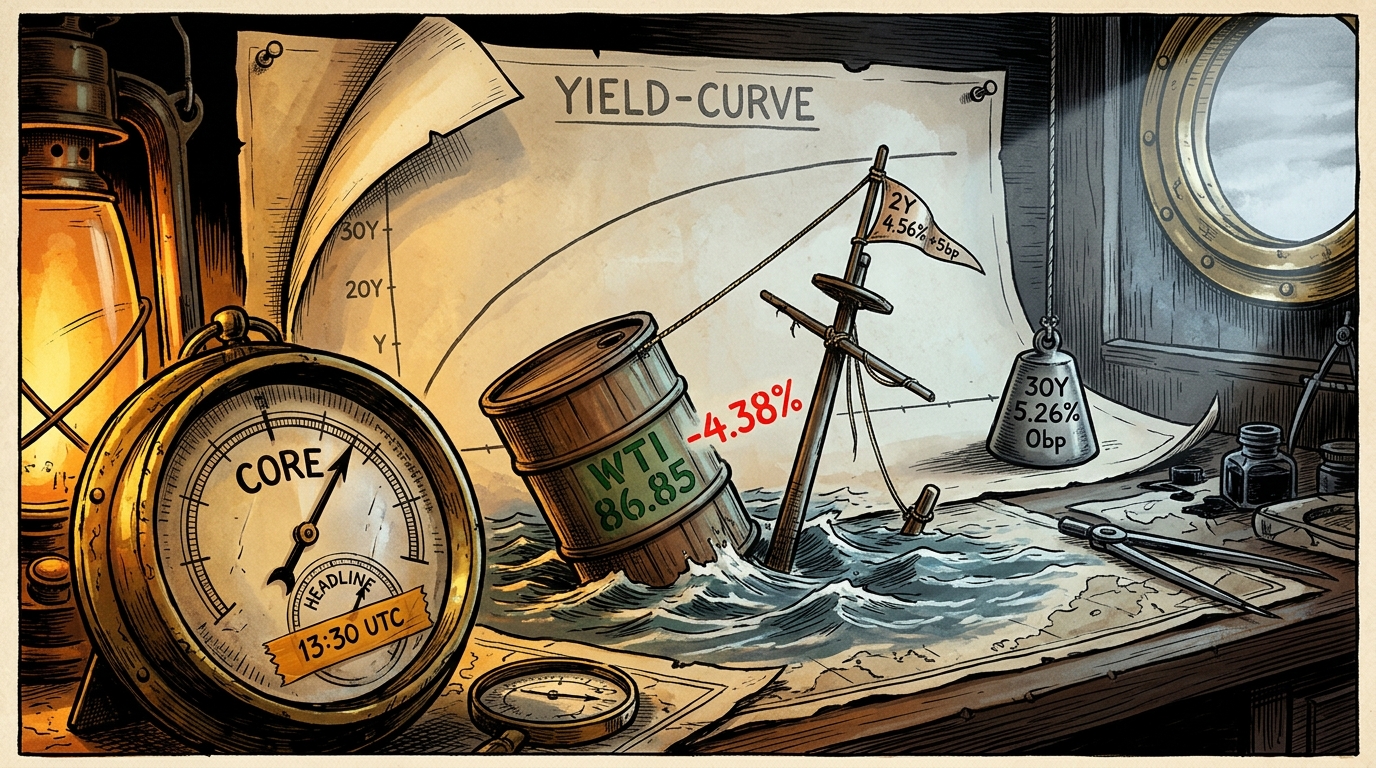
Oil fell 4.4% and the 2-year still rose 5bp: what does the front end know that the oil market does not?
Monday looked like one of the friendlier sessions of the autumn. The S&P 500 rose 2.35%. The VIX fell from 25.64 to 19.92 and its curve came out of inversion. December WTI settled 4.38% lower at $86.85, and the dollar index slipped 0.59%.
On the surface, that is a disinflation day. Cheaper oil feeds straight into headline inflation, a calmer world needs less insurance, and a softer dollar eases import prices. Every one of those should pull the 2-year yield down.
The 2-year rose 5 basis points to 4.56%. The 10-year rose 2bp. The 20-year and 30-year did not move at all. So the curve flattened from the front: 2s10s narrowed to 32bp from 35bp.
The textbook says the front end trades the next few Fed meetings, and the next few Fed meetings trade inflation. On that reading, a 4.4% fall in crude should have bought the 2-year a few basis points of relief. Instead it gave a few back.
There are two honest readings of the gap. One: the front end is looking through oil to core, where the energy price barely reaches, and core has been the stubborn half. September printed 0.6% on the headline and 0.3% on core, month on month. Two: the rally itself is the problem. A 2.35% equity day and a collapsing VIX ease financial conditions, and easier conditions are precisely what a committee watching inflation does not want to see.
There is a catch in the calendar. This morning’s CPI covers October, so Monday’s 4.38% oil fall is not in it at all; it belongs to November’s report. Today’s print cannot tell us whether the oil market was right. It can only test the front end’s worry, and the number that does that is core. Consensus is 0.2% month on month. A core print at or below that, with the 2-year still higher by the close, would make the second reading the stronger one. A core print above it would make Monday’s equity rally look early.
So the useful thing to watch at 13:30 UTC is core, and the oil question waits a month.
Phil’s Musing
I keep coming back to the 30-year sitting perfectly still while the 2-year rose. If the long end really sets the weather, Monday was a day it chose not to vote. The front end did all the talking, and it talked about the Fed rather than about oil.
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
P.S. – Phil’s Footnote I assumed a big fall in crude would drag the front end down with it, at least for a session. It did not, and I had to go back and check the 2-year twice before I believed it.
🗂 Desk Notes – Part 247 | 10 Nov 2026
Session read (§8.4)
SESSION BRIDGE: prior session (Mon) full reaction ES Dec settle +2.33% (SPX cash +2.35%, after-hours single names only); live premarket ES +0.20% / NQ -0.12% at the 07:45Z capture, VIX -22.31% (prior close, no global-hours bar); threshold: HARD.
- Hard trigger on the prior session (ES +2.33%, over 2.0%). Soft legs also fire: VIX -22.31% (over 8%), December WTI -4.38% (over 4%).
- §8.4.2 cash trigger: met. SPX +2.35% and RUT +3.15% are each the second-largest absolute daily move in the held 24-session window (6 Oct to 9 Nov), behind 5 Nov; both are the largest up day in it. NDX, IXIC, DJI rank third.
- Premarket inside the normal band. 08:05Z re-quote: ES +0.21%, NQ -0.04%, YM +0.47%, RTY +0.32% vs Monday settle.
- Bases: ES-SPX 24.31, NQ-NDX 106.87. No contract roll (18 Dec). WTI December last trades about 19-20 Nov: roll watch.
Carry-over (§10.6): the expected follow-through from Monday’s oil fall did not show where it should have. Crude fell 4.38% and the 2-year rose 5bp. The dissection goes to Macro Edge.
Mechanism read
| Tenor | 6 Nov | 9 Nov | bp |
|---|---|---|---|
| 2y | 4.51 | 4.56 | +5 |
| 10y | 4.86 | 4.88 | +2 |
| 20y | 5.29 | 5.29 | 0 |
| 30y | 5.26 | 5.26 | 0 |
2s10s 35 to 32bp, 2s30s 75 to 70bp, 20s30s -3bp both days; 20-year strict curve maximum again. Front-end-led bear flattening on a risk-on day. DXY 102.279 to 101.677 (-0.589%), 101.546 at 07:45Z. VIX 25.64 to 19.92; VIX3M 24.60 to 20.85; ratio 1.042 to 0.955, curve back in contango. MOVE 92.782 to 85.994 (-7.316%). HYG 77.23 to 77.51, LQD 104.53 to 104.67, TLT 81.92 to 81.96 (proxies, no duration held, no spread call).
Cause board (§8.3). Effects without causes: SPX +2.35% with 73.78% of the move after the 14:30Z open; NDX 70.20% after the open. Causes without effects: Tehran’s “FAKE NEWS” rejection (00:39Z), after which crude was still lower at the capture (-1.62%) and futures sat inside the band.
The refusal, with its search. Routes checked: AP via KSAT, Al Jazeera, CBS live, Yahoo Finance, TradingView news, Reuters headline via TradingView. Stamps found: Rubio 23:14Z Sun (no breakthrough), Reuters “Iran talks lift risk appetite” 20:15Z Mon, Trump remark 20:52Z Mon, narrative wraps 22:23Z Mon onward. Test run: no Monday stamp held explains the 14:30Z-21:00Z intraday leg that carries 73.78% of the SPX gain; the Reuters 20:15Z headline came after most of it (the first hour carried most of the intraday leg), and the 20:52Z remark post-dates the 19:30Z crude settle. Crude’s -4.38% and SOXX +7.49% likewise carry no stamped cause. Index scope: majority_unexplained.
Majority test on the premarket contract. NQ reads: capture -0.12% (07:50Z), re-quote -0.04% (08:10Z). No cause is credited to the NQ reads; both sit inside the normal band. The Nvidia board inquiry is stock-scope and is not tested at index level.
| Candidate | Class | Stamp | Precedes majority | Disposition |
|---|---|---|---|---|
| Trump “effectively over” | 3 | 20:52Z 9 Nov | no | coincidence |
| Weekend Iran talk (Rubio, scheduled Qatar meeting) | 3 | 23:14Z 8 Nov | yes | refusal at index scope |
| Reuters “Iran talks lift risk appetite” | 4 | 20:15Z 9 Nov | no | coincidence |
| Nvidia board inquiry | 2 | 21:58Z 8 Nov | yes | published cause, NVDA only |
| AI dip-buying narrative | 4 | 22:23Z 9 Nov | no | coincidence |
| Constellation Energy beat and raise | 2 | 9 Nov pre-open | yes | Desk Notes only: stock scope, no index weights held |
| After-hours: Trade Desk, Take-Two, Rocket Lab, Occidental | 2 | 21:01Z-21:15Z | no | Desk Notes only: single names after the close |
Null rate: index-scope NULL again.
Overnight Excitement (§8.5)
Silent. NQ overnight range +0.337% / -0.519%, ES +0.32% / -0.09%, YM +0.54% / -0.03%, RTY +0.365% / -0.158%, all versus Monday settle. Colour only, attributed: Japan and Korea opened higher, Hong Kong and China modestly higher (syndicated reports); India closed.
Hot News board
- Middle East / Iran, ROLLING, LEAD. New: Trump-Qatar PM meeting; “militarily effectively over”, blockade stays (AP 20:52Z). Iran: Rezaei “FAKE NEWS” (Al Jazeera 00:39Z), Pezeshkian “will not surrender”. Not known: talks date, venue, Hormuz status. Next: Rubio at G7 Paris today. Market: crude -4.38% Mon, -1.62% at capture.
- Nvidia board inquiry, ROLLING (opened 9 Nov). New: House chairs Mast, Moolenaar and Crawford request a closed-door briefing on 18 Nov; Bloomberg via The Edge (02:08Z) says Nvidia’s general counsel contacted Commerce in 2025 about a Megaspeed executive’s detention; investor lawsuit filed (tier 3). NVDA -4.27% vs SOXX +7.49%. Next: results 17 Nov, briefing 18 Nov.
- AI and tech rout, ROLLING. Monday relief: SOXX +7.49%, AMD +13.26%, AVGO +8.78%, MU +6.25%. Next: CoreWeave after today’s close, Cisco and Applied Materials Thursday (Cisco date conflicts: 11 vs 12 Nov).
- US midterms 2026, ROLLING. Mississippi ballot deadline today, Colom +2,574 (AP); DDHQ House 255-162, 18 unprojected. No AP tally newer than 7 Nov held. No market link. Retire on the Mississippi call.
Forward slate
- Today: Waller 09:00Z (London, Economic Outlook); October CPI 13:30Z, consensus 0.3% headline / 0.2% core m/m on two routes; Lombardelli 12:30Z; 10-year auction $42bn 18:00Z; Bowman 20:30Z and 23:30Z; CoreWeave after the close; TransDigm before the open.
- CPI annual rate: conflict. Previews say BLS will not publish a 12-month change (October 2025 not collected); AP quotes an expected 3.9%. Nothing annual published until the release settles it.
- Wed 11 Nov: Veterans Day, bond market closed, equities open. Thu 12 Nov: 30-year auction $25bn; Applied Materials. Fri 13 Nov: PPI. 17 Nov: Nvidia results.
- Not this week: FOMC (8-9 Dec).
Divergence flags
- Crude -4.38% vs 2-year +5bp on the same session.
- Spot gold +1.83% while VIX fell 22.31%: haven reading challenged.
- NVDA vs its sector: -11.76 points.
- Bitcoin flat since Monday’s 21:00Z mark through an equity rally.
- NQ below YM at the capture, second morning running (9 Nov gap -1.16pp, Part 246 lock; today -0.60pp).
Regime and sensitivity read (§17.3)
Weathervane turn condition not advanced (no dated Fed communication; Bowman 9 Nov had no policy content). Regime flag not tripped. Sensitivity running LOOSE, stated openly.