A hot core print, a 17bp 2-year, and two volatility gauges that read it in opposite directions
⚓ Weathervane. The wind is coming from the long end. The policy rate has been frozen for most of the year whilst the term premium does the tightening, and the price of long money is set by deficits, issuance supply and a synchronised global duration bid rather than by the committee. Higher-for-longer stopped being a Fed decision and became a bond-market fact. The cruise ship is holding this heading.
 Ahoy there, Trader! ⚓️
It’s Phil…
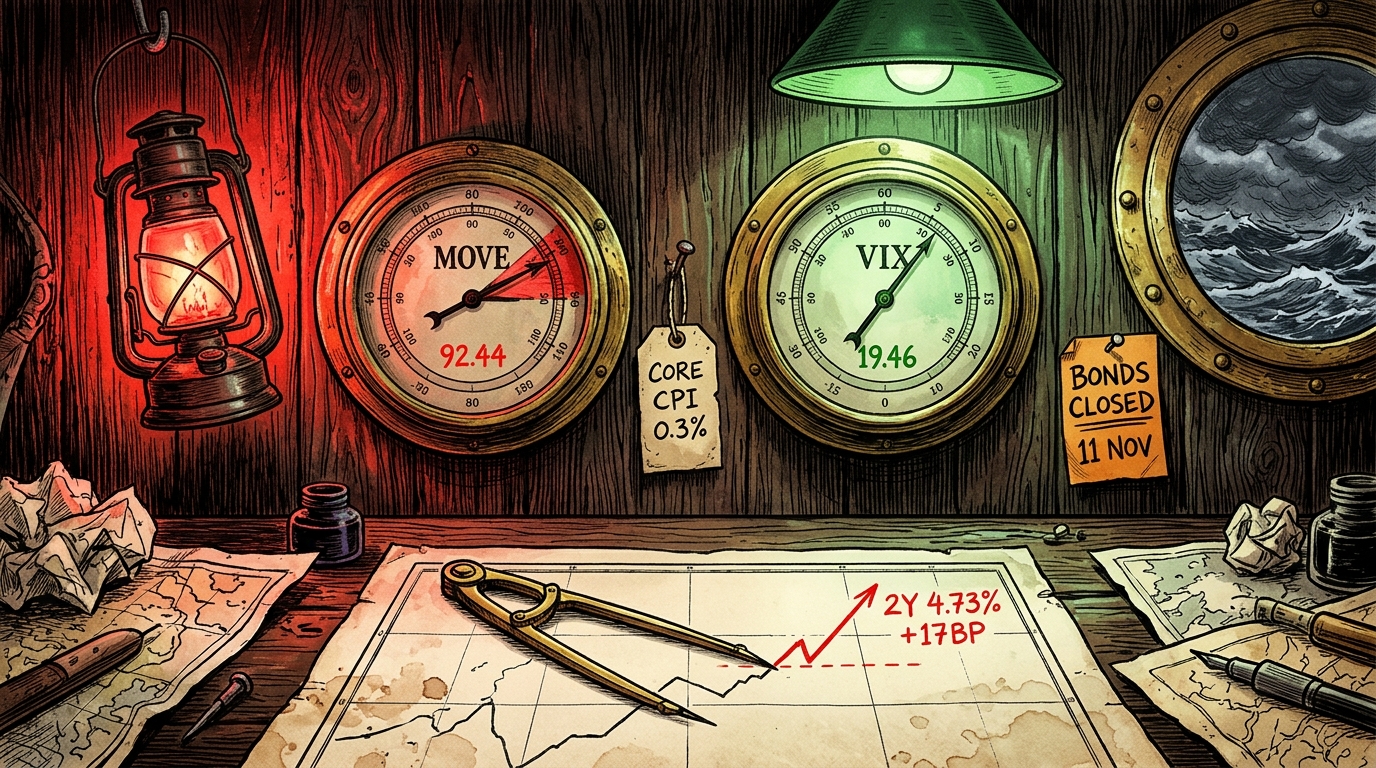
The 2-year rose 17bp and the VIX fell: why is the fear sitting in bonds and not in stocks?
Tuesday handed both markets the same news. October core CPI rose 0.3% against 0.2% expected, and Governor Waller had said that very morning that a print near 0.3% would justify considering a 50 basis point December hike. The 2-year Treasury yield rose 17 basis points to 4.73%. The 30-year rose 9. On the intraday path, a different measurement from the official close, the climb came in three steps, only one of them in the hour of the release.
Bond volatility answered loudly. The MOVE index, which measures how much the Treasury options market expects yields to swing, rose 7.5% to 92.44. Equity volatility answered with a shrug: the VIX fell 2.31% to 19.46 and its term structure stayed in contango at 0.94. The S&P 500 lost 0.38%.
Most macro courses say a sharp rise in the policy-sensitive end of the curve should travel. Higher expected rates raise the discount rate on every future dollar of earnings, and equity volatility usually rises with it, because the market is suddenly less sure what those earnings are worth. On Tuesday it did not travel. The fear stayed in the instrument closest to the Fed.
There are two honest readings, and they predict different things. In the first, equities believe the bond market’s story and like the ending: a Fed that hikes harder now gets inflation back sooner, which is what a flattening curve says, and stocks are pricing the destination rather than the journey. In the second, equities are simply looking elsewhere, at the AI trade, and have not done the rates arithmetic yet.
The two readings can be told apart. If the first is right, the 2-year should hold its gain when the bond market reopens on Thursday while the VIX stays below 20. If the second is right, a further rise in the front end should start to show up in equity volatility, because the arithmetic eventually arrives whether or not anyone is looking. The 30-year auction at 18:00 UTC on Thursday is the first reopening test of how much long money the market wants at 5.35%.
What is new this morning is the pairing. A 7.5% rise in bond volatility on a day equity volatility fell is a number most coverage will not put beside the other one, and it locates the December debate precisely: led by the front end, with equity volatility not yet joining in.
Phil’s Musing
I keep asking myself whether the stock market knows something or has simply not looked up. A 17bp move in the 2-year is not small, and the long end followed about half as far, which reads as a market expecting the Fed to win. I lean towards that being too comfortable, but I would not bet the house on my lean.
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
P.S. – Phil’s Footnote I assumed a hot core print would show up in the VIX. It showed up in the MOVE index instead, and the VIX went down. I had the right worry in the wrong market.
🗂 Desk Notes – Part 248 | 11 Nov 2026
Session read (§8.4)
SESSION BRIDGE: prior session (Tue) full reaction [SPX -0.384%, whole loss at the 14:30 UTC open, gap 1.27x the day’s move; 2-year CMT +17bp]; live premarket ES +0.57% / NQ +1.322% (07:45 UTC bar), re-quote ES +0.643% / NQ +1.557% (08:10 UTC bar), VIX prior close 19.46 (-2.31%, no premarket bar); threshold: soft (NQ premarket leg outside the 0.6% band; cash-session and VIX and crude legs silent).
- §8.4.1: SPX -0.384% is inside the normal envelope. VIX leg -2.31% (under 8%). Crude leg -0.93% (under 4%). The NQ premarket leg at +1.557% is abnormal on its own and fires the soft trigger with a candidate named (CoreWeave, coincidence only).
- §8.4.2 cash trigger: not met. No index posted a largest or second-largest move of the held 24-session window (ranks 12th to 18th). Sector spread 1.67pp (under 4.0). No table constituent moved 10% in the cash session (NVDA -5.47%).
- Capture: four contracts read twice (08:05 to 08:07 and 08:12 UTC), O/H/L/C and volume byte-identical on the 07:45 UTC bar; the 08:05 UTC forming bar changed between reads (control held). Sixteenth consecutive four-contract two-read capture.
- Basis: es_spx_basis +23.32, nq_ndx_basis +94.45 (futures daily close against cash close, up to an hour apart).
- No contract roll. December WTI last trades about 19 to 20 Nov: roll watch.
Mechanism read (§8)
| Tenor | 9 Nov | 10 Nov | Change |
|---|---|---|---|
| 3-month | 4.24 | 4.30 | +6bp |
| 2-year | 4.56 | 4.73 | +17bp |
| 5-year | 4.67 | 4.81 | +14bp |
| 10-year | 4.88 | 4.98 | +10bp |
| 20-year | 5.29 | 5.39 | +10bp |
| 30-year | 5.26 | 5.35 | +9bp |
Treasury CMT, two cache-busted fetches agreeing, top row 10 Nov on both; 14 tenors asserted. 2s10s 32 to 25bp, 2s30s 70 to 62bp, 20s30s -3 to -4bp. A front-end-led bear flattener. The 20-year holds the strict curve maximum, 43rd consecutive session on the ledger count (8 rows re-verified this run). H.15’s 10 Nov column is delayed to 12 Nov.
What it implies: the front end repriced the December meeting. Waller (09:00 UTC, prepared text): “a 50 basis point hike in the policy rate should be considered” if core CPI printed around 0.3% or higher. Core printed 0.3%. Bowman (20:30 UTC): CPI “suggests that 12-month core PCE inflation likely moved up further to 3.3 percent”. The dollar index rose 0.53%, dollar-yen 0.53%: confirming. VIX fell 2.31% while MOVE rose 7.5%: the vol signal sits in rates, not equities. VIX/VIX3M 0.943 from 0.955, still contango.
Majority test, 2-year. The intraday path (TVC:US02Y 1h, shape only, a different measurement from CMT): 4.546 (08:00 UTC bar) to 4.614 (09:00 bar), flat to 4.624 (12:00 bar), 4.681 (13:00 bar), 4.740 (14:00 bar), then 4.742 at 21:00. Three steps of roughly equal size. Step 1 sits in the Waller hour, step 2 in the CPI hour, step 3 in the hour of the cash open with no stamp held. No single release carries the majority. Published as: Waller and CPI each own one step; the third step has no named cause in this book.
Majority test, equities. Every index opened below its close (SPX gap 1.27x, NDX 1.55x, IXIC 1.10x, DJI 1.44x, RUT 1.22x the day’s move). The whole loss sat in the pre-open window that held both Waller and the CPI; neither is named for the index alone.
Refusal with its search, overnight NQ leg. Routes checked: TradingView news and news-story, BusinessWire via DJ flashes, Seeking Alpha, Benzinga, Stocktwits, TradingView ohlcv (regular session only, no extended-hours bar). Stamps found: CoreWeave release 21:05 UTC; Rigetti 21:05 UTC; StubHub 21:15 UTC; headlines tying Asia’s rise to CoreWeave at 01:32 UTC (headline only). Test run: the CoreWeave release precedes the overnight leg (it opened 23:00 UTC), so it passes the clock, but it is a single stock and no index weights are held, so it is published as a coincidence, not an index cause.
Candidate board (§8.3)
| Candidate | Class | Stamp (UTC) | Precedes majority | Disposition |
|---|---|---|---|---|
| Waller 50bp remark | 3 | 10 Nov 09:00 | no (one step of three) | published cause, first 2-year step only |
| October CPI | 1 | 10 Nov 13:30 | no (one step of three) | published cause, second step only |
| Third 2-year step | 6 | 10 Nov 14:00 hour | n/a | refusal: no stamp held |
| Nvidia China chips report | 3 | 10 Nov 15:26 | n/a | published cause, scoped to NVDA only |
| CoreWeave results | 2 | 10 Nov 21:05 | yes, for the overnight NQ leg | coincidence: single stock |
| Hormuz tanker mine claim | 3 | 11 Nov ~07:23 | no | coincidence: cause without effect, crude +0.41% at 08:10 |
| API crude inventory | 3 | 11 Nov 02:17 | no | Desk Notes only: relays disagree on direction (+9m against -9.8m barrels), unverified |
Causes without effects: the Hormuz mine claim (December WTI $86.39, +0.41% on settlement). Effects without causes: the third 2-year step; MOVE +7.5% beyond what the two stamped steps alone would size.
Hot News board
- Nvidia China chips inquiry, ROLLING, LEAD (opened 9 Nov). The Information (via Yahoo, 15:26 UTC 10 Nov): at least $7.5bn of hardware reached Chinese firms since 2023 via a network linked to Alice Huang, two unnamed sources. Board retained Joon Kim / Wachtell Lipton (WSJ via DJN 22:03 UTC). Chairs’ reply deadline today; Mast subpoena threat (tier 3 relay of ABC). Newsweek 23:33 UTC on the general counsel and a paused Commerce probe. NVDA -5.47% against SOXX -0.12%. Not known: whether the report is true, Huang’s attendance on 18 Nov, Nvidia’s statement. Next: today’s deadline, results 17 Nov, briefing 18 Nov.
- Middle East / Iran, ROLLING. Rubio at the G7: “no need” to resume major combat (AFP via Yahoo 16:12 UTC). Rezaei: talks “fake news”. Iran’s army: a tanker hit a mine in the eastern Strait of Hormuz this morning (Al Jazeera ~07:23 UTC, Iranian claim). December WTI $86.39 at 08:10 UTC. Not known: talks date, Hormuz status. Transit counts barred as figures.
- AI and tech rout, ROLLING. CoreWeave Q3 revenue $3.66bn, full-year guide raised to $13.0bn to $13.3bn (21:05 UTC). After-hours gain reported from 2.4% (Seeking Alpha 21:43 UTC) to 16% (TradingView News 06:19 UTC); unresolved. Next: Cisco and Applied Materials Thursday after the close.
- US midterms 2026, RETIRED. Epitaph: Democrats took both chambers; no market link for three editions; Mississippi certifies 13 Nov, no AP call found.
Overnight Excitement (§8.5)
FIRES and leads: December NQ +1.322% at the capture and +1.557% at the 08:10 UTC re-quote, 0.057pp over the 1.5% lead line and 0.443pp short of the 2.0% spine line. ES +0.643%, just above the 0.6% normal band and well short of the 1.0% trigger. Japan and Korea up, Hong Kong down, China up, on syndicated reports (direction only). UK labour data not captured.
Forward catalyst slate
- Today: bond market closed (SIFMA). No auction. Nvidia’s reply deadline to House chairs.
- Thu 12 Nov: jobless claims 13:30 UTC; Barr 15:00 UTC; 30-year auction 18:00 UTC; Cisco (call 21:30 UTC) and Applied Materials after the close; H.15 publishes the 10 Nov column.
- 17 Nov Nvidia results; 18 Nov House briefing request; FOMC 8 to 9 Dec. December WTI expiry about 19 to 20 Nov.
- Futures-implied December pricing leans heavily to 25bp over 50bp (investing.com relay, tier 3, qualitative only).
Divergence flags
- MOVE +7.5% against VIX -2.31%: rates and equity vol disagree.
- Gold spot -2.6% against futures -2.05%: different times and quantities, not a conflict.
- CoreWeave after-hours: four relays, four numbers.
- NVDA close: 168.89 (TradingView) against 168.80 and 166.95 on relays. TradingView used.
- Fed 50bp odds: 14% (SBS) against 9% (IndexBox) against 8.8% (investing.com). None published as a figure.
Regime and sensitivity read (§17.3)
Weathervane turn condition: a dated Fed communication moves DGS2 by 10bp or more while DGS30 moves by less than half. 10 Nov: DGS2 +17bp, DGS30 +9bp, half is 8.5bp. Not met by 0.5bp, and the 2-year move is shared between a dated communication and a data release. Non-advance number 38. Regime flag not tripped. Sensitivity running loose, stated openly, fifty-ninth edition.