Waller went first, Nvidia lost 5.5%, and December Nasdaq futures are up 1.6% anyway
 Ahoy there, Trader! ⚓️
It’s Phil…
The 2-Year Rose 17bp in 3 Steps. CPI Was Only the Middle One. Waller went first, Nvidia lost 5.5%, and December Nasdaq futures are up 1.6% anyway
October core CPI rose 0.3% month on month. Consensus was 0.2%. The headline rose 0.4% against 0.3%. The Bureau of Labor Statistics published no 12-month rate for headline or core, because October 2025 was never collected, so anyone quoting you a year-on-year figure this morning has made one.
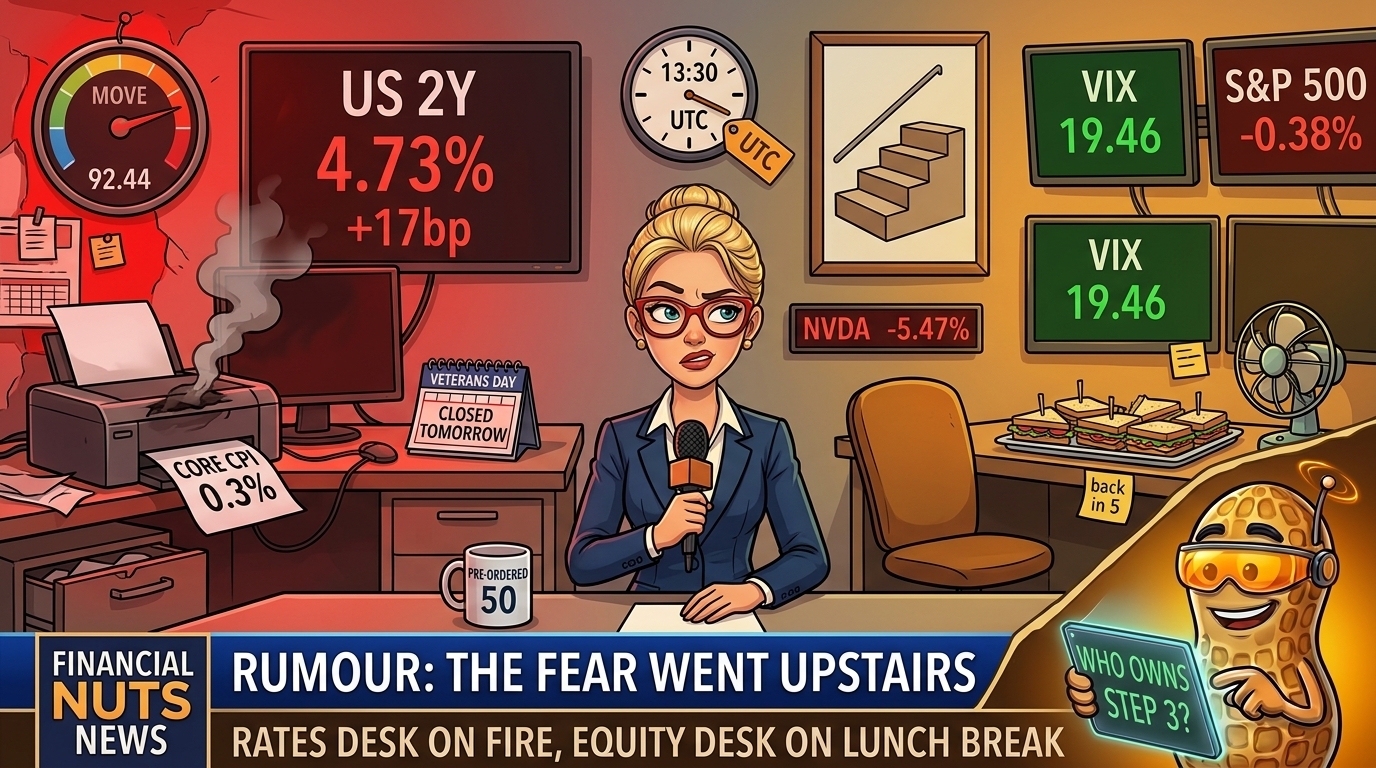
The 2-year Treasury yield rose 17 basis points to 4.73%. The 10-year rose 10 to 4.98%. The 30-year rose 9 to 5.35%. 2s10s went from 32bp to 25bp. A bear flattener, which is the bond market’s way of saying the next few meetings just got more expensive and the distant future can look after itself.
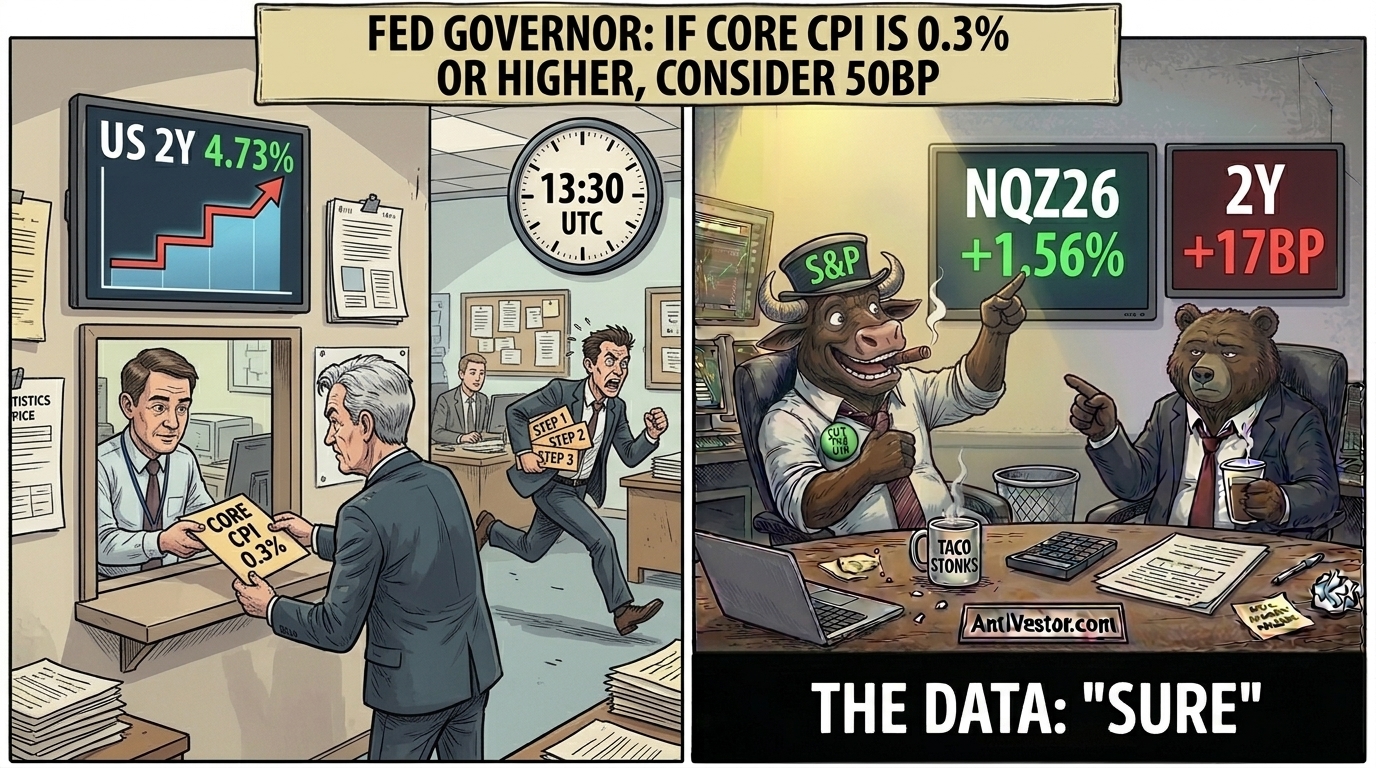
On the intraday path, which is a different measurement from the official close, the 2-year did not move once. It moved three times, in steps of roughly equal size. The first came in the 09:00 UTC hour, four and a half hours before the data, when Governor Waller told a London audience that a 50 basis point December hike “should be considered” if core CPI came in around 0.3%. The second came in the hour of the 13:30 UTC release, when core came in at 0.3%. The third step arrived an hour after that and carries no stamp in this book. So the CPI owns about a third of the move, Waller a third, and a third has no named cause in this book.
A governor named his price in the morning, the data met it in the afternoon, and the 2-year charged for both.
The S&P 500 fell 0.38% to 7,520.93, and all of that loss was in place at the 14:30 UTC open; the cash session spent the rest of the day clawing back a little. NYSE decliners beat advancers 1,815 to 903, which is less composed than the index makes it look. The VIX fell 2.31% to 19.46. Bond volatility, the MOVE index, rose 7.5%, more than the two stamped steps alone would obviously size. Governor Bowman added in the evening that inflation pressures are “persisting”.
Then there is Nvidia. It fell 5.47% to $168.89 after The Information reported that at least $7.5bn of its hardware reached Chinese firms through a network linked to Alice Huang. The semiconductor fund fell 0.12%. That is a cause, and it is scoped to Nvidia alone; nothing here says it moved an index.
This book has a tripwire for exactly this kind of day. The Weathervane turns when a dated Fed communication moves the 2-year by 10bp or more while the 30-year moves less than half as much. The 2-year rose 17. The 30-year rose 9. Half of 17 is 8.5. Only one of those three steps belongs to a Fed communication, so the test was generous to the turn, and it still failed. The cruise ship held its heading by half a basis point.
The one that mattered is the 17bp. Everything else, including a 5.5% fall in Nvidia, is a footnote to a front end that just priced December as live.
And this morning the futures have moved on. December Nasdaq 100 futures were up 1.56% at the 08:10 UTC re-quote, after a cloud company’s results; this book holds no index cause for that move. The bond market is closed for Veterans Day, so stocks get to open without the one market that spent yesterday worrying.
The One That Mattered
The 2-year rose 17bp on a hot core print and a governor who had floated 50 in advance. The S&P 500 lost 0.38% and the VIX actually fell. Bond volatility rose 7.5%. Two markets read the same Tuesday, one priced a live December and the other priced a mild inconvenience, and the front end has a habit of reading the Fed first. The 2-year rose 17bp and the VIX fell: why is the fear sitting in bonds and not in stocks? We went down that rabbit hole in today’s Macro Edge. https://antivestor.com/macro-edge
Hot News: Nvidia, $7.5bn and a Deadline
The chips story grew a number; the board hired a law firm
New since yesterday: The Information reported at 15:26 UTC that at least $7.5bn of Nvidia hardware reached Chinese firms since 2023 through a network linked to Alice Huang, citing two unnamed sources. Nvidia’s independent directors retained Wachtell Lipton to investigate. Three House committee chairs want a reply to their 18 Nov briefing request by today, and one has said he is prepared to subpoena. Nvidia fell 5.47%, and two brokers cut their targets. Not yet known: whether the report is right, whether Huang attends on 18 Nov, and what Nvidia says. Results are due 17 Nov.
Rolling: Iran. Rubio told the G7 there is “no need” to resume major combat; Tehran still calls the talks fake news. Iran’s army says a tanker hit a mine in the eastern Strait of Hormuz this morning, an Iranian claim. December WTI was $86.39 at 08:10 UTC, 0.41% above settlement, which is not the reaction of an oil market that believes it.
Retired: the midterms. Democrats took both chambers; three editions with no market link. Mississippi certifies on 13 Nov without us.
Our Top Trader Uses This 9:50 AM Secret to Target $500 Per Day Regardless Of Which Direction The Market Moves https://antivestor.com/ppp-webinar
Overnight Excitement
December Nasdaq futures rose 1.6% while a cloud company reported
December Nasdaq 100 futures led the night: up 1.32% at the 07:45 UTC capture, at 28,203.25, and up 1.56% at the 08:10 UTC re-quote. That is over this book’s 1.5% line, where overnight stops being a footnote and leads its own section. December S&P 500 futures were up 0.64% at the re-quote and Dow futures up a modest 0.17% at the capture, so the bid was mostly a technology bid.
This book has no index-level cause for that move. The only stamp held is CoreWeave, and it is one company. It reported at 21:05 UTC: revenue of $3.66bn and full-year guidance raised to $13.0bn to $13.3bn. How much it rose after hours depends on whom you ask. Reports run from 2.4% to 16%, and this book has no exchange bar to settle it. One company’s results are not an index cause either: the CoreWeave release came before the overnight move, and this book records that as a coincidence in time. Japan and Korea rose overnight, on syndicated reports.
Stock Market Edge
An index that lost 0.38%, all of it before breakfast
Premarket snapshot:
At the 07:45 to 07:50 UTC capture, December S&P 500 futures stood at 7,587.25, up 0.57% on Tuesday’s 7,544.25 close. December Nasdaq 100 futures were 28,203.25, up 1.32%. Dow futures rose 0.17% and Russell 2000 futures 0.39%. The 08:10 UTC re-quote had the Nasdaq contract at 28,268.75 and the S&P contract up 0.64%.
Sector rotation:
Technology was the worst SPDR sector fund on Tuesday at -1.15%. Financials led at +0.52%. The best-to-worst spread was 1.67 points. Falling stocks took 61% of NYSE volume.
Earnings or guidance:
Nvidia fell 5.47% against a 0.12% dip in its sector. Broadcom rose 3.91% and AMD 1.30%, so the rest of the chip aisle stayed open. After the close, CoreWeave raised guidance and Rigetti traded lower, on relay reports. Cisco and Applied Materials report on Thursday after the close, which is the next test of whether this AI bid has legs or just a good night’s sleep.
Cross-asset nuance:
The dollar index rose 0.53% to 102.22. December WTI settled 0.93% lower at $86.04, a calmer day after Monday’s 4.38%. Spot gold fell 2.6% to $4,032.02 and was $4,058.97 at 08:10 UTC. The 20-year Treasury, at 5.39%, still sits above the 30-year at 5.35%. The cash bond market is shut today.
Crypto Market Edge
Bitcoin fell on rates day, which it would like noted was a coincidence
Price snapshot:
CRYPTO bitcoin closed the 00:00 UTC day at $73,706.12, down 2.08%, and Coinbase bitcoin was $74,023.62 at 08:10 UTC. Ether closed the day at $2,050.86, down 3.83%.
Flows and positioning:
US spot bitcoin ETFs lost $201.1m on Monday, on TFTC relay data. Farside’s pages failed on two reads each, for a seventh edition running; the relay is labelled as one. No Tuesday row exists anywhere this book can reach.
Leadership and rotation:
Ether fell 1.75 points further than bitcoin. Strategy’s 9 Nov filing reports 1,036 bitcoin bought and 850,364 held, with no sales.
Catalysts and roadmap:
Jobless claims print at 13:30 UTC on Thursday and the 30-year auction at 18:00 UTC. Crypto’s next macro test is the bond market reopening.
TL;DR
- Core CPI rose 0.3% against 0.2%, and the 2-year jumped 17bp to 4.73% in three steps. Waller’s 50bp remark sits in the first; the CPI hour in the second.
- The S&P 500 fell 0.38% to 7,520.93 with the whole loss at the open. The VIX fell 2.31% while bond volatility rose 7.5%.
- Nvidia fell 5.47% on a report that at least $7.5bn of its hardware reached China via a Huang-linked network. Its sector fell 0.12%.
- December Nasdaq 100 futures were up 1.56% at 08:10 UTC after CoreWeave reported; no index cause is held for the move.
- Bitcoin fell 2.08% on the day to $73,706.12. The Weathervane’s tripwire missed by half a basis point: the 30-year rose 9bp, the limit was 8.5.
The Eleventh Hour Why Veterans Day falls on 11 November
The holiday marks the armistice that stopped the fighting of the First World War at the eleventh hour of the eleventh day of the eleventh month of 1918. It was renamed Veterans Day in 1954. The bond market observes it; the stock market does not.
Meme of the Day:
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
p.s. There are 3 ways I can help you…
- Option 1: Collect Morning Income
A complete guide to the Premium Popper system.
Written to be clear, concise, and immediately actionable.
>> Learn More Here
- Option 2: Collect Weekly Income
A complete guide to the Tag ‘n Turn system.
>> Learn More Here
- Option 3: Join the Fast Forward Mentorship
>> Join the Fast Forward Mentorship – trade live, twice a week, with me and the crew.
PLUS Monthly on-demand 1-2-1’s
No fluff. Just profits, Tag ‘n Turn Pulse bars, Poppers, and Patterns that actually work.