14 tenors up or flat, 2s10s at 31 before and after, bond volatility down 3.3%, and the committee meets Wednesday
⚓ Weathervane. The wind is coming from the long end. The policy rate has been frozen for most of the year whilst the term premium does the tightening, and the price of long money is set by deficits, issuance supply and a synchronised global duration bid rather than by the committee. Higher-for-longer stopped being a Fed decision and became a bond-market fact.
 Ahoy there, Trader! ⚓️
It’s Phil…
Oil settled at $103.27 and the 20-year closed at 5.37%, so is the bond market pricing the barrel or the committee?
The textbook is short: an oil shock is an inflation shock, an inflation shock is a policy shock, and a policy shock lives at the front of the curve. Read as inflation, Friday’s 3.82% in December WTI should have moved the 2-year first and most and flattened the curve.
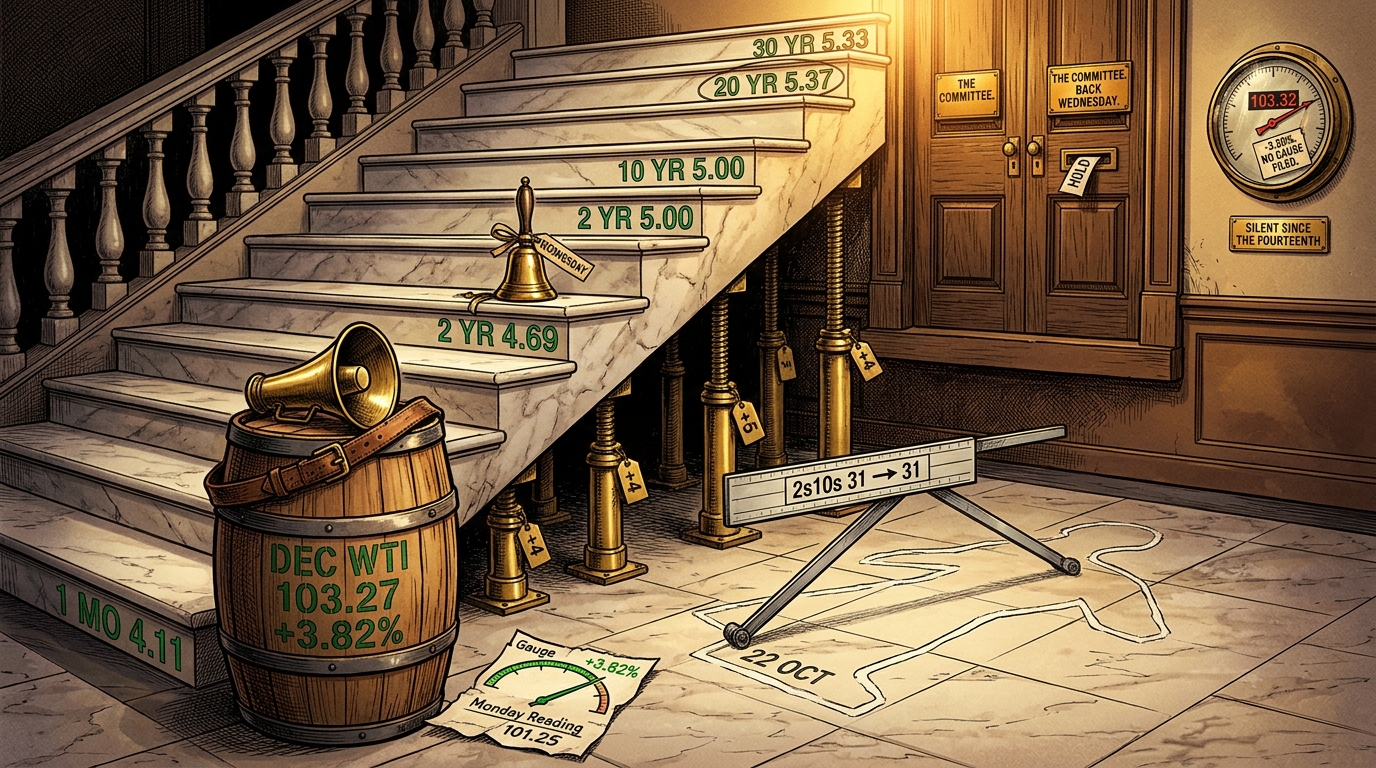
The tape: the 2-year rose 4 basis points to 4.69%, the 10-year 4 to 5.00%, the 20-year 5 to 5.37%, top of the curve for a 31st consecutive session, the 30-year 4. The 2s10s was 31 basis points on Thursday and 31 on Friday; the 2s30s 64 and 64. Eleven of fourteen tenors rose, three were unchanged, none fell. The dollar rose 0.13%. Bond volatility fell 3.30% to 103.32; no cause is named for that either.
So the number nobody else will put beside another number today: a 3.82% front-month oil move and an unchanged 2s10s. The whole curve moved by about the same amount, the long end fractionally ahead. That is not the textbook’s drawing of a barrel story but of a term premium story, the Weathervane’s heading, though a parallel shift is also what a lift in the whole expected policy path draws, and we hold no term premium series to separate the two.
One afternoon is one observation. The relay this book does not print prices a hold on Wednesday and a hike by December; the bill curve rising from 4.11% to 4.44% across the year says the same in an instrument we can quote. On Friday the one-month bill was unchanged and the one-year rose 3 basis points. What moved most was the price of long money, on a day the loud story was the price of short energy.
Then Monday. December WTI read 101.25 on the 06:00 UTC bar, down 1.96%, and 100.84 by the 09:05 UTC bar, down 2.35%, after a Sunday statement that there would not be a strike that day, which is speculation and not a retrieved cause. The barrel gave back more than half of Friday before the committee had said a word; the curve waits for Wednesday at 18:00 UTC.
The testable version: if Wednesday’s statement moves the 2-year by more than the 20-year, the committee is back in the driving seat and the Weathervane has a question to answer. If the 20-year keeps leading, Friday was the regime and oil was the weather. If neither moves, Wednesday settles nothing.
Phil’s Musing
A curve that lifts eleven tenors and leaves the 2s10s where it was has told you who is in charge, and it is not the people meeting on Wednesday. I would rather read one unchanged spread than ten forecasts of the statement. What changes my mind is the 2-year outrunning the 20-year on Wednesday afternoon.
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
P.S. – Phils Footnote I went looking on Friday for the oil shock in the front end and found it in the 20-year instead, which is roughly where this letter has been finding everything for six weeks. I had assumed the barrel at 103 would at least rattle the 2-year on a Friday before a Fed meeting, and it rattled nothing. The honest admission is that I no longer know what would make the front end move on its own, and the committee gets its chance to show me on Wednesday.
🗂 Desk Notes – Part 236 | 26 Oct 2026
Raw briefing. Observations, not trades. Marks against the full Friday 23 October reaction plus the weekend and the Monday 26 October premarket.
Session read (§8.4)
SESSION BRIDGE: prior session (Fri 23 Oct) full reaction: December ES -0.58% (7,704.50 to 7,659.75), cash SPX -0.52%, DJI -1.23%, NDX -0.00%, RUT -0.29%; VIX +2.21% to 19.45; December WTI +3.82%; live premarket ES +0.17% / NQ -0.04% / YM +0.33% / RTY +0.32% on the 07:45 to 07:50 UTC bar, VIX 19.63 on the 07:45 UTC 15-minute bar, +0.93% on the close; threshold: none.
Reasoning. Equity leg: the December ES prior-session move of -0.581% sits 0.419 points short of the 1.0% investigate band. Volatility leg: VIX +2.207%, 5.793 points short of the 8% condition. Commodity leg: December WTI +3.820%, 0.180 points short of the 4% condition, the nearest miss of the three. No limb of §8.4.1 fires, so the carry-over note does not fire and the threshold is none.
§8.4.2 trips on all three limbs, so the candidate board and the decomposition are mandatory regardless. Limb (a): the Dow’s -1.235% is its largest daily fall of the 14 sessions 6 to 23 October, window locked as a dated series; the S&P 500’s -0.519% is not in its own top two and the Nasdaq 100’s -0.004% is the smallest absolute daily move of its window. Limb (b): sector spread 4.527 points against 4.0. Limb (c): LKQ -22.474% against 10%, with Robert Half +21.736%, Bloom Energy -11.237%, Crown Castle +9.06% behind it.
The close-to-open window: ES 7,659.75 at the Friday settlement to 7,672.75 on the capture bar, +13.00 points; the Globex session so far ran 7,651.75 to 7,698.50. Capture protocol: the 07:45 to 07:50 UTC bar read at 08:05:14Z and 08:12:14Z (ES, NQ) and 08:06:17Z and 08:13:12Z (YM, RTY), byte-identical on open, high, low, close and volume on all four, with the still-forming 08:05 bar mutating on all four between reads (ES volume 118 to 2,711). Taken by the equities lane. Fourth consecutive on-time, four-contract capture. Container clock verified at 07:38:19Z; UK is on GMT from 25 October so UK time equals UTC, whilst US clocks do not change until 1 November, so the 07:45 UK bar is 03:45 EDT, not 02:45 as the standing brief still says.
Contract roll: none near. December contracts are front on all four equity futures; next roll is the third Friday of December. WTI December is front by volume (313,170 against January’s 140,956). Brent January overtook December by volume on Friday (343,015 against 314,970) and December expires 30 October, so every Brent figure this week names its month.
Basis: December ES less SPX 36.07 (Thursday 41.07). December NQ less NDX 160.22 (Thursday 183.31). December YM less DJI 178.84.
Overnight Excitement (§8.5)
Silent. Largest overnight move on US futures is December Dow at +0.326%, 0.674 points short of the 1.0% trigger. ES +0.170% and RTY +0.323% inside the 0.3 to 0.6 normal band or just under it; NQ -0.038%. At the 08:15 UTC re-quote RTY read +0.187%, so it crossed from inside the normal band to below it on a price move of 0.14%, the limb-two crossing limb one cannot see, for a fourth consecutive edition. No non-US central bank decision landed outside US hours. Asia lower on syndicated reports: Nikkei down, CSI300 down as the plenum opened, Kospi down, Taiwan closed, Europe seen opening higher; direction only, no level published, and the Japan and China closure tests both returned a 26 October bar, so both markets were open. Nothing is forced.
§8.3 candidate cause board
Both columns. Class per ruling R, earliest stamp, whether it precedes the majority of the move it is offered for, and disposition.
Effects without causes
| Effect | Class | Stamp | Precedes majority | Disposition |
|---|---|---|---|---|
| The Dow’s 73.76% intraday leg, 481.54 points | 6 | PMI 13:45Z and Michigan 14:00Z sit inside the leg; untestable without an intraday path | no | refusal, published |
| Gold spot -0.744% to 3,994.00 on a session oil rose 3.820% and the dollar 0.133% | 6 | none | no | refusal, published |
| Bond volatility -3.300% to 103.322 on a session every tenor rose or held | 6 | none | no | refusal, published |
| The unstamped 12:00Z-hour Treasury dip and full recovery before the PMI, on the TradingView path, shape only | 6 | 12:00Z bar | no | desk notes only: no wire stamp located in the hour and no CMT magnitude attaches to a path read |
| Energy equities +2.605% on a session the index fell 0.519%, the mirror of Thursday’s energy fall on a Brent rise | 6 | none | no | desk notes only: second observation of the Part 235 tracked series of sector sign against front-month sign; filable at five |
Causes without effects, and causes scoped to one instrument
| Candidate | Class | Stamp | Precedes majority | Disposition |
|---|---|---|---|---|
| American Express Q3 results and 5% workforce cut, scoped to AXP | 2 | 2026-10-23T11:34:50Z | yes, gap share 85.105% | published cause, scoped to AXP alone |
| LKQ preliminary Q3, guidance withdrawn, chief executive change, scoped to LKQ | 2 | 2026-10-23T12:00:00Z | yes, gap share 85.347% | published cause, scoped to LKQ alone |
| SpaceX talks for 80,000 US cell sites, Bloomberg report via Benzinga | 3 | 2026-10-23T04:26:05Z | yes for T (gap 55.249%) and TMUS (gap 66.857%); the CCI decomposition is degenerate, open +15.464% to close +9.06% | labelled speculation in AVE and the Snippet, with the clock stated |
| SLB Q3 results, offered for SLB +7.084% | 2 | 2026-10-23T10:50:00Z | no, gap share 11.681% | refusal, published |
| Brent and WTI on Houthi and Iran-strike reports, offered for energy +2.605% | 3 | 2026-10-23T09:16:27Z | not testable at sector scope; the sector proxy’s gap is not held | coincidence, published |
| Flash October PMIs, composite 57.6, manufacturing 56.0, services 57.9 (single source) | 1 | 2026-10-23T13:45:00Z | no; SPX had gapped 66.038% of its move before it | coincidence, published |
| Michigan final October sentiment 48.0 against 46.3 preliminary; 1-year inflation 4.7, 5-year 3.5 | 1 | 2026-10-23T14:00:00Z | no | coincidence, published |
| Staples -1.922% one session after +3.306% | 5 | session | no | coincidence, published as a signature |
| Trump “there will not be a strike today”, offered for the Monday crude give-back | 3 | 2026-10-26T02:44:59Z (first wire carrying the quote; a 23:21:33Z Sunday Trading Economics item carried an earlier, different remark) | yes against every Monday read held | labelled speculation in AVE and the Snippet |
| Musk post on neocloud consolidation, offered for December Nasdaq -0.038% | 3 | 2026-10-26T01:57:06Z | n/a, no index effect to attribute | coincidence, published |
| Brazil runoff result, offered for US futures | 3 | 2026-10-26T01:55:17Z | n/a | desk notes only: the instruments it moved are Brazilian ADRs and a country fund quoted on a tier-3 wire; US index futures sat inside the normal band |
| No Federal Reserve communication of any kind, blackout in force before the 27 to 28 October meeting | 6 | none | n/a | desk notes only: the expected null, seventh consecutive edition |
| Asia lower on syndicated reports | 3 | 2026-10-26T07:08:12Z | n/a | desk notes only: a level is barred and §8.5 is silent |
Majority test, run per Lesson 156 against every locked read of the premarket contract (December YM at 07:45Z, 0.326%, and 08:15Z, 0.326%): the Monday speculation row and the Monday coincidence row are both stamped before the first read and pass. Both Friday published causes are stamped before the 13:30Z open and before the gap they are offered for. Null rate per ruling S: none of the last three editions names a session-level cause; this one names two constituent-scoped causes and admits the index leg.
The named cause from Part 235, Lam Research’s 21 October filing scoped to LRCX, is marked on follow-through per ruling U: LRCX closed 230.10 from 230.15 on Friday, -0.022%, and the semiconductor proxy rose 0.528%. No instrument kept responding. MARKED-MISS on follow-through, the third consecutive ruling-U miss.
Mechanism read (§8), full
| Tenor | 23 Oct | 22 Oct | Change bp |
|---|---|---|---|
| 1 Mo | 4.11 | 4.11 | 0 |
| 1.5 Mo | 4.11 | 4.10 | +1 |
| 2 Mo | 4.16 | 4.16 | 0 |
| 3 Mo | 4.22 | 4.22 | 0 |
| 4 Mo | 4.30 | 4.29 | +1 |
| 6 Mo | 4.30 | 4.29 | +1 |
| 1 Yr | 4.44 | 4.41 | +3 |
| 2 Yr | 4.69 | 4.65 | +4 |
| 3 Yr | 4.75 | 4.72 | +3 |
| 5 Yr | 4.82 | 4.78 | +4 |
| 7 Yr | 4.89 | 4.86 | +3 |
| 10 Yr | 5.00 | 4.96 | +4 |
| 20 Yr | 5.37 | 5.32 | +5 |
| 30 Yr | 5.33 | 5.29 | +4 |
Eleven tenors rose, three were unchanged, none fell, recomputed over all fourteen in code. Spreads: 2s10s 31 (31), 2s30s 64 (64), 20s30s -4 (-3). The 20-year is the strict maximum of the curve for a 31st consecutive published session, 10 September to 23 October, bounded at the start by the 9 September tie with the 30-year; the run is recomputed over all fourteen tenors per session from the full dated series and nothing is claimed before 10 September. CMT read on three agreeing fetches with two different cache-bust parameter names, top row asserted as 10/23/2026, header asserted at fifteen fields. H.15 carries no 23 October column; 55 of 55 overlapping cells matched for 16 to 22 October.
What moved: a parallel-ish level shift of 3 to 5 basis points from one year out, bills flat. What it implies: Friday’s oil move did not re-price the committee. A 3.82% front-month oil day that priced as inflation would show in the 2-year ahead of the 20-year; the 2-year took 4 and the 20-year took 5, and the 2s10s did not move. That is the shape of a term premium day, which is the Weathervane’s heading, and it happened with bond volatility falling 3.30% to 103.32. The dollar rose 0.13% to 101.75, the yen barely moved at 156.806, the franc weakened 0.55%, so the dollar confirmed the rates direction mildly. VIX rose 2.21% to 19.45 against VIX3M 20.48, ratio 0.950 from 0.946, still in contango, the ratio having risen 0.004 on the session against candidate 8’s 0.070 condition.
The one artery: the Dow. Its 652.82-point fall decomposes 171.28 points of gap (26.237%) and 481.54 points of session (73.763%). The Nasdaq 100’s net 1.16-point fall decomposes a 110.87-point gap down and a 109.71-point session recovery, so shares are not published for it. The S&P 500’s 39.75-point fall was 66.038% gap. Three indices, three different shapes, one afternoon. The ES futures and the cash gap: the index opened 26.25 points below Thursday’s close and the futures had already made most of that overnight.
Credit, duration-aware for a third edition. High yield -0.065%, investment grade -0.412%, long Treasuries -0.489% on 35,149,579 shares against 65,635,115 Thursday. Durations as at 22 October: 3.17, 7.63 and 14.96 years. The issuer’s option-adjusted spreads now carry a 22 October stamp: high yield 297.81 basis points from 287.23 as at 21 October, a 10.58 point widening across Thursday’s session; investment grade 91.91 from 90.86, 1.05 points. The widening Part 235 refused to name is published and it is confined to high yield. Friday’s spread change is not yet published and is not named.
Gold: spot 3,994.00, -0.744%, December 4,007.9, -1.293%, silver -1.923%, copper +1.711%. Gold down on an oil-up, dollar-up, yields-up afternoon is consistent with real yields doing the work and this book holds no real yield series, so it is a refusal, not a mechanism. The aligned carry is on its every-third-edition schedule and was not run; the unaligned December-less-spot gap of 13.9 is recorded and is not the carry.
Crude: December WTI 103.27 (+3.820%), January 100.94, December-January spread 2.33 from 1.95; December Brent 116.72 (+3.137%), January 111.70, spread 5.02 from 4.51; Brent-WTI December 13.45 from 13.70. WTI session range 98.84 to 103.92 on the 23 October trade date. Wire superlatives on Brent conflict with each other (a four-year high against a five-month high) and no window is held; neither is published. Monday 06:00Z bars: WTI 101.25 (-1.956%), Brent 114.90 (-1.559%).
Crypto: BTC 81,086.26 Friday, 80,781.44 Saturday, 80,047.76 Sunday, -1.602% Thursday to Sunday, Saturday low 79,162.65; ETH 2,326.97 Sunday, -2.523%. Flows: 23 October BTC -137.9 million provisional on a blank HODL cell (IBIT -110.3, FBTC -31.8, MSBT +4.2, the rest printed zero); ETH +4.4 million provisional on a blank ETHV cell (FETH 3.6, MSSE 0.8, ETHA 0.0). Both blanks are the VanEck product on both products. Asymmetry diagnostic: both products rendered one blank, so it returns NULL for an eighth consecutive edition. Earliest row 7 October from 5 October, two trading sessions eroded in one edition after Part 235’s stall. Frozen cumulatives 57,251 and 12,748. Second-venue gap on Sunday’s BTC mark 5.40 dollars, registry observation only.
Enumeration of locked single-name moves (R8)
Floor 5%, every confirmed name, published or admitted: LKQ -22.474% (published, cause named and scoped); RHI +21.736% (published, Q3 beat, stamp not held, admitted as unstamped); BE -11.237% (published, second-day post-earnings, stamp not held); FIX -9.263% (published, stamp not held); CCI +9.06% (published under speculation); FCNCA +8.152% (published, 8-K on EDGAR, no wire stamp held); T -7.960% (speculation); TMUS -7.715% (speculation); SLB +7.084% (published refusal); HAL +5.212% (published with the energy proxy, no stamp). Instruments above their recent range: DJI -1.235% (admitted unexplained); CLZ2026 +3.820% and BRNZ2026 +3.137% (coincidence row); MOVE -3.300% (refusal). Nothing locked above the floor is absent from every file.
Divergence flags
- The Dow fell 1.235% and the Nasdaq 100 fell 0.004% on the same afternoon, one session after a 2.919 point divergence the other way. The spine pair.
- Gold spot fell 0.744% on a session oil rose 3.820%, the dollar rose 0.133% and every Treasury tenor rose or held.
- Bond volatility fell 3.300% whilst every tenor rose or held and equity volatility rose 2.207%.
- The energy proxy rose 2.605% on a Brent-up day after falling 0.866% on Thursday’s Brent-up day. Second observation of the sign series; filable at five.
- The two semiconductor proxies rose 0.528% and 0.736%, divergence 0.208 points, session three of ten on the Part 233 shot, none of the four falsifier sessions in.
- Breadth: NYSE 0.575 and Nasdaq 0.660, both below one, the Part 225 window closed without a fourth straddle.
- The flow table’s erosion resumed at two sessions in one edition after a one-edition stall.
- Crude settled up 3.820% on Friday and read down 1.956% on the Monday 06:00Z bar, a round trip larger than the Friday session’s net move in one weekend, with a labelled speculation candidate first quoted at 02:44:59Z Monday.
Carry-over note (§10.6)
Does not fire. No §8.4.1 limb tripped and Phil has flagged no catalyst. §8.4.2 tripping forces the board, not the note.
Capture-to-publish re-quote (§11.9.1, both limbs)
Pre-draft drift, read window 08:30:15Z to 08:36:40Z, sixteen keys, zero over the 2% threshold, zero movable figures un-quoted. Limb one, price: ES 7,672.75 to 7,670.50 (-0.03%); NQ 29,106.75 to 29,097 (-0.03%); YM 52,565 to 52,563 (-0.00%); RTY 2,793.5 to 2,789.6 (-0.14%); December WTI 103.27 to 101.30 (-1.91%); January WTI 100.94 to 99.23 (-1.69%); December Brent 116.72 to 115.04 (-1.44%, feed lagging ten minutes); January Brent 111.70 to 110.11; December gold 4,007.9 to 4,027.8 (+0.50%); silver 53.949 to 54.11; copper 6.51 to 6.52; gold spot 3,994.00 to 4,014.27 (+0.51%); BTC 80,047.76 to 80,054.17; ETH 2,326.97 to 2,320.95; VIX 19.45 to 19.60 (+0.77%, 08:15Z bar); DXY 101.751 to 101.805. Limb two, distance to thresholds: ES +0.140%, 0.860 short of the 1.0% trigger and 0.160 below the 0.3 band low; NQ -0.071%, 0.929 short; YM +0.323%, 0.677 short and 0.023 above the band low; RTY +0.183%, 0.817 short and 0.117 below the band low, having crossed below it since the capture. Crude’s 1.91% drift sits 0.09 short of the 2% refresh line and is requalified in the copy by carrying both the settlement and the Monday read. Second drift run, read window 09:12:10Z to 09:18:30Z: December WTI 103.27 to 100.84 (-2.353%, OVER the 2% line) and January WTI 100.94 to 98.80 (-2.120%, over), requalified in the copy by carrying the 09:05Z read beside the settlement and the 06:00Z read; December Brent 116.72 to 114.56 (-1.851%, ICE feed ten minutes behind); ES 7,683 (+0.304% on Friday, crossing INTO the normal band, 0.004 above its low); NQ 29,182.5 (+0.222%, sign flipped from the capture); YM 52,659 (+0.506%, 0.494 short of the trigger); RTY 2,794.0 (+0.341%, back inside the band); gold spot 4,015.02 (+0.526%); BTC 80,124.89; ETH 2,320.58; VIX 19.24 (09:00Z bar, -1.080% on the close); DXY 101.759. Section 8.5 stays silent on every contract; the largest clearance to the 1.0% trigger is YM at 0.494 points.
Forward catalyst slate
- Mon 26 Oct: 2-year note auction (new issue, CUSIP 91282CRU7), 13 and 26-week bills, 13:00 ET; offering size not obtainable on any permitted route this run. Dallas Fed manufacturing 14:30Z. Verizon reports pre-market.
- Tue 27 Oct: FOMC day one. Durable goods 12:30Z, Case-Shiller 13:00Z, Conference Board confidence 14:00Z, new home sales; 5-year note auction 13:00 ET. Forecast and previous fields conflict between routes on durables, Case-Shiller and new home sales; neither route’s figure is published.
- Wed 28 Oct: FOMC statement 18:00Z, press conference 18:30Z, confirmed on the Board’s own calendar; no projections. Bank of Canada 13:45Z. Microsoft and Alphabet after the close (tier 2, wire-relayed, no company release checked). A 28 October 2-year record on the auction feed is probably the floating-rate note and is not printed as a second fixed-rate 2-year.
- Thu 29 Oct: Q3 GDP advance and September PCE together at 12:30Z (GDP forecast 3.2 against 2.2 previous, core PCE 0.3 against 0.2, both routes agreeing); ECB 13:15Z; 7-year note 13:00 ET; Amazon after the close (tier 2); Strategy reports.
- Fri 30 Oct: ECI 12:30Z; Chicago PMI 13:45Z; Daly 16:00Z and Musalem 16:30Z, the first post-blackout speakers; Bank of Japan overnight. Brent December last trades.
- Not this week: an October jobs report. The BLS October schedule carries only the September report, released 2 October. Next CPI 10 November, next PPI 13 November.
- Ledger tests coming: the Part 233 semiconductor divergence shot runs to 3 November. The Part 232 ether shot needs scorable sessions by 10 November and had none on Friday.
Regime and sensitivity read (§17.3)
Weathervane carried, not rewritten. The 23 October curve is a 3 to 5 basis point level shift with the long end taking the most, which runs with the Weathervane for the first time in three sessions after two sessions against it. Turn condition: DGS2 moved 4bp, short of the 10bp limb; no Fed communication exists in the blackout, so the communication limb is inapplicable; progress 0 of 2, twenty-sixth consecutive non-advance. The split recommendation is twenty-five editions unanswered.
Candidates: 1, dollar non-response, not scored for a twenty-fourth edition for want of its condition text; the dollar rose 0.133% on a 4bp 2-year, which is a response, not a non-response. 4, retired, scoreable and would not have fired; the front end moved with the rest of the curve. 5, counter 3, unchanged; the 20-year reopening of 21 October still shows null results on the Treasury feed. 6, scoreable on a level shift and still without a numeric threshold in the live file. 8, scored: the ratio rose 0.004 against a 0.070 condition, correctly silent for a sixth consecutive edition. 9, scored: the Dow’s gap share is 26.237% against an 80% condition, both exchanges closed below one, limb two fires and limb one does not; zero of two, does not fire.
Sensitivity read: running LOOSE, forty-seventh consecutive edition, stated openly. Four of nine candidates still carry no numeric condition text. The spine today is a cross-index divergence and no candidate reads two indices against each other, which is the same gap as Part 235’s sector-against-index spine in a new coat. The diagnosis stays specification.
Retrieval and route notes
- Twelve Data was absent from this session; registry substitutes used throughout. Twelve Data connector needs reconnecting.
- Zero 429s across four research lanes, one re-quote agent and the main thread; two-parallel discipline held with one pair at 25 seconds and two inter-batch gaps under 40 seconds, both noted by the lanes.
- CMT: first fetch returned the correct session; two cache-busted fetches with different parameter names agreed; protocol kept.
get-ohlcvreturned no extended-hours bars on single equities, again; the after-hours deliverable rests on wire stamps.- Farside: both products rendered one blank cell on both reads, so both 23 October rows are provisional. Earliest row 7 October.
- The S&P Global public PMI page confirmed the manufacturing and composite values and not the services value, so services is single-sourced at tier 2.
- Treasury upcoming auctions return null offering sizes for this week’s three coupons and TreasuryDirect is robots-disallowed, so no size is published.
- The Stocktwits equities board carries BTC without a suffix at rank 23: that is the Grayscale Bitcoin Mini Trust, not spot. COMP.X is the Compound token, not the Nasdaq Composite. Both for the registry collision list.
- Diff loop ran after the lanes returned rather than while they were out, because the dispatch call blocked the main thread; the order amendment B3 asks for was not met this run and is logged.
Re-cut record (§14.4)
- Delivered 09:24Z; re-cut on the editor’s live feedback at 09:50Z, under the antivestor-humour-and-image skill loaded at his instruction.
- Error corrected in all four reader-facing files: Friday was described as “the reverse of Thursday” and “sides swapped”. It was not. Thursday the Nasdaq 100 fell 2.90% whilst the Dow held; Friday the Dow fell 1.23% whilst the Nasdaq 100 held. The reverse of Thursday would have been the Nasdaq 100 up. The corrected frame is two sell-offs in two sessions with no overlap, one index at a time.
- Masthead re-led on the finding rather than the fact; two alternates re-cut. Inside Edge headline given a point, no humour.
- AVE letter: three print formats added, each once, each placed before the line it sets up: a corrections notice before the flow refusal, a classified for the 481.54 unexplained Dow points, a footnote on the lift line. Prose de-numbered; exact figures stay in the tables and here.
- All three image prompts rebuilt by the method: contrast stated as the joke, the day’s instruments as props with words, one signature each in one place, two light sources in conflict. Hazel and Percy named and not described; the gate’s character-reference block retained as names only. Meme rebuilt without the costume swap, which rested on the corrected error.
- Spine, lock, candidate board, threshold and bridge unchanged. Lock additions:
dji_intraday_points_rounded482,t_volume_shares_m99.8,t_prior_volume_shares_m54.4. - Pre-delivery drift re-run on a fresh live read at 11:20Z (ICE Brent 11:10Z, VIX 11:00 to 11:15Z): 16 checked, 2 over the 2.0% line, both crude again. December WTI 101.03 against the 103.27 settle, down 2.17%; January 98.84, down 2.08%. Both sit between the 06:00Z and 09:05Z reads already carried in the copy, so the requalification stands and no figure was re-timestamped. ES 7,668.75, NQ 29,152.5, YM 52,578, RTY 2,787.6, VIX 19.74, gold spot 4,012.33, BTC 80,250.70, Brent December 114.95.
- Macro Edge image re-cut at 11:50Z on the editor’s ruling that it was “still a little bland”: style block kept, scene rebuilt by the method (the jacked-up fourteen-tread staircase under a shut committee door, the barrel with the megaphone at its foot, three depth layers, worded props, one reacting element, two light sources). Macro Edge body unchanged.
- Gates after the re-cut: qa_check all gates passing; validate clean with zero failures and zero warnings; audit residuals all index names, part numbers and section references; one §14.2b pass on the re-cut argument, every item raised applied.