Two war hedges, one election result, opposite answers on the same Wednesday
⚓ Weathervane. The wind is coming from the long end. The policy rate has been frozen for most of the year whilst the term premium does the tightening, and the price of long money is set by deficits, issuance supply and a synchronised global duration bid rather than by the committee. Higher-for-longer stopped being a Fed decision and became a bond-market fact. The cruise ship is holding this heading.
 Ahoy there, Trader! ⚓️
It’s Phil…
If the wires read the election as less war and oil fell 8.3%, why did spot gold add 3.3% the same day?
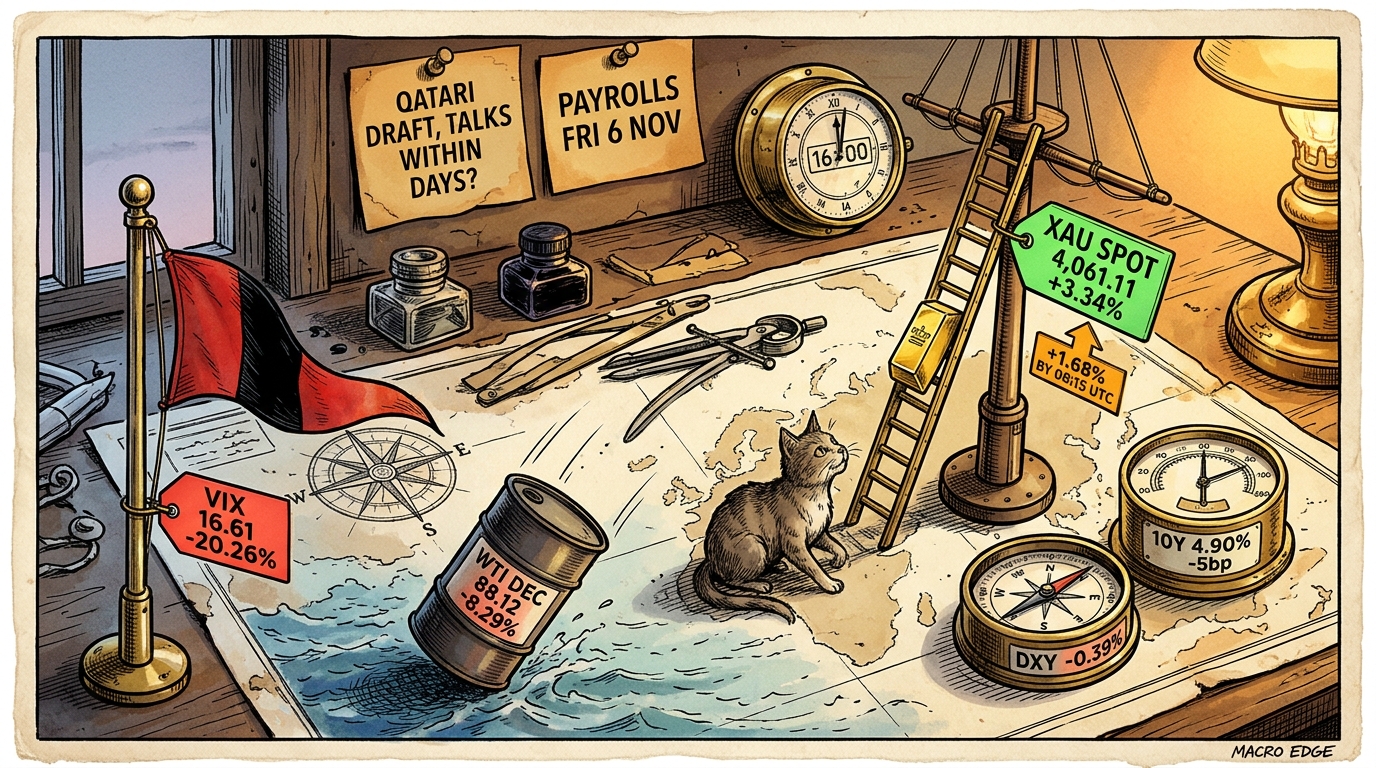
Start with what Wednesday did. The Dow rose 3.03% and the S&P 500 1.58%. December WTI fell 8.29% to 88.12 and January Brent 8.67%. The wires read the Democratic Congress as less appetite for a wider war with Iran, and JD Vance said as much on the day, though oil had already lost 7.36% on Monday, before the vote. Meanwhile spot gold rose 3.34% to 4,061.11.
The textbook keeps gold in two drawers. In the first it is a haven: it rises when fear rises and gives the gain back when the fear goes. On Wednesday the fear went. The VIX fell 20.26% to 16.61, its ratio to VIX3M dropped to 0.88, and the MOVE index fell 6.09%. On the haven account gold should have fallen.
In the second drawer gold is a currency with no yield, so it rises when the dollar and real yields fall. On Wednesday the dollar index fell 0.39% and the nominal 10-year yield 5bp to 4.90%. Both point gold up. Neither points it up 3.34%: gold moved 8.54 times as far as the dollar index. This book holds no real-yield series to test the size.
Here is the comparison worth keeping. Oil and gold are both said to carry a war premium. On the same day, one lost 8.29% and the other gained 3.34%. If both were pricing the same war, one of them priced it wrongly. If they were pricing different things, gold was never mostly a war trade this week.
The timing is the one thing this book can add. Gold stood at 3,951.82 at 05:00 UTC on Wednesday, twenty minutes after AP’s Senate story, and 57% of the day’s gain came in the next two hours. So gold did react to the result, and fast. It reacted in the opposite direction to oil. It was 4,129.16 at 08:15 UTC this morning. This book holds no trigger for the size.
What would settle it? One level, one date. If spot gold closes Friday, after payrolls, below Wednesday’s close of 4,061.11, it was the war hedge running late and giving the premium back. If it closes above, gold is pricing something other than the war. The earlier test still stands: above 3,951.82 at Friday’s close. At 07:50 UTC it was 169.52 above.
Phil’s Musing
I always thought of oil and gold as the two things you hold when the news gets frightening. Wednesday the news got less frightening, and they both reacted within hours, in opposite directions. I can’t tell yet whether gold knows something about the dollar that the rest of us don’t, or whether it simply read a different paper.
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
P.S. – Phil’s Footnote I filed gold under “war” for years. This week it went up on the day the wires called less war, and on the night the Nasdaq futures fell it added another 1.7%. I may need a new drawer.
🗂 Desk Notes – Part 244 | 5 Nov 2026
Observations, not trades.
Session read (§8.4)
SESSION BRIDGE: prior session (Wed) full reaction [December ES settle +1.63% to 7,720.50; cash SPX +1.58%, DJI +3.03%, NDX +0.91%; VIX -20.26%; December WTI -8.29%]; live premarket ES -0.12% / NQ -0.91% at the 07:45 UTC capture (ES -0.06% / NQ -0.85% at the 08:10 UTC bar), VIX no global-hours print (prior close 16.61); threshold: soft.
- Equity leg: +1.63% on December ES sits in the 1.0-2.0% soft band. Catalyst is clear and is the Hot News story, so the carry-over fires.
- Volatility leg: VIX -20.26%, past the ±8% soft trigger.
- Commodity leg: December WTI -8.29%, past the ±4% soft trigger.
- §8.4.2 cash trigger: best-to-worst sector proxy spread 9.001 points (XLY +4.262, XLE -4.739), past 4.0. Board and decomposition mandatory and done.
- Premarket band: NQ -0.85% at the re-quote is outside the ~0.6% band on its own leg, 0.246 points beyond it. ES inside.
- Contract roll: none (18 Dec). Capture: four contracts, two reads (08:05 and 08:09-08:10 UTC), 07:45 bar byte-identical, 07:50 control identical, forming 08:05 bar changed between reads.
- Basis, same date (4 Nov): es_spx +31.88, nq_ndx +129.58.
Hot News board
- US midterms 2026, ROLLING, lead. New: CBS projects Democratic Senate control with at least 54 seats and 7 flips (NC, SC, TX, OH, KS, IA, ME). Mississippi uncalled, Colom +65 votes at ~96% counted, recount talk. Alaska uncalled, 48.2 to 47.9 at 77% counted, ranked choice. House: no call; Jeffries claims at least 255 (17:44 UTC 4 Nov) and a Speaker bid (21:00 UTC); Johnson not seeking minority leader. Trump to NYT: “absolutely willing to accept those results” (undated, upper bound 4 Nov). First cash session: Dow +3.03%, SOXX -3.14%, WTI -8.29%, gold +3.34%. Not yet known: final House total, Mississippi, Alaska, NY-17. Next: those calls; January swearing-in. Ledger correction: SC (03:03 UTC) and Minnesota (05:13 UTC) were called by CBS on 4 Nov; Mississippi was missing from the list.
- Middle East / Iran, ROLLING. New: Qatari draft could restart direct talks “within days” (Gulf News, upper bound 07:48 local 5 Nov). Trump to Fox: “something large”, possibly a “heavy hit” (logged 4 Nov, timezone unstated). Vance: “The reason we lost is the war.” Reuters 05:00 UTC: oil down a fourth day. IRGC tanker and drone claims unverified. Not yet known: whether either side accepts; any date. Next: talks date, Hormuz.
- AI and tech rout, ROLLING (re-ignited). New: SOXX -3.14%, SMH -2.75%, NVDA -3.17% on 4 Nov; data-centre names fell on the result (Reuters 21:25 UTC); NQ -0.85% at the re-quote; Kospi chip slump (Reuters). Narrative only: AI regulation and slower data-centre build-out (Citi via Reuters); Texas governor-elect’s data-centre pause pledge has no detail. Next: Nvidia results 17 Nov 21:20 UTC.
Mechanism read
| Series | 3 Nov | 4 Nov | Change |
|---|---|---|---|
| 2-year CMT | 4.61 | 4.58 | -3bp |
| 5-year | 4.74 | 4.69 | -5bp |
| 10-year | 4.95 | 4.90 | -5bp |
| 20-year | 5.35 | 5.30 | -5bp |
| 30-year | 5.32 | 5.28 | -4bp |
| 2s10s | 34bp | 32bp | flatter |
| VIX / VIX3M | 20.83 / 21.27 | 16.61 / 18.80 | ratio 0.979 to 0.884 |
| MOVE | 99.980 | 93.895 | -6.09% |
| DXY | 101.89 | 101.491 | -0.39% |
Curve: bull flattening, belly and long end led. Dollar weaker, yen +0.16%. Vol down across VIX, VIX3M, MOVE. Credit and duration proxies up (HYG +0.702%, LQD +0.752%, TLT +0.801%); no duration held, so no spread call.
The causal read. The session traded the election result, stamped by AP at 04:40:42 UTC, nearly ten hours (9h49m) before the cash open. SPX gap share 55.88%, intraday 44.12%; NDX gap 64.83%, intraday 35.17% (high 28,829.66 in the first hour, then faded). The result precedes the whole session, so as context it passes the clock; which part of it moved which sector is not stamped. Rates, dollar and vol all eased together, which reads as relief rather than fear. The divergence inside equities (Dow +3.031%, SOXX -3.138%, gap 6.168 points) is the spine pair.
Crude: no hourly path held for 4 Nov, so the majority test on WTI could not be run. Earliest midterm-oil headline 10:11:59 UTC (upper bound); WSJ “falls further after Vance tweet” 16:45 UTC. Refused as a named cause.
Gold: spot +3.342% on a day DXY fell 0.39% (gold 8.54 times the dollar’s move) and the 10-year fell 5bp; no real-yield series held. 4 Nov hourly path: 3,951.82 at 05:00 UTC, 4,061.11 at the close.
Cause board (§8.3)
Effects without causes: NQ overnight -0.91% to the capture; WTI -8.29% (refused, no path); gold +3.34%; SOXX -3.14% (narrative only). Causes without effects: Trump “heavy hit” remark on Iran (oil fell 8.29% anyway); EIA crude draw of 0.865m barrels, 15:30:41 UTC (crude fell anyway; consensus conflicts, Reuters poll +877k against Mace -1.7m).
The refusal, with its search, for the NQ overnight leg:
- Routes checked: TradingView news (get-news, get-news-story), Reuters and DJ via syndication, SEC EDGAR full-text (396 Item 2.02 filers on 4 Nov), Twelve Data extended-hours quotes.
- Stamps found: Qualcomm 21:00:00 UTC, AppLovin 21:05 UTC, Arm 21:03:42 UTC, Kospi sidecar 02:42 UTC, Reuters “Nikkei tumbles on tech rout” 07:07 UTC.
- Test run: NQ hourly closes against the 28,306.75 capture. 85.38% of the 260-point fall was in by the 01:00 UTC bar close. Every after-hours release precedes the whole fall but is stock-scoped. The Asian chip selling ran concurrently from 00:00 UTC and its stamps post-date the half-way point. Result: no index-scope cause; the overnight is written as the same split as the cash session.
Labelled speculation (AVE, Snippet, Macro only): the AI and data-centre regulation reading for the chip fall, stamped at the 21:25 UTC close wrap (a live blog carried it from 12:11 UTC). Not a retrieved cause.
Desk-notes-only: Fastly (-15.38%) and Sunrun (+12.63%) overnight moves on the Stocktwits board; attention-panel prices are stored, not published; no sourced cause.
Overnight Excitement (§8.5)
Fires. NQ overnight low 28,167.75 (05:45 UTC bar), -1.397% against settlement, past 1.0%, short of 1.5% (0.103 points). ES low -0.382%. Highs at the 23:00 UTC reopen on both. YM and RTY higher at the capture. Asia: Kospi sharply lower, Nikkei lower at the close after a higher start, Hang Seng higher, ASX higher (direction only, Reuters and others). Europe: STOXX 600 higher at the open; DAX and FTSE not separately established. BoJ minutes hawkish; Australia’s trade surplus larger than forecast. Norges Bank 09:00 UTC.
Forward catalyst slate
- Thu 5 Nov: Norges Bank 09:00 UTC; Bank of England 12:00 UTC (a hike is the wires’ expectation, single-route forecast, not published as a figure); US jobless claims and Q3 productivity 13:30 UTC; ConocoPhillips before the open; Airbnb and Cloudflare after the close.
- Fri 6 Nov: October payrolls 13:30 UTC (BLS schedule confirmed); UMich 15:00 UTC; Bowman on supervision 17:15 UTC.
- 9, 10, 12 Nov: refunding auctions, 3-year $58bn, 10-year $42bn, 30-year $25bn (total $125bn, unchanged).
- 17 Nov: Nvidia results 21:20 UTC.
- Not this week: FOMC (next 8-9 Dec; October minutes 18 Nov).
Divergence flags
- Gold up 3.342% while oil fell 8.294% on the same war-risk reading. Second consecutive edition with gold diverging from the risk read (4 Nov: gold kept its overnight gain while futures recovered). One more edition makes it a mandatory board candidate (ruling Y).
- Dow +3.031% against SOXX -3.138%: the spine.
- Brent and WTI disagree on direction this morning (Brent +0.19%, WTI -0.30% at the re-quote).
- SOXX and SMH 0.389 points apart on 4 Nov.
Carry-over note (§10.6)
Fires on the soft trigger with a clear catalyst. The noteworthy thing is not the rally but its shape: a 3% Dow day on a flat technology proxy, with oil, defence and chips all lower. The market heard “divided Washington” and repriced sectors, not the index level.
Regime and sensitivity read (§17.3)
Weathervane carried. NEUTRAL: the long end fell with the front end, 20-year still the curve’s high point (5.30 against 5.28 on the 30-year), a 39th consecutive session on the ledger’s count. Turn condition (2 sessions where a dated Fed communication moves DGS2 10bp+ while DGS30 moves less than half): 0 of 2, no Fed text. A change of Congress is a candidate regime event with no specified condition; flagged for Phil again. Sensitivity running LOOSE, stated openly.