The first cash session after the midterms took 8.3% off oil, put 3.3% on spot gold, and left December Nasdaq futures 0.9% lower this morning
 Ahoy there, Trader! ⚓️
It’s Phil…
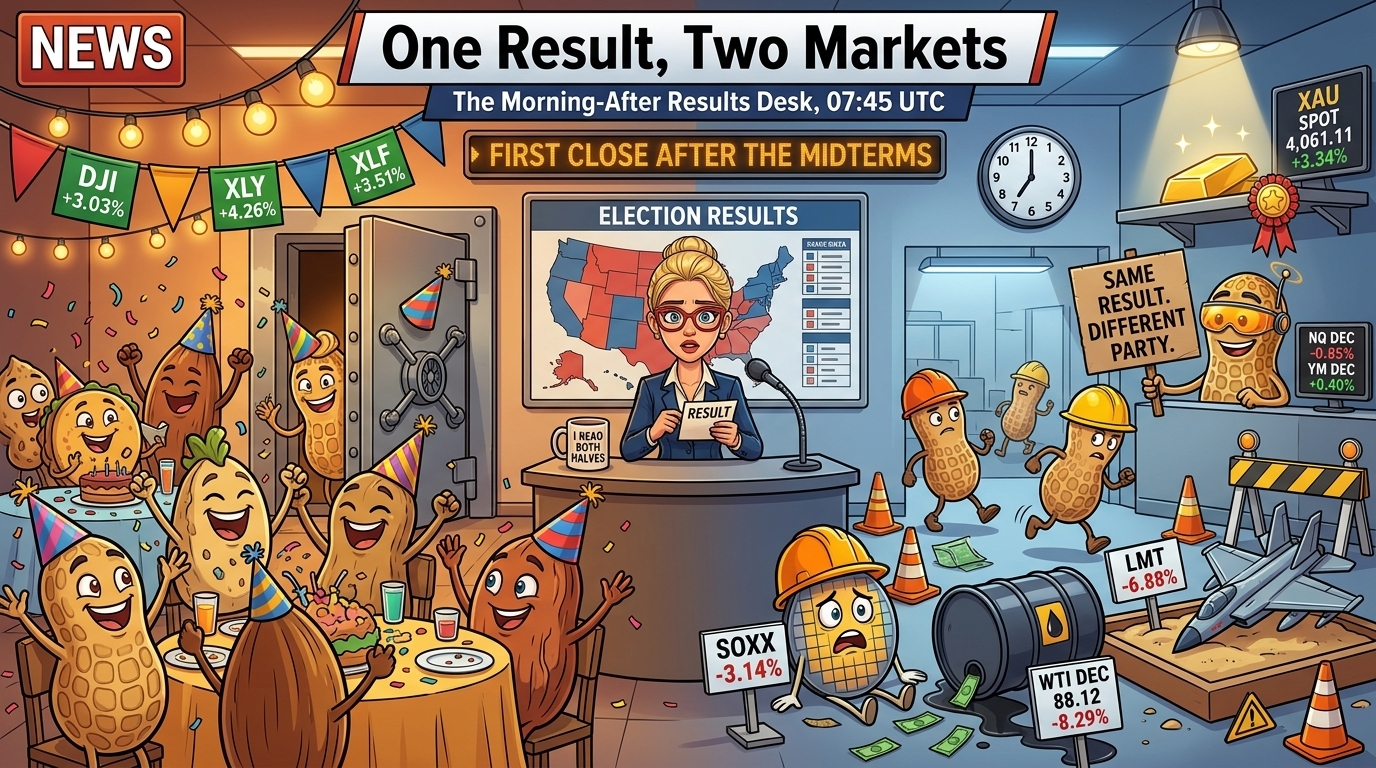
Democrats Took Congress. The Dow Rose 3.0% and the Chip Funds Fell 3.1%. The first cash session after the midterms took 8.3% off oil, put 3.3% on spot gold, and left December Nasdaq futures 0.9% lower this morning
Tuesday night the country voted. Wednesday the market had to pay a closing price for its opinion, and it turned out to hold two.
The result first. The Democrats won both chambers. CBS now projects Democratic control of the Senate with at least 54 seats and 7 flips. No House total has been called; Hakeem Jeffries says at least 255 seats and has announced a bid for Speaker. Mississippi and Alaska are still counting.
Then the closing prices. The Dow rose 3.03% to 53,356.12. The S&P 500 rose 1.58% to 7,688.62. The Nasdaq 100 rose 0.91% and finished last of the five main indices. NYSE advancers beat decliners 2,014 to 655, about three to one, and 70.16% of the exchange’s volume went into rising stocks. That is not a narrow rally. That is the floor turning up.
And the other market. The semiconductor fund SOXX fell 3.14%. Nvidia fell 3.17%. The technology proxy finished flat although its chip makers fell. Memory and data-centre names were among the losers, on Reuters’ close wrap. Energy fell 4.74%. Lockheed Martin fell 6.88%, Northrop Grumman 4.53%, Exxon Mobil 4.62%. Consumer discretionary rose 4.26% and financials 3.51%. JPMorgan rose 4.18%. The best sector proxy and the worst finished 9.00 points apart.
So the one number that mattered today is a pair: the Dow up 3.03% and SOXX down 3.14%, 6.17 points apart on the same result.
The session traded the result, and the result was known nearly ten hours before the bell: AP’s Senate story went out at 04:40 UTC on Wednesday and the cash market opened at 14:30 UTC. The opening gap carried 55.88% of the S&P 500’s move. Which part of the result moved which sector is not stamped, so this book names no single call or statement as the cause of any leg. The desks’ own readings, labelled as readings: a clear result lifts the fog; a divided Congress spends less and legislates less; and a Democratic House is less keen on a wider war with Iran.
That last reading is where oil comes in. December WTI fell 8.29% to 88.12. January Brent fell 8.67% to 94.62. The fall did not start with the vote: on Monday, before anyone voted, December WTI had lost 7.36% on reports of Qatari-led talks, and Reuters counts Thursday as a fourth straight day lower. By 16:45 UTC on Wednesday JD Vance had posted that “the reason we lost is the war”, and the Wall Street Journal’s headline on it said oil fell “further”, which places the post after at least part of the fall by its own wording. This book holds no hourly crude path for Wednesday, so it names nothing as the cause of the 8.29%. The EIA reported a crude draw that afternoon. Oil fell anyway. On Wednesday President Trump spoke of “something large” on Iran, possibly a “heavy hit”, and by 15:23 UTC, on Seeking Alpha’s report, was playing down the prospect of strikes. Oil fell through both.
Then there is gold. Spot gold rose 3.34% to 4,061.11 on a day the fear gauges fell: the VIX fell 20.26% to 16.61, the 10-year yield fell 5bp to 4.90% and the dollar index fell 0.39%. A falling dollar and falling yields lift gold in the textbook. They do not obviously account for a move 8.54 times as large as the dollar’s. The timing is the one clue: 57% of gold’s gain on the day came in the two hours from 05:00 UTC, straight after AP’s Senate story. This book holds no trigger for the size of it.
On Wednesday this book set AMD a test: hold above its 483.90 close. It traded as low as 476.50 and closed at 488.78: a hit, scraped. The gold test, above 3,951.82 at Friday’s close, is scored after payrolls and not before.
Overnight the split carried on: at the 08:10 UTC bar December Nasdaq 100 futures were 0.85% lower and December Dow futures 0.40% higher.
The Bank of England decides at 12:00 UTC. Jobless claims print at 13:30 UTC. Payrolls arrive on Friday, which gives the chips a day and a half to decide whether Wednesday was a verdict or a mood.
The One That Mattered
The Dow rose 3.03% and the chip fund fell 3.14%, and they were reading the same result. Oil read it as less war and lost 8.29%. Gold read the same day, with the VIX down 20.26% and the dollar softer, and added 3.34%. Two of the market’s favourite war hedges reached opposite verdicts in one session. Either one of them is wrong about the war, or gold was not pricing the war. If the wires read the election as less war and oil fell 8.3%, why did spot gold add 3.3% the same day? We have not settled it here. We took it apart in today’s Macro Edge.
Hot News: The Midterms, Day Two
Senate Control Is Called. The House Is Not. Mississippi Is Still Counting. What is new since Wednesday morning, and what is still not known
CBS projects Democratic Senate control with at least 54 seats and 7 flips, including South Carolina and Maine. Mississippi is uncalled: the Democrat led by 65 votes with about 96% counted, and a recount is being discussed. Alaska is uncalled, 48.2% to 47.9% with 77% counted, under ranked choice. No House total is called. Jeffries claims at least 255 seats and is running for Speaker; Mike Johnson has told staff he will not seek minority leader. Trump told the New York Times he is “absolutely willing to accept those results”. A correction to Wednesday’s list of uncalled races: CBS had called South Carolina and Minnesota by 05:13 UTC, and Mississippi, left off the list, is the one still counting.
On Iran, a Qatari draft could restart direct US-Iran talks within days, according to Gulf News. Neither side has said it accepts it. On chips, the Reuters close wrap reported that data-centre stocks tumbled on the result. Nvidia reports on 17 November, which is when that argument gets a number.
Our Top Trader Uses This 9:50 AM Secret to Target $500 Per Day Regardless Of Which Direction The Market Moves https://antivestor.com/ppp-webinar
Overnight Excitement
December Nasdaq Futures Fell 1.4% Overnight. Dow Futures Went the Other Way. The section fires on the futures; the overnight session repeated Wednesday’s split
December Nasdaq 100 futures fell 1.40% below Wednesday’s settlement at their overnight low, 28,167.75 in the 05:45 UTC bar. That is past the 1.0% mark that fires this section and short of the 1.5% that would lead it. At the capture they were 0.91% lower, and at the 08:10 UTC bar 0.85% lower. December Dow futures were 0.42% higher at the capture, December Russell futures 0.22% higher, December S&P futures 0.12% lower.
The night, in UTC. Qualcomm released its results at 21:00 and AppLovin at 21:05, both before the futures reopened at 23:00. The reopen was the overnight high. By the close of the 01:00 UTC bar, 85.38% of the fall to the capture was already in. Asian chip selling ran alongside: the Kospi fell sharply as chipmakers slumped and the Nikkei closed lower on a tech rout, on Reuters’ reports, whilst the Hang Seng rose. Qualcomm’s fall is a cause for Qualcomm. It is not stamped as the cause of an index, so this book names none for the 0.91%; it says the futures traded the same split as the cash session.
Elsewhere, December WTI was 0.30% lower at 87.86 at the 08:15 UTC bar while January Brent was 0.19% higher at the 08:05 UTC bar, so the direction of oil this morning depends on which oil. Spot gold was 1.68% higher at 4,129.16. European shares opened higher. Norges Bank decides at 09:00 UTC.
Stock Market Edge
The Floor Rallied, the Chips Sat Out, and Defence Went Home Early December Dow futures 0.40% higher, December Nasdaq 100 futures 0.85% lower at the 08:10 UTC bar
Premarket snapshot:
At the 07:45 to 07:50 UTC capture, December S&P 500 futures stood at 7,711, 0.12% below Wednesday’s settlement of 7,720.50. December Nasdaq 100 futures were 0.91% lower at 28,306.75 against a 28,566.75 settlement. December Dow futures were 0.42% higher at 53,730 and December Russell 2000 futures 0.22% higher at 2,872.10. At the 08:10 UTC bar the four December contracts stood at 7,716, 28,325, 53,717 and 2,871.40. The VIX had no global-hours print by 08:20 UTC; it closed Wednesday at 16.61. The Nasdaq contract is outside the normal premarket band on its own. The Dow contract is enjoying itself.
Sector rotation:
Wednesday’s cash session put consumer discretionary up 4.26%, financials up 3.51% and communication services up 3.47%. Staples rose 3.36%, real estate 3.32%, health care 3.06% and materials 2.49%. Energy fell 4.74% and industrials 1.09%, with defence inside that: Lockheed Martin down 6.88%, Northrop Grumman 4.53%, RTX 2.64%. Technology finished flat while SOXX fell 3.14% and SMH 2.75%, 0.39 points apart, two chip funds agreeing on the direction and differing on the size. First Solar rose 4.63% and Enphase 3.71%. Tesla fell 3.34%. JPMorgan rose 4.18% and Goldman Sachs 3.56%. Banks, shops and solar panels up; missiles, oil wells and chips down. Nobody would have voted for that list. Everybody did.
Earnings or guidance:
After Wednesday’s close, AppLovin reported its third quarter at 21:05 UTC and rose 22.13% after hours to 331.88. Qualcomm reported at 21:00 UTC and fell 7.04% to 161. Zillow fell 15.93%, Snap 11.66% and MercadoLibre 7.58%. Coherent, reporting its first quarter of fiscal 2027, rose 5.16%. Arm fell 1.98% and McKesson 1.54%. Qualcomm’s and AppLovin’s stamped results are causes for their own shares and nothing larger; the rest are moves after results, with no cause traced here. AMD closed Wednesday at 488.78. Today ConocoPhillips reports before the open, with an oil price 8.29% lighter than on Tuesday, and Airbnb after the close.
Cross-asset nuance:
The curve fell too. The 2-year yield fell 3bp to 4.58%, the 5-year 5bp to 4.69%, the 10-year 5bp to 4.90% and the 30-year 4bp to 5.28%. The 2s10s spread narrowed to 32bp. The VIX fell 20.26% to 16.61 and VIX3M to 18.80, a ratio of 0.88, comfortably in contango. Bond volatility, the MOVE index, fell 6.09%. High yield rose 0.70% and TLT 0.80%. The dollar index fell 0.39% to 101.49 and the yen firmed 0.16%. Spot gold rose 3.34%, December silver settled at 52.28 and copper barely moved. Treasury left its refunding unchanged at $125bn: $58bn of 3-year notes, $42bn of 10-year and $25bn of 30-year bonds, auctioned from 9 November. The VIX, VIX3M and MOVE all fell. Gold went up anyway.
Crypto Market Edge
Bitcoin Added 3.97% and Was Not Invited Onto Its Own Board Ether added 6.62%; the flow tables stayed shut
Price snapshot:
Bitcoin stood at 80,400.29 on the Thursday 00:00 UTC mark, up 3.97% from 77,328.21, and at 80,488.90 at the 08:15 UTC bar. Ether stood at 2,421.48, up 6.62% from 2,271.10, and at 2,413.26 at the 07:45 UTC bar. Coinbase and the composite feed agreed within 0.04%.
Flows and positioning:
Farside’s bitcoin and ether pages returned errors on two attempts each, for a third session. This book has no spot ETF flow for 3 or 4 November and does not borrow one.
Leadership and rotation:
Ether beat bitcoin by more than 2 points. This book holds no cause for either move. On Stocktwits’ crypto-only board at 07:30 UTC, depth 25, SOL.X ranked first, TRUMP.X second and MELANIA.X seventh. BTC.X did not appear at all. A day after the President’s party lost Congress, his memecoin ranked second on the crypto board, behind Solana. Attention is not a price, and a memecoin is not a policy.
Catalysts and roadmap:
The Bank of England at 12:00 UTC, jobless claims at 13:30 UTC, payrolls Friday at 13:30 UTC.
TL;DR
- The Dow rose 3.03% and the S&P 500 1.58% in the first close after the midterms, while the chip fund SOXX fell 3.14%: one result, two markets.
- Consumer discretionary rose 4.26% and financials 3.51% while energy fell 4.74% and Lockheed Martin 6.88%; the sector proxies finished 9.00 points apart.
- December WTI lost 8.29% to 88.12 as the wires read the result as less war; this book holds no hourly crude path to name a cause.
- Spot gold rose 3.34% to 4,061.11 while the VIX fell 20.26%; 57% of the gain came in the two hours after the Senate call.
- December Nasdaq 100 futures were 0.85% lower and December Dow futures 0.40% higher at 08:10 UTC; the Bank of England decides at 12:00 UTC, payrolls Friday.
Fun Fact
The Dow Started With 12 Stocks Its first published value was 40.94
Charles Dow first published his industrial average on 26 May 1896, with 12 companies in it, at 40.94. On Wednesday it rose 1,569.40 points in one session, which would have been a rounding error on a very large number of 1896s.
Meme of the Day:
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
p.s. There are 3 ways I can help you…
- Option 1: Collect Morning Income
A complete guide to the Premium Popper system.
Written to be clear, concise, and immediately actionable.
>> Learn More Here
- Option 2: Collect Weekly Income
A complete guide to the Tag ‘n Turn system.
>> Learn More Here
- Option 3: Join the Fast Forward Mentorship
>> Join the Fast Forward Mentorship – trade live, twice a week, with me and the crew.
PLUS Monthly on-demand 1-2-1’s
No fluff. Just profits, Tag ‘n Turn Pulse bars, Poppers, and Patterns that actually work.