Friday took back 5 of Thursday’s 12bp; Tuesday’s inflation print arrives with December already leaning
⚓ Weathervane. The wind is coming from the long end. The policy rate has been frozen for most of the year whilst the term premium does the tightening, and the price of long money is set by deficits, issuance supply and a synchronised global duration bid rather than by the committee. Higher-for-longer stopped being a Fed decision and became a bond-market fact. The cruise ship is holding this heading.
 Ahoy there, Trader! ⚓️
It’s Phil…
The 2-year rose 5bp and the dollar 0.7% on payrolls day: what is left for Tuesday’s inflation print to decide?
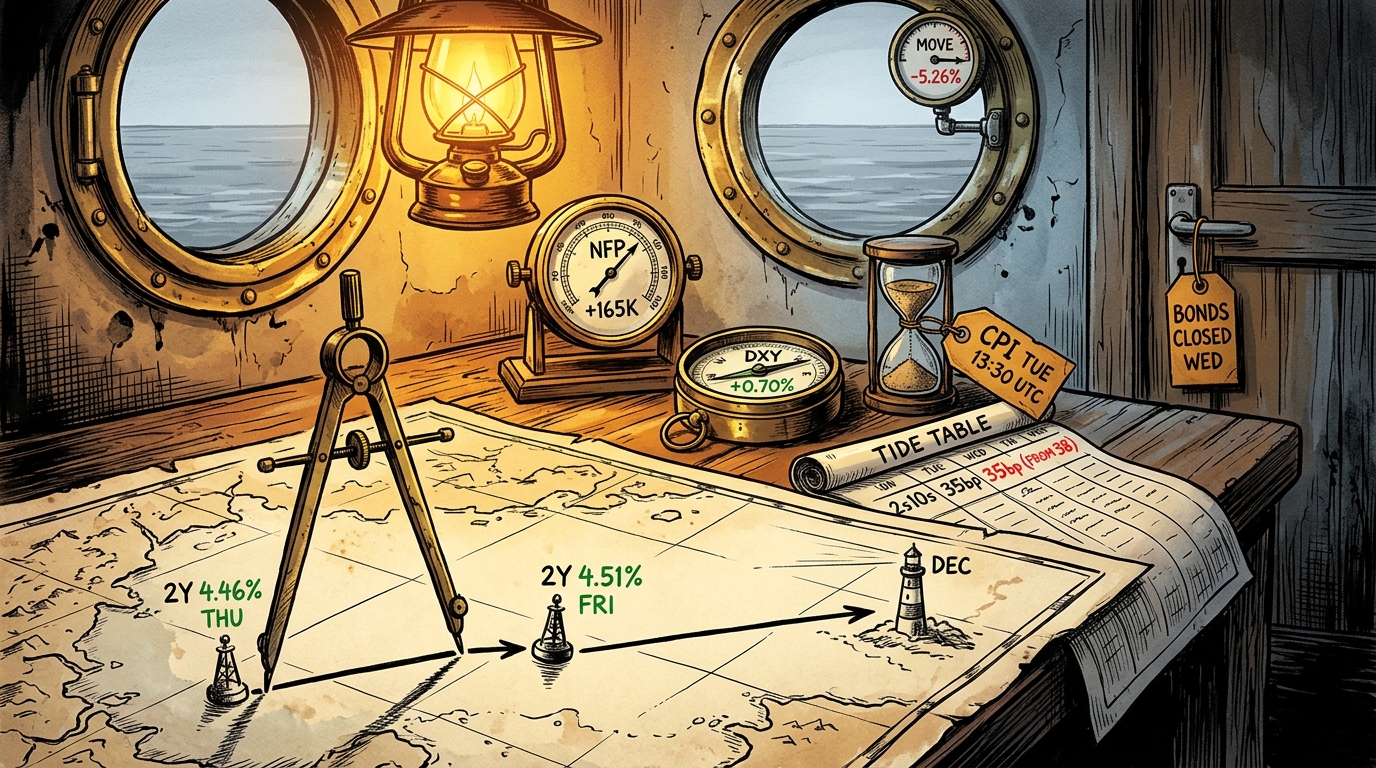
Start with Thursday, because Friday only makes sense against it. On Thursday the chips fell 11.21% and the 2-year yield fell 12bp to 4.46%. The surface read was that money ran to the short end because growth looked shakier. On Friday at 13:30 UTC the jobs report said growth was fine: 165,000 jobs, unemployment down to 4.1%, hourly earnings up 0.4% on the month, and 84,000 more jobs found in August and September than first reported. The 2-year rose 5bp to 4.51%. So Friday’s session took back 5 of Thursday’s 12 basis points.
The rest of the curve moved less. The 10-year rose 2bp to 4.86% and the 30-year 1bp to 5.26%, so 2s10s narrowed to 35bp from 38bp. The dollar index rose 0.70%. Bond volatility fell 5.26%. Equity volatility fell 9.01% to 25.64 but stayed above its three-month cousin, a ratio of 1.04.
The textbook says a strong jobs report lifts the front end more than the back, firms the dollar and flattens the curve. Friday did all three.
The gap is elsewhere. Bond volatility fell on a day the front end repriced, and the futures relay this book reads, which it never quotes as a figure, now leans towards a December hike. The rates market moved and calmed down at the same time.
Which brings us back to Tuesday. The settling figure is core CPI’s monthly change at 13:30 UTC, and the curve’s reply in the hour after it. A 2-year that rises again with 2s10s narrower confirms Friday. A 2-year that gives back its 5bp says Friday was one data point leaning on another. Wednesday’s bond market is shut for Veterans Day, so whatever Tuesday says will sit there for a day with the cash bond market shut.
The cruise ship has not moved. Friday carried no Fed communication, so the Weathervane rides.
Phil’s Musing
I think Friday did more work than Tuesday will. A 165,000 print with upward revisions is the sort of report that changes how the next one is read, and the 2-year’s 5bp looked like a market quietly giving up on the idea that Thursday was a growth scare. I would want to see the curve’s reaction to CPI before calling December, but the burden has shifted onto the soft-print case.
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
P.S. – Phil’s Footnote I went into the weekend thinking Thursday’s 12bp was the bond market’s verdict on the chips. One session later, nearly half of it is gone, and I am less sure the bond market and the chip market were ever talking to each other.
🗂 Desk Notes – Part 246 | 9 Nov 2026
Observations, not trades.
Session read (§8.4)
SESSION BRIDGE: prior session (Fri 6 Nov) full reaction ES Dec settle +0.257%, SPX +0.315%, NDX +1.353%, DJI -0.461%, VIX -9.014% to 25.64; live premarket ES -0.034% / NQ -0.809% at the 07:45-07:50Z capture (ES +0.064% / NQ -0.569% at the 08:05Z bar), VIX no global-hours print; threshold: soft.
- Prior-session equity leg: under 1.0%, silent.
- Volatility leg: VIX -9.014%, beyond the ±8% line, so the soft trigger fires on vol alone.
- Premarket leg: NQ -0.809% at capture was outside the 0.6% band; at the 08:05Z re-quote it was -0.569%, back inside by 0.031 points. The soft call stands on the vol leg.
- Capture: 07:45Z bar read twice (about 08:05:30Z and 08:11:50Z), o/h/l/c/v byte-identical on all four contracts; the 08:05Z control bar changed between reads on all four. Fourteenth consecutive on-time four-contract two-read capture.
- Basis (Friday): es_spx_basis +25.14, nq_ndx_basis +95.26.
- Friday’s SPX opening gap was 103.42% of the close-to-close move; the index faded from a 7,444.2 first-hour high. NDX gap 115.34%.
- Contract roll: none (18 Dec). Veterans Day Wed 11 Nov: SIFMA recommends a full bond-market close; equities open.
Hot News board
| Topic | Status | Today’s update | Not yet known | Next |
|---|---|---|---|---|
| Nvidia board inquiry | OPEN, LEAD | Independent directors with outside counsel to review reports Huang was targeted by a Chinese intelligence effort; Huang admits affair, apologises; board retains confidence (CBS 21:58Z 8 Nov, AP 04:14Z 9 Nov, Yahoo 02:09Z) | Scope, timetable, substantiation, congressional action, effect on the quarter | Results 17 Nov (company release); overnight NVDA move unsettled between sources, not printed |
| AI and tech rout | ROLLING | Friday bounce: SMH +3.625%, SOXX +3.510%, AMD +11.039%, INTC +7.713%, NVDA +2.775% to 186.64; week SPX -2.681%, NDX -4.914% | Whether the bounce holds into Nvidia’s results | CoreWeave Tue after close; Nvidia 17 Nov |
| Middle East / Iran | ROLLING | Qeshm strike (Fri), Task Force Iron Gate (Sat), M/V Huda disabled (Sat); Trump: war “highly unlikely” if Iran signs; Rubio: no breakthrough | Any acceptance of the Qatari proposals; talks date; retaliation; Hormuz status | Any talks date; Brent |
| US midterms 2026 | ROLLING | AP Sat: Senate 54 D / 44 R; House 254 D / 162 R, 19 uncalled; Stephen Miller named chief of staff | Mississippi and Alaska Senate seats; final House total | Mississippi ballot deadline 10 Nov; Alaska RCV about 18 Nov; funding deadline 11 Dec |
The mechanism read
What moved. Friday: payrolls +165k at 13:30Z, unemployment 4.1% from 4.2%, AHE +0.4% m/m, revisions +84k net. CMT: 2Y 4.51 (+5bp), 10Y 4.86 (+2), 20Y 5.29 (+2), 30Y 5.26 (+1). 2s10s 35bp (from 38), 2s30s 75bp (from 79), 20s30s -3bp. 20Y strict curve maximum, 41st consecutive session. DXY 102.279 (+0.703%). USDJPY 158.469 (+0.506%). VIX 25.64 (-9.014%), VIX3M 24.60, ratio 1.042, inverted for a second session. MOVE 92.782 (-5.259%). HYG -0.065%, LQD -0.124%, TLT -0.012%.
What it implies. A front-end-led bear flattening on a jobs beat, with the dollar confirming. Bond vol fell while equity vol stayed inverted, so the fear sat in equities again. The equity bounce was all at the open: Friday’s SPX gap carried 103.42% of the day’s move.
The one artery, crowned in the letter: the overnight futures split, NQ -0.809% against YM +0.352% at capture (gap 1.161 points), in the context of the Nvidia story.
The refusal, with its search.
- Routes checked: CBS, AP via news4jax, Yahoo/Stocktwits syndication, Al Jazeera, Gulf News for the story clock; TradingView 5m bars on ESZ2026, NQZ2026, YMZ2026, RTYZ2026 for the path.
- Stamps found: story 21:58Z Sun (CBS), before the 23:00Z reopen. NQ path: +0.863% at the 02:30Z bar (high), -1.233% at the 07:45Z bar (low), -0.569% at 08:05Z.
- Test run: majority test against the capture and re-quote reads. The story precedes every read, but the contract rose 0.863% after it before falling. The stamp cannot carry the 02:30Z-07:45Z fade on timing alone, and a stock-scope story is never written as the cause of an index move (no index weights held). majority_unexplained: true.
Candidate board (§8.3)
Effects without causes. NQ fade 02:30Z to 07:45Z: no stamped headline in that window (refusal, published). Bitcoin -2.208% (composite feed; Coinbase -2.220%) from Fri 21:00Z, mostly in the 21:00Z Sunday hour: wires call it forced long selling (liquidation), bitcoin scope only, coincidence published.
Causes without effects. Iran: Qeshm strike, Iron Gate, M/V Huda; January Brent -1.658% at capture (coincidence, published). Payrolls +165k: 2Y +5bp on the day, no intraday CMT path held (coincidence, published).
Filed here only. China October PPI +5.7% y/y and CPI +0.7% y/y (tier 2, single mirror source): no US transmission route tested; Asia mostly higher on wire reports.
Narrative the market gave for Friday (labelled narrative, not fact): dip-buying after Thursday’s chip fall; a reassessment of data-centre restrictions; payrolls lifting December hike odds.
Overnight Excitement
Fires on the range: NQ Dec overnight high +0.863% (02:30Z bar), low -1.233% (07:45Z bar), past the 1.0% line but short of 1.5%, so it does not lead. ES +0.682% / -0.517%, YM +0.821% / -0.348%, RTY +0.895% / -0.529%; the ES, YM and RTY lows were in the 23:00Z reopen bar. Asia on wires: Taiex and Nikkei strongly higher, Hang Seng and Shanghai slightly higher, Kospi lower. No US company reported after Friday’s close. Brent Jan 96.86 at 08:00Z (-1.485%), WTI Dec 90.06 at 08:05Z (-0.848%), spot gold 4,092.47 (+0.671%).
Forward catalyst slate
- Mon 9 Nov: Bowman 13:40Z (discussion, community banking); NY Fed consumer expectations 16:00Z; 3-year auction 18:00Z (calendar route only; fiscaldata returned nothing, so no size).
- Tue 10 Nov: Waller 09:00Z London (economic outlook); CPI 13:30Z; 10-year auction 18:00Z; CoreWeave after close; Mississippi ballot deadline.
- Wed 11 Nov: Veterans Day, bond market closed.
- Thu 12 Nov: jobless claims 13:30Z; 30-year auction 18:00Z.
- Fri 13 Nov: PPI 13:30Z.
- Not this week: retail sales. Nvidia 17 Nov. FOMC 8-9 Dec; the futures relay (tier 3) leans to a December hike.
Divergence flags
- NQ and YM split in opposite directions on consecutive sessions (Friday cash, Monday futures).
- VIX/VIX3M inverted for a second session (1.042) while MOVE fell 5.259%.
- Staples the worst sector fund (-1.282%) on a session the chips bounced.
- NYSE advancers 1,439 against decliners 1,249 while up volume was 47.467% of the two-way total.
Carry-over note
Soft trigger fires on the vol leg. The futures traded after the Nvidia headlines; the contract rose first after the story broke, and the fade is the unexplained leg.
Regime and sensitivity (§17.3)
Weathervane carried. No Fed communication on Friday, so the turn condition does not advance (thirty-sixth non-advance). VIX curve inversion, second session: candidate signal with no pre-stated condition, flagged for Phil. Sensitivity running LOOSE, fifty-seventh edition, stated openly.