December futures at the 07:45 UTC capture, after a week in which the S&P 500 lost 2.7%; CPI prints Tuesday
 Ahoy there, Trader! ⚓️
It’s Phil…
Nvidia, the AI trade’s bellwether, spent Sunday afternoon in New York announcing that its board would be looking into its chief executive.
Nvidia’s independent directors, with outside counsel, will review reports that Jensen Huang was targeted by a Chinese intelligence effort. Huang has admitted an affair and apologised to staff. The board says it has no reason to believe company secrets or US national security were compromised and that it retains confidence in him. Nvidia reports its quarter on 17 November.
Then the futures reopened. At the 07:45 UTC capture, December Nasdaq 100 futures stood 0.81% below Friday’s settlement. December Dow futures stood 0.35% above theirs. December Russell 2000 futures were up 0.55%. December S&P 500 futures, caught in the middle, were down 0.03%.
So the one number that mattered this morning is a pair: Nasdaq contract -0.81%, Dow contract +0.35%, a gap of 1.16 percentage points between two indices that share a country, a central bank and, as of Friday, a jobs report.
It is the mirror of Friday’s cash session, when the Nasdaq 100 rose 1.35% and the Dow fell 0.46%. The market has now split these two indices in opposite directions on consecutive sessions, which is one way to stay busy.
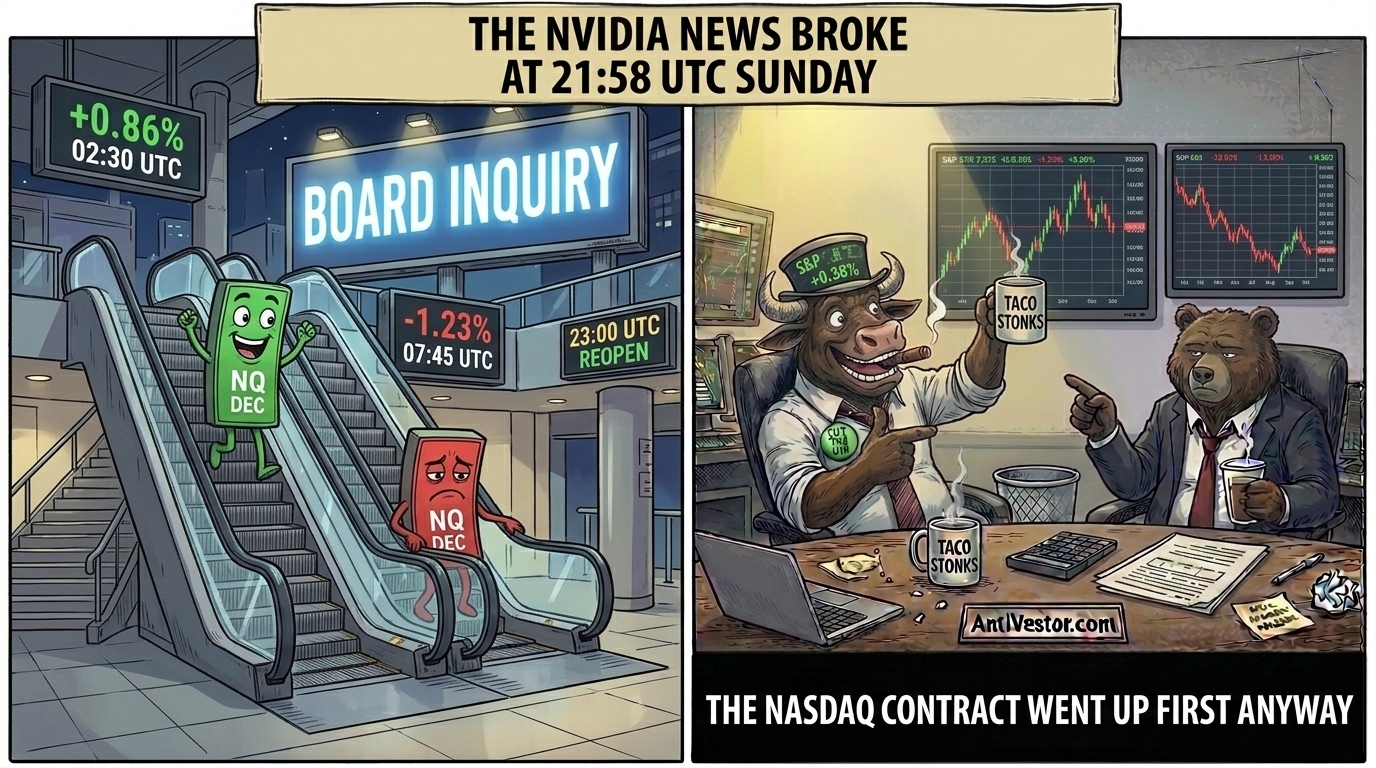
Now the clock, because it is the obvious story and it does not quite fit. CBS had the inquiry at 21:58 UTC on Sunday, an hour before the contract reopened at 23:00 UTC. The Nasdaq contract then rose, and stood 0.86% above settlement by 02:30 UTC, with CBS and Yahoo already carrying it; the wider wire pickup came after the high. The fall came between then and the capture, and that leg carries no stamp in this book. We checked CBS, AP, Yahoo and Al Jazeera for the story’s timeline and the five-minute bars on all four December contracts for the moves, then ran the stamp against every locked read. The story precedes the move. So does the rise that came first. The futures traded through the Nvidia story; no stamp ties it to the fall, so no cause is named. The inquiry is named as a cause for Nvidia’s shares alone.
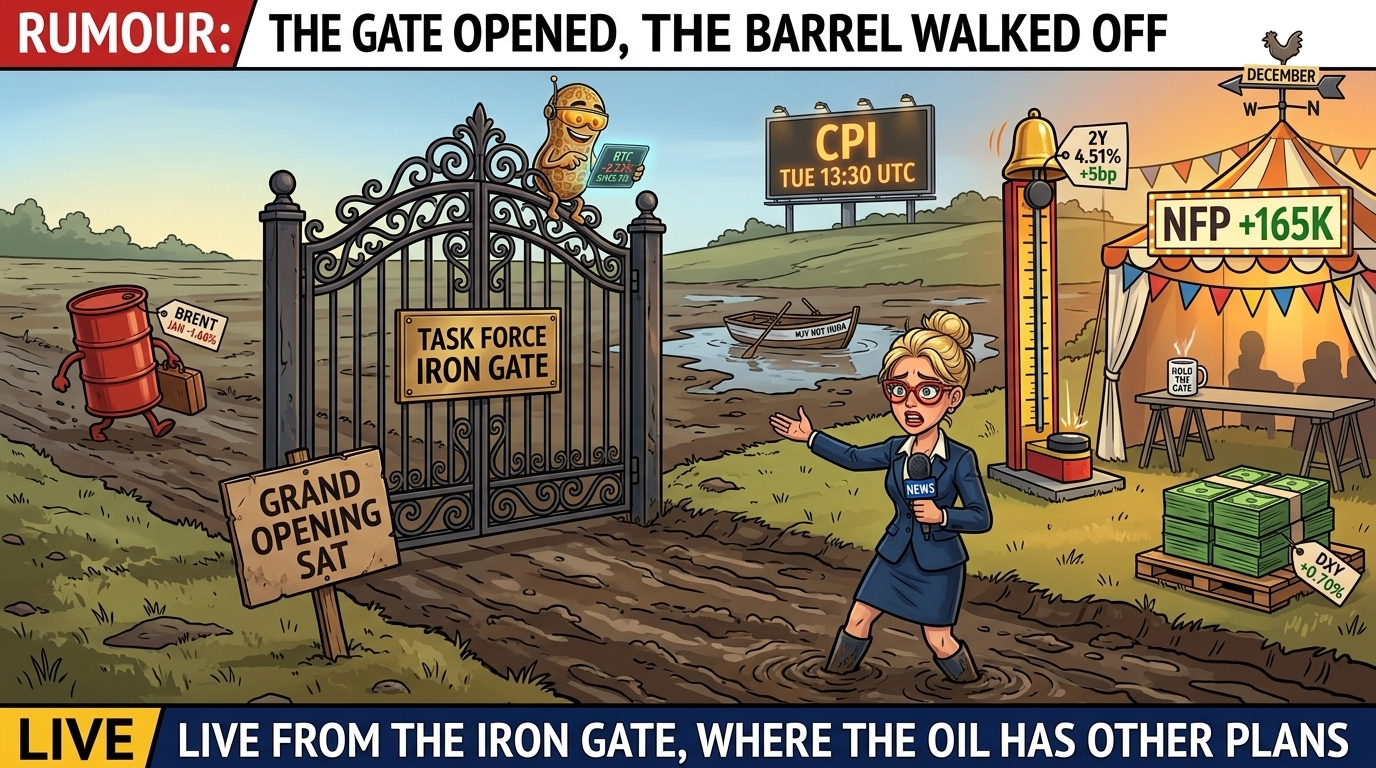
One weekend story did not move what it was supposed to. The US struck Iranian air defences on Qeshm Island on Friday, announced a task force called Iron Gate on Saturday to watch Iran’s land borders and disabled a blockade-running ship. January Brent was 1.66% lower at the capture. No stamped trigger for Brent’s fall is held; President Trump’s Sunday remark that renewed war was “highly unlikely” if Iran signs a deal is untested as one.
Friday’s two tests from Thursday’s edition are in. December WTI, below 96.09 through Friday: it settled at 90.83. Spot gold, above 3,951.82 at Friday’s close: it closed at 4,065.20. Two hits. The book’s record on named causes is 17 hits, 7 misses and 2 splits. Macro Edge’s own test, gold closing below 4,061.11, did not fire: gold cleared it by four dollars.
CPI prints on Tuesday at 13:30 UTC, the bond market shuts on Wednesday, and Nvidia’s results arrive on 17 November with a board inquiry stapled to the front.
The One That Mattered
The Nasdaq contract fell 0.81% overnight after a chief executive’s weekend, with no stamp on the fall, and the Dow contract rose 0.35%. That is the story the screens are showing. The rates story printed on Friday: 165,000 jobs, a 2-year yield up 5bp and a dollar up 0.7%, all before anyone had heard of an inquiry. The 2-year rose 5bp and the dollar 0.7% on payrolls day: what is left for Tuesday’s inflation print to decide? We have not settled it here. We took it apart in today’s Macro Edge.
Hot News: Nvidia’s Inquiry, Iran’s Iron Gate and the Midterm Count
Nvidia Opens an Inquiry, Iran Gets a Task Force, the House Count Reaches 254 What is new since Friday morning, and what is still not known
Nvidia is today’s new story. The board’s review follows New York Times reporting last month that US intelligence believes a former executive at a Singapore data-centre buyer of Nvidia chips worked for China’s Ministry of State Security and was close to Huang. The board will review “all available information”. What is not known: the review’s scope and timetable, whether the reporting is substantiated, whether Congress acts, and whether any of it touches the quarter due on 17 November. Analysts quoted over the weekend called it a governance risk. The shares traded lower in overnight venues on syndicated reports; this book holds no settled figure for the move, so it prints none.
The AI and tech rout paused on Friday. SMH rose 3.62% after Thursday’s 11.21% fall, AMD rose 11.04% and Nvidia 2.78% to 186.64. The S&P 500 still lost 2.68% on the week and the Nasdaq 100 4.91%.
On Iran, the Qeshm strike, Task Force Iron Gate and the disabled ship M/V Huda all landed between Friday and Saturday. President Trump said renewed war is “highly unlikely” if Tehran signs a strong deal; Secretary Rubio said there is no breakthrough. Iran has accepted no proposal and no talks date is set. Brent fell anyway.
On the midterms, AP counts 54 Democratic Senate seats to 44 and 254 Democratic House seats to 162, with 19 uncalled. Mississippi’s ballot deadline is Tuesday and Alaska’s count runs to about 18 November. Stephen Miller has been named White House chief of staff.
Our Top Trader Uses This 9:50 AM Secret to Target $500 Per Day Regardless Of Which Direction The Market Moves https://antivestor.com/ppp-webinar
Overnight Excitement
The Nasdaq Contract Went Up First and Down Second The section fires on the overnight range: 1.23% below Friday’s settlement at the low, 0.86% above it at the high
December Nasdaq 100 futures traded an overnight range from 0.86% above Friday’s 27,085.25 settlement, at the 02:30 UTC bar, to 1.23% below it, at the 07:45 UTC capture bar itself. The capture caught the low. By the 08:05 UTC bar the contract was 0.57% lower at 26,931.25.
The other three contracts did their worst at the 23:00 UTC reopen and then improved. December Dow futures were 0.42% higher at 08:05 UTC, December Russell futures 0.78% higher and December S&P 500 futures 0.06% higher. All four contracts rallied into the Asian session and faded from their highs; the Nasdaq contract faded furthest, from 0.86% above settlement to 1.23% below.
Asia, on wire reports, was mostly higher: Taiwan and Japan strongly, Hong Kong and Shanghai slightly, with Korea lower. No US company reported after Friday’s close.
January Brent was 96.86 at the 08:00 UTC bar and December WTI 90.06 at 08:05 UTC. Spot gold was 4,092.47 at the 08:05 UTC bar, up 0.67% on Friday’s close.
Stock Market Edge
The Chips Bounced, the Staples Fell and the Week Still Lost 2.7% Friday’s cash session, read from Monday’s futures
Premarket snapshot:
At the 07:45 to 07:50 UTC capture, December S&P 500 futures stood at 7,399.5 against Friday’s 7,402 settlement. December Nasdaq 100 futures were at 26,866.25, down 0.81%. December Dow futures were at 51,566, up 0.35%, and December Russell 2000 futures at 2,775.7, up 0.55%. At the 08:05 UTC bar the four read 7,406.75, 26,931.25, 51,603 and 2,782. The VIX has no global-hours print yet; it closed Friday at 25.64.
Sector rotation:
Technology led Friday, XLK up 1.45%, with communication services up 0.43%. Staples were worst at -1.28%, then materials -0.73% and real estate -0.68%: a 2.74-point spread. On the NYSE 1,439 issues rose and 1,249 fell, but up volume was only 47.47% of the two-way total. On Nasdaq 2,915 rose and 1,971 fell.
Earnings or guidance:
Inside the chips, AMD rose 11.04%, Intel 7.71%, Taiwan Semiconductor 6.33%, Micron 5.12%, Nvidia 2.78% and Broadcom 0.74%. No company reported after Friday’s close. Constellation Energy reports before today’s open and CoreWeave after Tuesday’s close. Nvidia’s 17 November date is confirmed by the company.
Cross-asset nuance:
Payrolls rose 165,000, unemployment fell to 4.1% and hourly earnings rose 0.4% on the month. The 2-year yield rose 5bp to 4.51% and the 10-year 2bp to 4.86%; 2s10s narrowed to 35bp from 38bp. The 20-year held the top of the curve at 5.29%. The dollar index rose 0.70%. The VIX fell 9.01% to 25.64, still above VIX3M at 24.60, a ratio of 1.04, so the fear curve stayed upside down for a second session. Bond volatility fell 5.26%. High yield slipped 0.06%.
Crypto Market Edge
Bitcoin Had a Quiet Weekend Until Sunday Evening Down 2.22% from Friday’s US close to 07:40 UTC; ether down 5.83%
Price snapshot:
Bitcoin stood at 74,081.77 on Coinbase at 07:40 UTC, down 2.22% from 75,763.84 at Friday’s 21:00 UTC mark, and at 73,753.33 at the 08:05 UTC bar. Ether stood at 2,096.03, down 5.83%. The composite and Coinbase feeds agreed within 0.02% on bitcoin.
Flows and positioning:
Farside’s bitcoin page failed for a fifth session and its ether table still stops at 23 October. A secondary tracker shows outflows through last week; it is not a primary source, so no flow figure is printed. Wires describe Sunday’s fall as a liquidation of leveraged longs.
Leadership and rotation:
Bitcoin sat still on Saturday and most of Sunday. Then the 21:00 UTC hour on Sunday did most of the weekend’s work in one go. Ether fell more than twice as far. No trigger is stamped for the hour itself.
Catalysts and roadmap:
Strategy has filed no 8-K since 2 November and its sale count stays at 2. CPI prints Tuesday at 13:30 UTC.
TL;DR
- Nvidia’s board opened an independent inquiry into Jensen Huang late on Sunday; December Nasdaq futures stood 0.81% lower at the 07:45 UTC capture while Dow futures rose 0.35%.
- The story broke at 21:58 UTC, before the 23:00 UTC reopen, yet the Nasdaq contract rose first; the later fall carries no stamp, so this book names no cause.
- Payrolls rose 165,000 on Friday, lifting the 2-year yield 5bp to 4.51% and the dollar index 0.70%; CPI prints Tuesday at 13:30 UTC.
- The US struck Qeshm Island and launched Task Force Iron Gate over the weekend, yet January Brent stood 1.66% lower at the capture, with no stamped trigger held.
- Bitcoin fell 2.22% and ether 5.83% from Friday’s close, mostly in one Sunday hour; the S&P 500 lost 2.68% on the week despite Friday’s chip bounce.
Fun Fact
Nvidia Was Planned in a Diner Booth The founders met at a Denny’s in San Jose in 1993
Jensen Huang, Chris Malachowsky and Curtis Priem sketched out the company over coffee at a Denny’s restaurant in 1993. Denny’s later put up a plaque in the booth.
Meme of the Day:
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
p.s. There are 3 ways I can help you…
- Option 1: Collect Morning Income
A complete guide to the Premium Popper system.
Written to be clear, concise, and immediately actionable.
>> Learn More Here
- Option 2: Collect Weekly Income
A complete guide to the Tag ‘n Turn system.
>> Learn More Here
- Option 3: Join the Fast Forward Mentorship
>> Join the Fast Forward Mentorship – trade live, twice a week, with me and the crew.
PLUS Monthly on-demand 1-2-1’s
No fluff. Just profits, Tag ‘n Turn Pulse bars, Poppers, and Patterns that actually work.