Half of SOXX’s 9.4% fall came before the open; 95% of the December S&P futures’ 3.2% fall came after it, and the news the wires blame was public by breakfast
 Ahoy there, Trader! ⚓️
It’s Phil…
The News Was In by Breakfast. The S&P Waited for the Bell. A 3.2% fall in December S&P futures, almost all of it after 09:30 ET, on news that broke hours earlier
Going into the 09:30 ET open this morning, December S&P 500 futures were 0.17% lower. The chips were already falling. At 09:30 the cash market opened and everything else started falling with them.
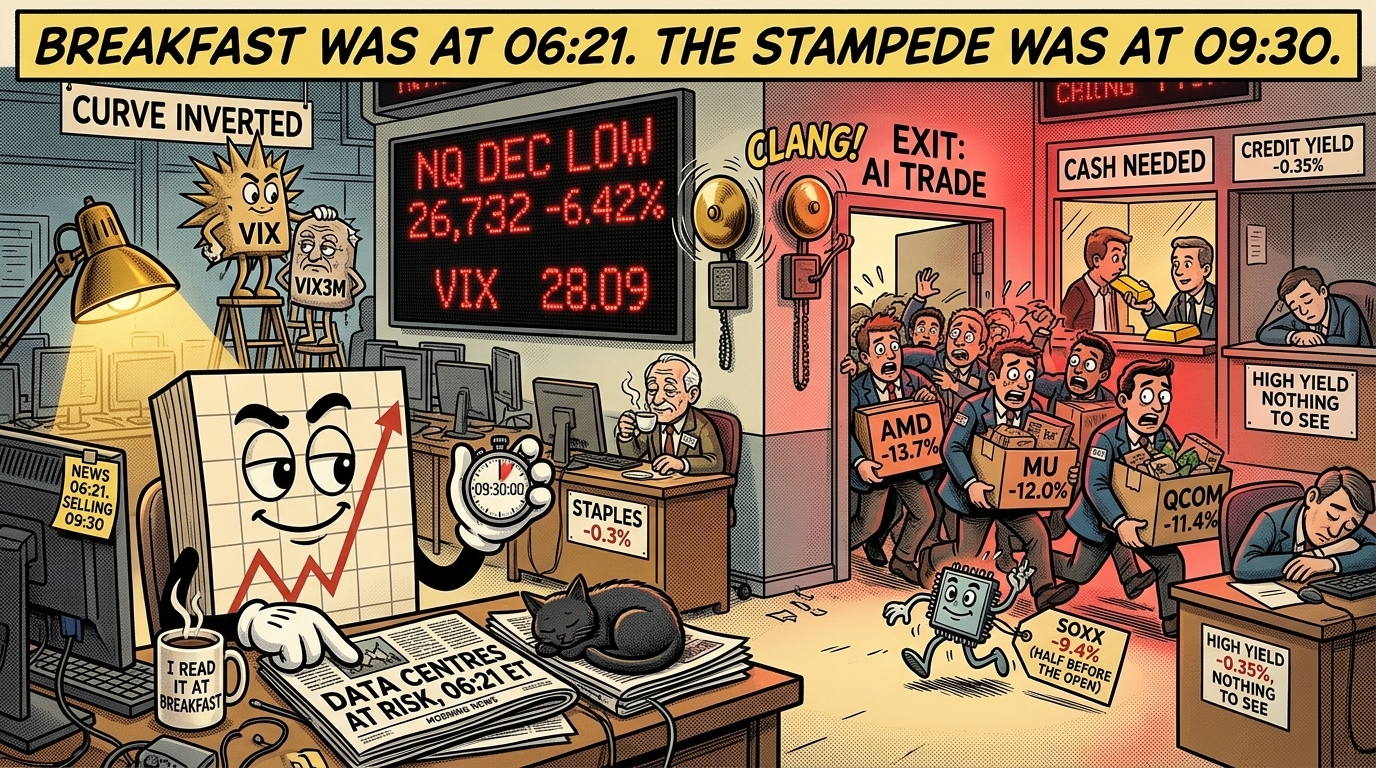
By 11:50 ET December S&P 500 futures stood at 7,471.25, 3.23% below Wednesday’s settlement. December Nasdaq 100 futures stood at 27,157.25, down 4.93%. At the low, in the 10:50 ET bar, they were down 3.88% and 6.42%. The VIX, which closed Wednesday at 16.61, touched 28.09 in the same bar. The Dow, which opened 0.61% higher, gave up more than 1,400 points from its open before lunch.
The one number that matters today is a share, not a level: about 95% of the December S&P futures’ fall arrived after 09:30 ET. The chips did not wait. SOXX opened 4.70% lower, half of its fall so far, and Qualcomm opened 13.36% down. The S&P futures were flat overnight and the 08:30 ET data barely moved them. Then the bell rang and the selling spread, and it did not come in one lump. December S&P futures closed lower in 16 of the 17 five-minute bars between the open and the low. There was no crash candle, no headline spike, no single minute anyone can point to. It was a queue.
What the market is selling. The selling is broad: on TradingView’s count, decliners outnumbered advancers 2,240 to 442, about five to one, and the Russell 2000 fund IWM fell 3.24%. But the damage is concentrated. It is the AI trade going down, and the rest of the market being dragged along behind it.
The chip fund SOXX was about 9.4% lower by 11:40 ET and SMH 8.43%. Arm fell about 12%, on Invezz’s report. AMD fell 13.66%, Micron 11.98%, Qualcomm 11.37%, Tesla 9.99%, Nvidia 6.72% and Broadcom 6.67%. Now look at the other end. Apple fell 1.24%, Amazon 1.71%, Alphabet 1.75%. Staples fell 0.26% and utilities 0.62%. Lockheed Martin, Wednesday’s casualty, fell 0.38%. AppLovin, reporting on its own, rose 29.51%. Banks opened higher and rolled over later: JPMorgan was 3.38% lower. Wednesday’s losers in defence and energy were among the quietest names on the board. The Wall Street Journal reports that Nvidia’s shares are now down for the year.
What everyone is blaming, and when they started blaming it. The wires, AP and Reuters among them, have a main story: the Democratic Congress, and a wave of local ballot measures against data centres, threaten the AI build-out. UBS estimates that about 30% of expected 2028 US data-centre capacity additions are at risk, according to Reuters. Texas governor-elect Hinojosa has pledged a moratorium on data-centre construction, according to Yahoo Finance. Then the company news: Qualcomm’s forecast, Arm’s smartphone royalties and Micron pausing plans for a Taiwan plant over a labour dispute.
Every one of those was public before the open. The UBS estimate ran on Reuters at 11:21 UTC, three hours before the bell. Qualcomm’s results came out on Wednesday night. Yahoo had Qualcomm, Micron and Arm “leading the chip sector lower” at 13:31 UTC. So the news was early enough to be the cause, and the chips priced it before the bell: the Kospi had already hit a 7-month closing low on chipmakers overnight, by Reuters’ account. The problem is the rest of the market. It had the same news for hours and the S&P futures did nothing with it. What changed at 09:30 was not the news. It was the clock.
The Clock
All times UTC. ET is five hours behind.
- 03:45 December WTI’s overnight low, 86.65. By 08:30 it was back above Wednesday’s 88.12 settlement. Oil turned about eight and a half hours before the open, too early to be the trigger.
- 11:21 Reuters runs the UBS data-centre estimate. December S&P futures steady.
- 12:00 The Bank of England raises Bank Rate to 4.00%, all nine votes for a hike. December S&P futures steady.
- 12:15 Bitcoin breaks below 80,000. Two hours before the bell.
- 13:30 US jobless claims 189,000 against 196,000 expected; Q3 productivity +3.6%, unit labour costs -0.7%. Good numbers. December S&P futures barely moved in the release bar, then drifted about 23 points lower in the hour before the open.
- 14:15 The 10-year yield peaks into the open, about 4.92% on TradingView’s series.
- 14:30 The open. SOXX opens 4.70% lower and Qualcomm 13.36% lower. The first five-minute bar takes 0.80% off December Nasdaq futures. In the first 30 minutes December S&P futures traded 1.83 times Wednesday’s volume in the same window.
- 15:10 The VIX closes a bar above the three-month VIX. The curve is inverted.
- 15:45-15:50 The low, inside the same quarter-hour, for December S&P and Nasdaq futures, the cash indices, bitcoin at 75,502, gold, the 10-year yield and SOXX. VIX 28.09.
- 16:20 A partial bounce. The VIX is 22.77 and the curve is still inverted, at 1.02.
What the Other Markets Are Saying
The fear is in stocks, not in bonds or credit. The VIX’s ratio to VIX3M peaked at 1.10 on closes. That is genuine stress in equity options. Bond volatility, the MOVE index, was up 0.23%. High yield was 0.35% lower and investment grade 0.11% higher. Treasuries rallied: the 2-year yield fell from about 4.63% at 09:15 ET to 4.49% at the low, on TradingView’s series, and TLT rose 0.39%. This is a stock-market problem that the bond market is watching from a safe distance.
It is not a carry unwind. The yen firmed about 0.3% against the dollar. A carry unwind looks very different.
It is not oil. Crude turned before dawn: December WTI was 2.10% higher at 89.97 at 16:30 UTC, on a renewed focus on the Iran war, according to Reuters. Iran’s Revolutionary Guards claim two tankers and a tugboat caught fire in Hormuz today; that is unconfirmed. Energy stocks were flat. Oil going up today is a separate story that happened to share a morning with this one.
December gold was sold at the open with stocks, though it is still 1.23% higher on the day. It made its low in the same quarter-hour as stocks. A haven that falls in the same bar as the thing it is meant to protect you from is being sold to raise cash.
What This Book Will Not Say
The market has offered three more explanations this morning, and each fails a test.
Iran. A report that US strike plans against Iran are “ready” was attached to the sell-off by 16:20 UTC on the stamps this book holds. The slide had started nearly two hours earlier, and the underlying New York Times report dates from 8 and 9 October. It arrived late.
The data. Strong jobs and productivity numbers could mean a hawkish Fed, and the Cleveland Fed’s Hammack said at 13:50 UTC that policy must become restrictive. But yields rose into the open and fell hard after it. If the market were selling stocks on a hawkish Fed, bonds would not be the thing it bought.
The rumour. One Stocktwits post claims named hedge funds are in trouble. This book has no source for it and will not repeat the names.
Labelled Speculation
None of what follows is a retrieved cause. Every item is stamped, and none is stamped as the trigger for the 09:30 selling.
The strongest candidate is positioning. Nomura’s Charlie McElligott told MarketWatch at 16:23 UTC: “They’re shooting the generals”, meaning the year’s most crowded winners are being sold to cut risk. The shape fits: the steady grind, the volume, and the AI names at the centre of the year’s best trades falling furthest while the boring ones barely moved. The quote came two hours after the selling began, so it describes the move. It did not cause it.
The second is credit, and few are connecting it yet. At 14:40 UTC the Richmond Fed’s Barkin said he finds it hard to worry about the big cloud companies’ credit but wonders about “intermediaries”, the lenders and funds that sit between them and the money. Finimize, citing Reuters at 15:29 UTC, wrote that the selling spread to cloud-capacity firms on “funding risk”. High yield is down only 0.35%. If that number starts to move, this story changes.
What Would Settle It
- The close. A session that recovers half its loss into the bell was a positioning flush. One that closes near its 10:50 ET low was a repricing.
- The VIX curve. If the VIX is back below VIX3M by the close, the market thinks the stress is temporary. If it stays inverted tomorrow, it does not.
- Credit. If high yield stays within about 1% of Wednesday’s close, this is an equity story. If it breaks lower, it has become something else.
- Payrolls, Friday at 13:30 UTC. The first piece of news since the open that the market has not seen yet.
- Nvidia, 17 November. The result most likely to tell the market whether the AI build-out has lost its customers or only its admirers.
AP says the S&P 500 is on track for its worst day since April 2025. This book has not checked that window and is not adding its name to the claim. It will say this much: the news was in by breakfast, the chips sold it at once, and the rest of the market waited for the bell, which describes either a market that already knew, or one that was only waiting for somebody to sell to.
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
p.s. There are 3 ways I can help you…
- Option 1: Collect Morning Income
A complete guide to the Premium Popper system.
Written to be clear, concise, and immediately actionable.
>> Learn More Here
- Option 2: Collect Weekly Income
A complete guide to the Tag ‘n Turn system.
>> Learn More Here
- Option 3: Join the Fast Forward Mentorship
>> Join the Fast Forward Mentorship – trade live, twice a week, with me and the crew.
PLUS Monthly on-demand 1-2-1’s
No fluff. Just profits, Tag ‘n Turn Pulse bars, Poppers, and Patterns that actually work.