Equity fear jumped 21%, bond fear fell 1.4%, and 81% of the Nasdaq-100 fall has nothing attached to it
 Ahoy there, Trader! ⚓️
It’s Phil…
Volatility Closed at 19.99 and Refused to Panic Properly Equity fear jumped 21%. Bond fear went for a lie-down. One of them is lying.
For six weeks this letter has been complaining that the fear gauge would not move. On Friday it moved. It closed 19.99 from 16.46, up 21.44593%, printed 22.31 inside the session, and then stopped dead at the one threshold that would have turned a bad afternoon into an event. Three-month volatility closed 20.50. The ratio between them went to 0.975122 from 0.890211, which is compression with a view, and it is still contango by 0.51 points. A funding crisis is the thing that would have inverted that curve. It did not invert, and that is not proof there was no funding stress. It is the absence of the one piece of evidence this desk would accept for it.
Everything that was supposed to agree declined to. Bond volatility fell 1.351941%. The yen moved 0.000633%, in a currency that exists to panic on your behalf. All fourteen Treasury tenors moved between zero and minus five basis points, the 30-year unchanged, on a morning import prices printed 8.1% on the year. Six of eleven sectors rose, energy leading at 2.524038%.
So something large happened and the confirming apparatus sat it out. Here is the part nobody else will print. The only releases carrying a tier-one timestamp landed before the bell, which buys 18.514637% of the Nasdaq-100 fall. 81.485363% of the move has no named cause in this book. Crude added over 2.6% on both benchmarks and energy led every sector, and nothing in this book says why that happened either. Wednesday prices 13 billion of twenty-year paper onto the tenor nobody looked at on Friday.
The One That Mattered
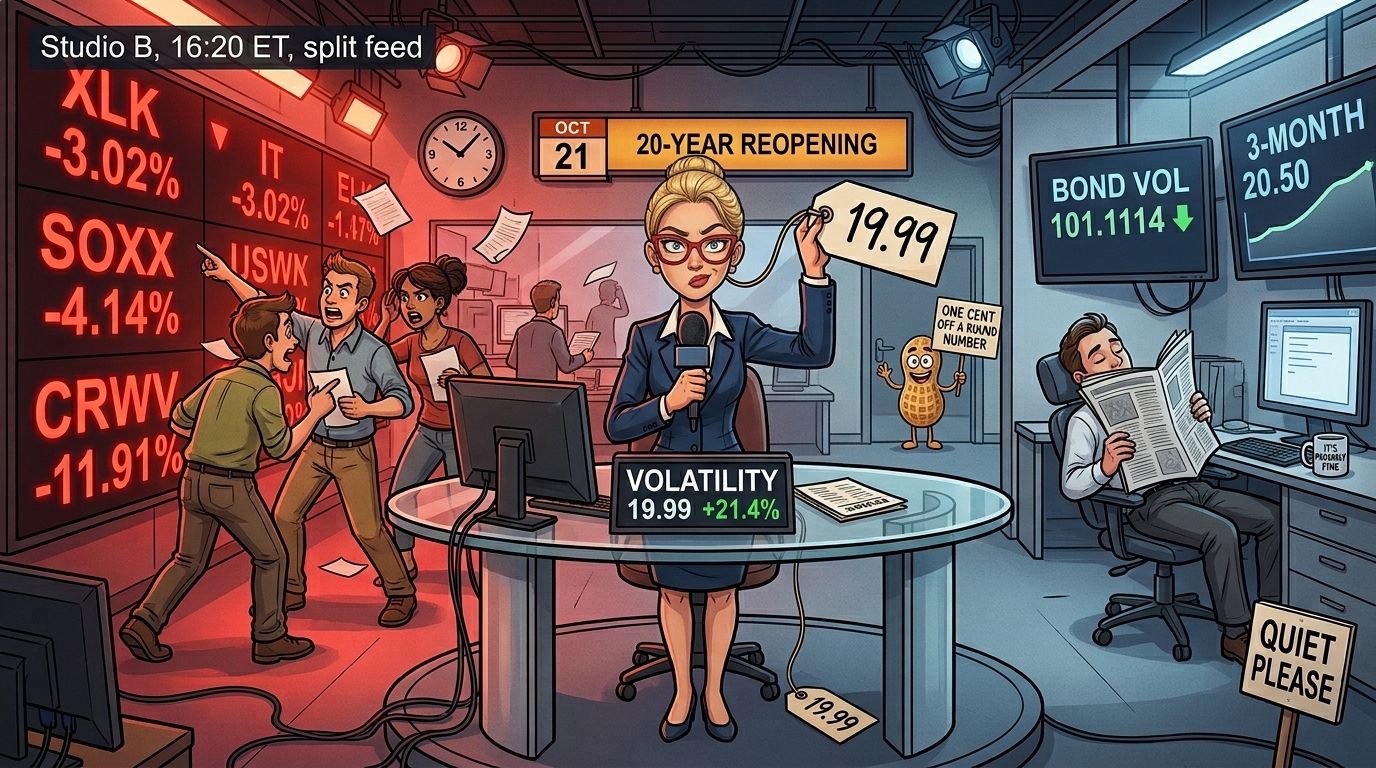
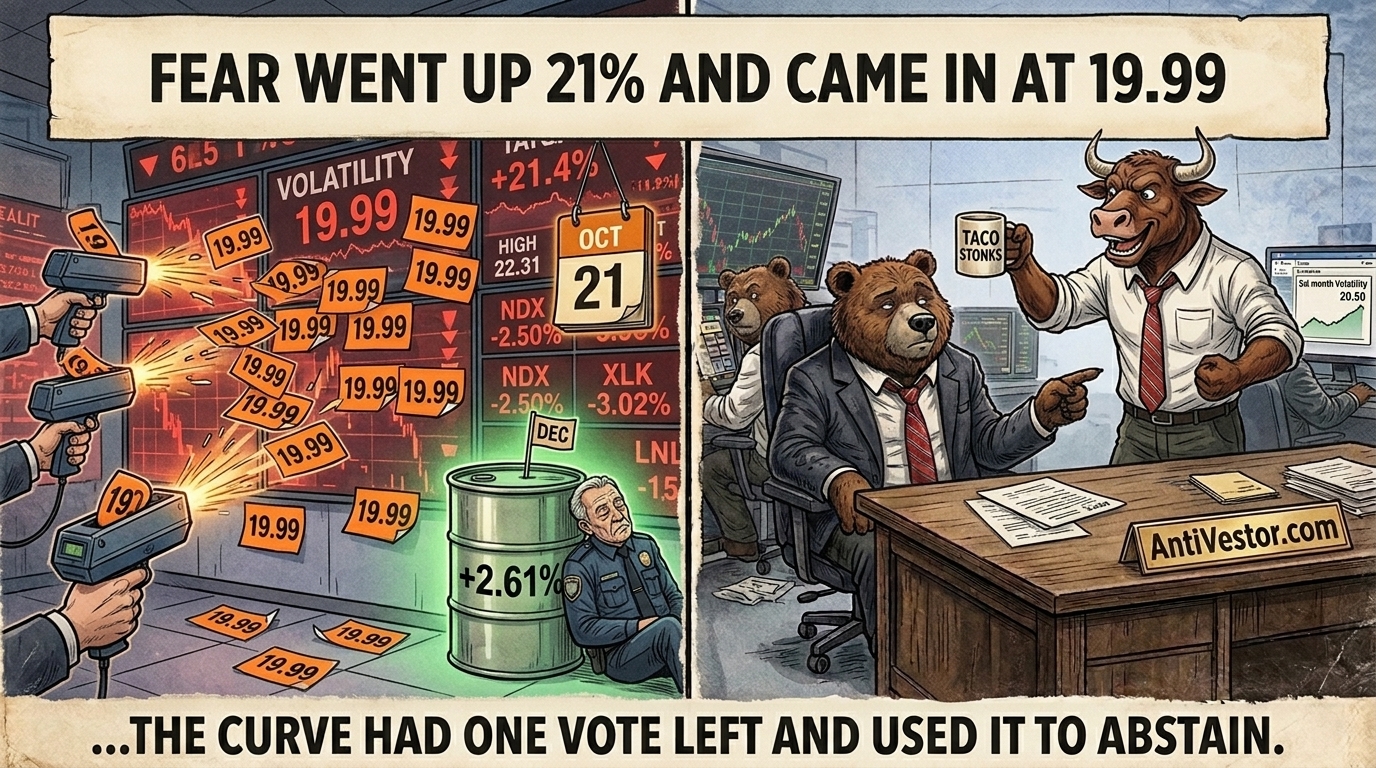
Volatility at 19.99 is the number of the week and also the joke of it, because 19.99 is not a level, it is a price tag. Somewhere a marketing department is furious it did not get there first. And the gag holds, because the thing behaved exactly like a price tag: eye-catching, one cent short of the round number, and telling you nothing about what is in the box. The three-month curve had the deciding vote at 0.975122 and used it to abstain. Bond volatility fell. The yen did not move. What is a 21% jump in volatility actually worth, if nothing else on the board will confirm it? We went down the rabbit hole in today’s Macro Edge. [https://antivestor.com/macro-edge]
Overnight Excitement
December Nasdaq futures are up 1.373696% from Friday’s 29,391.5 settlement, which clears the 1.0% trigger by 0.373696 points and falls 0.126304 short of leading this section. December S&P futures are up 0.736606%, so the dispersion between them is 0.63709 points and it is pointing the same way it pointed on the way down: the index that fell hardest is the one bouncing hardest. Japan and China both traded, confirmed on a constituent each, and no level from either is publishable on this desk. The complex that lost 2.5% on Friday is the one bouncing hardest, which is either mean reversion or a short memory, and we will know by Wednesday. One honest caveat on all of that: re-quoted at 07:55 UTC the Nasdaq leg had eased to 1.115969% and the S&P leg to 0.554889%, so the section still fires and it is now 0.115969 points from not firing.
Stock Market Edge
The Credit Market Widened, Quietly, and We Are Not Going to Tell You the Sign Is Established Low-grade debt gave back 0.35% whilst the curve it borrows against fell 3 basis points
Premarket snapshot:
Taken from the 06:30 to 06:35 UTC bar this morning, read twice, byte-identical on all four contracts. December S&P 7,761.00, up 0.736606% on Friday’s 7,704.25. December Nasdaq 29,795.25. December Dow 52,442.00. December Russell 2,755.50. There is no premarket volatility print on this desk at all, so 19.99 is carried as Friday’s cash close and labelled as such.
Sector rotation:
Six of eleven proxies rose. Energy 2.524038%, utilities 1.344538%, staples 1.084449%. Technology last at minus 3.023416%. The spread went to 5.547454 points from 3.438887. An index fell 1.092708% whilst a majority of its sectors rose, which is a sentence about arithmetic rather than about fear.
Earnings or guidance:
Somebody will tell you today that credit held up fine on Friday. Here is the figure everybody will reach for, and here is why it does not settle anything. The high-yield proxy fell 0.350058% whilst the curve at its own 3.25-year duration fell three basis points, which on a duration-matched read comes out near 13.77 basis points on the widening side. We are publishing the arithmetic and refusing the sign, because the curve barely moved at the tenor where that instrument actually lives, the long-proxy reconciliation behind the method tests only the long end, our duration figure is a session stale, and the fund’s own page is serving June data. Indicative. Not established.
Cross-asset nuance:
The dollar closed 101.779, down 0.22058%. December gold settled 4,181.10, up 0.263783%, whilst gold spot fell 0.069524%, so the two legs went opposite ways and whoever writes “gold fell on Friday” is half right by construction. Bond volatility closed 101.1114, down 1.351941%, against a 97.5903 intraday low and a 99.3123 open, so it fell on the day and firmed into the bell.
Crypto Market Edge
21% More Fear, and Crypto Moved Three-Quarters of 1% The assets everyone calls correlated did not act correlated, and nothing here says why
Price snapshot:
Bitcoin marked 81,513.66, down 0.75332%. Ether marked 2,420.53, down 0.765415%. Both on the 00:00 UTC convention and neither on a cash session. Ether’s magnitude was 1.016055 times bitcoin’s, down from 1.269, so after weeks of ether doing the dramatic work the two of them finally moved the same distance on the same day, in the same direction, with no particular conviction.
Flows and positioning:
Bitcoin funds reversed to minus 82.4 million from plus 5.1 million, and two issuers out of twelve did all of it at minus 71.8 million and minus 10.6 million. Ether funds took minus 69.7 million and a single issuer printed the entire total, with every one of the other ten columns at a genuine printed zero. Both rows reconcile exactly to their own stated totals on two cache-busted reads.
Leadership and rotation:
Ten of twelve bitcoin columns and ten of eleven ether columns did nothing whatsoever. The ether outflow run stands at three sessions, counted from the visible window rather than carried, because 13 October’s inflow broke the previous streak and nobody gets to say eleventh.
Catalysts and roadmap:
Two bills price today at 95 and 82 billion. Housing starts, building permits and state employment land Tuesday. The twenty-year reopening prices Wednesday at 13 billion, onto the only tenor holding the strict curve maximum at 5.47%. The committee meets on the 27th and 28th with no projection round.
TL;DR
- Volatility closed 19.99, up 21.44593%, then declined to invert its own three-month curve, which held contango at a ratio of 0.975122.
- Bond volatility fell 1.351941% on the same session, the yen moved 0.000633%, and all fourteen tenors moved between zero and minus five basis points, the 30-year unchanged.
- Only 18.514637% of the Nasdaq-100 fall sits in the opening gap, which is everything the pre-open releases can buy. The remaining 81.485363% has no cause here.
- Six of eleven sector proxies rose whilst the index fell 1.092708%, energy led at 2.524038%, and NYSE new highs still beat new lows 58 to 38.
- December crude settled 99.02 and December Brent 109.86, both over 2.6% higher, widening the Brent premium to 10.84 from 9.42 on a same-date basis.
Fun Fact
The Index Everybody Quotes Is Not the Index They Built The original fear gauge still publishes, under a new name, watched by almost nobody
The volatility index the Cboe launched in 1993 was built on options on the S&P 100. When the methodology moved to the S&P 500 in 2003, the original was not retired. It was renamed VXO, and it is still publishing, quietly, next to the number every newsroom quotes.
Meme of the Day:
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
p.s. There are 3 ways I can help you…
- Option 1: Collect Morning Income
A complete guide to the Premium Popper system.
Written to be clear, concise, and immediately actionable.
>> Learn More Here
- Option 2: Collect Weekly Income
A complete guide to the Tag ‘n Turn system.
>> Learn More Here
- Option 3: Join the Fast Forward Mentorship
>> Join the Fast Forward Mentorship – trade live, twice a week, with me and the crew.
PLUS Monthly on-demand 1-2-1’s
No fluff. Just profits, Tag ‘n Turn Pulse bars, Poppers, and Patterns that actually work.