A 1.4% fall, a 0.4% Dow gain and no named cause for the index
 Ahoy there, Trader! ⚓️
It’s Phil…
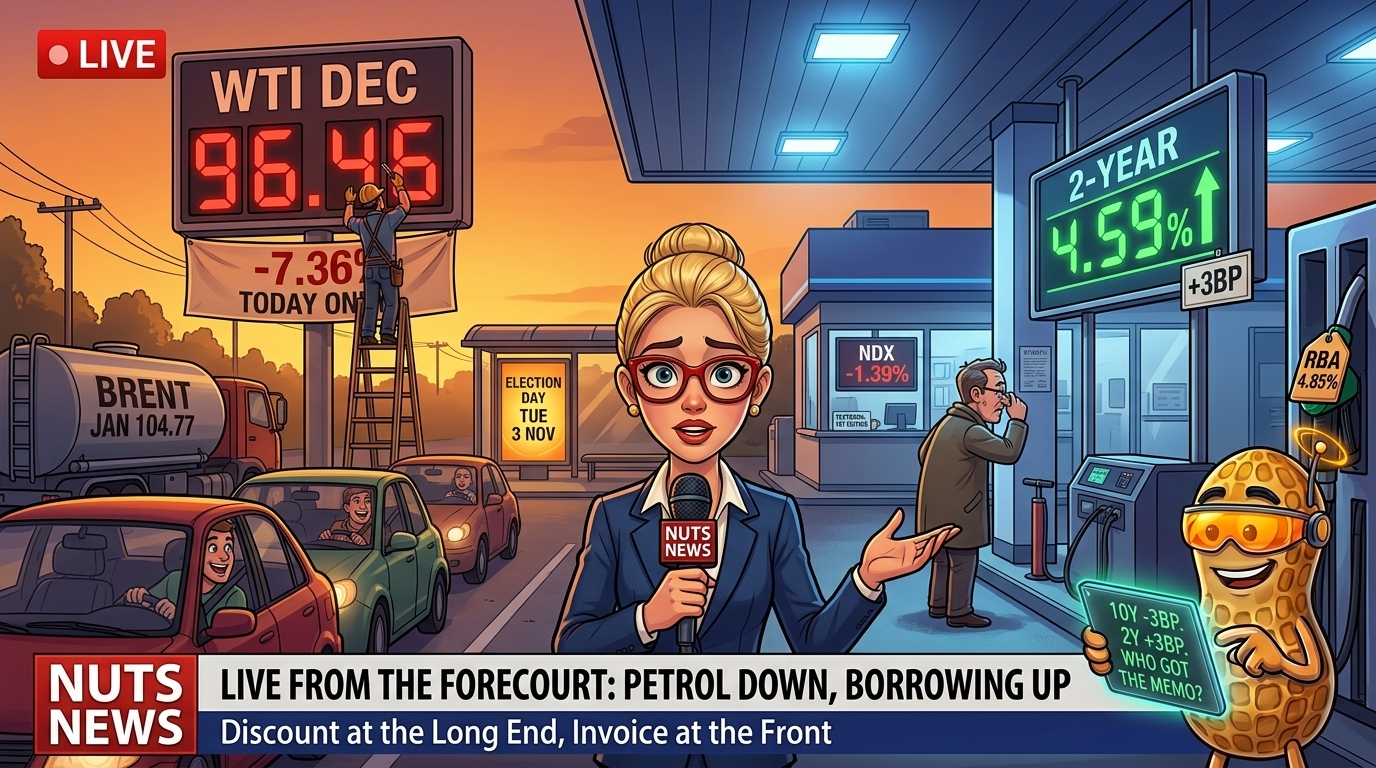
On Monday the world’s most argued-over commodity got 7.36% cheaper, and the price of borrowing money for two years went up.
December WTI settled at 96.46, down from 104.12. January Brent settled at 104.77, down 7.63%. The move followed reports of Qatar-led talks between Washington and Tehran. This book ran the clock on it: the first timed report landed on Sunday evening, a minute after crude reopened at 102.39, and about three quarters of the fall came after it. For crude, and only for crude, the talks go down as a named cause, labelled as reports. About a quarter of the fall came in a single Monday hour from 13:00 UTC, when the wires had both presidents talking up a deal; this book cannot stamp those remarks, so that leg stays unclaimed.
The textbook then writes itself. Cheaper oil, lower inflation expectations, a lower 2-year yield. The 2-year Treasury yield closed at 4.59%, up 3 basis points.
The long end did fall. The 10-year fell 3bp to 4.91% and the 30-year 3bp to 5.28%, so the 2s10s spread narrowed to 32bp from 38bp. But the 10-year has now fallen three sessions running, from 5.05%, including Friday, when crude rose. The 2-year had fallen three sessions running too, from 4.70% to 4.56%. On Monday it stopped.
What moved the 2-year? This book looked. It checked the Treasury curve, the Fed’s own speech pages and the economic calendar. It found no Fed speaker with policy content on Monday and a strong ISM manufacturing reading at 15:00 UTC that it holds on relays only, with no forecast held on two routes. It cannot size a surprise it cannot see. So the 2-year’s rise has no named cause in this book.
Equities split. The Dow rose 0.41%. Consumer discretionary rose 2.41%, financials 1.86%, materials 1.76%. Energy fell 3.96%. Technology fell 2.95%.
The Nasdaq 100 opened 0.62% higher, made its high in the first hour at 28,753.39, and closed at 27,989.82, down 1.39%. It spent six and a half hours correcting its opening remarks. All of the close-to-close fall arrived after the opening bell. Marvell fell 12.72% on its all-stock deal for Lumentum, and Lumentum fell 18.59%, but a deal is a cause for its own shares, and this book holds no index weights. The Nasdaq 100’s fall has no named cause in this book. The market’s own explanation, pre-election caution, is what people said afterwards. They said it after the tape had fallen. Nor does this book hold a cause for the VIX’s highest close in 25 sessions or for bitcoin’s 1.97% slip.
And then gold, which had an exam. Monday morning’s Macro Edge wrote down the test before the open: on the next bad day for stocks, if gold falls again it is behaving as collateral, and if it rises, Friday was the exception. Monday was a down day for the Nasdaq 100, a smaller one at 1.39% against Friday’s 3.46%, whilst the Dow rose. Spot gold rose 1.90% to 3,946.27. By the rule as written, Friday reads as the exception, on one observation, and spot is 0.95% lower this morning. We wrote down what would settle it before it was settled, which is the only time writing it down counts.
The one number that mattered was crude’s 7.36%, because of what the 2-year did next to it.
Overnight, the Reserve Bank of Australia raised rates. Crude has bounced 1.48%. Futures are 0.36% lower. Americans vote today. The futures have voted already, which is not legally binding.
The One That Mattered
Crude lost 7.36% on reports of peace talks, and the textbook says that is a gift to the front end: cheaper oil, softer inflation, a lower 2-year. The long end took the gift, 3bp lower at 10 and 30 years. The 2-year rose 3bp to 4.59%. Nothing on the calendar this book can measure explains it. Why did the 2-year rise on the day oil fell 7.4%? We are not answering it here. We went looking in today’s Macro Edge. https://antivestor.com/macro-edge
Our Top Trader Uses This 9:50 AM Secret to Target $500 Per Day Regardless Of Which Direction The Market Moves https://antivestor.com/ppp-webinar
The Midterms, Tonight
435 House Seats, 35 Senate Seats, 36 Governors. The Market Closes First. The cash bell rings 2 hours before the first polls close, and the futures sit up for the rest
Americans vote today for every seat in the House, 35 of the 100 in the Senate and 36 governorships. The stock market, which has opinions on all of it, will be shut by the time anyone finds out.
The timetable, in New York time. The cash session closes at 16:00. The first polls close at 18:00 in parts of Indiana and Kentucky, which is also the minute December futures reopen after their daily break. Georgia follows at 19:00, Ohio and North Carolina at 19:30, Pennsylvania and most of the East at 20:00, Arizona at 21:00, Nevada at 22:00, California at 23:00. Alaska shuts the door at 01:00 on Wednesday, or 06:00 UTC.
So the result will be traded first by the futures, overnight, by whoever is still awake. Wednesday’s 07:45 UTC capture comes after the last poll has closed, and it will be the first read of the verdict in this book.
What this book will not do is tell you which outcome the market wants. It holds no odds it trusts and no poll it can stamp, and Monday’s “pre-election caution” was said after the Nasdaq 100 had already fallen. The tape votes tonight. We count tomorrow.
Overnight Excitement
Australia Hiked. Japan Took the Day Off. The Oil Bounced. The futures stayed in the quiet band; the Reserve Bank of Australia did not
US futures barely stirred overnight: December S&P 500 futures were 0.36% below Monday’s final close at the 07:45 UTC capture, inside the normal band. The section fires on the Reserve Bank of Australia, not the futures.
The Reserve Bank of Australia raised its cash rate 25 basis points to 4.85% from 4.60% at 03:30 UTC, on a 6-3 vote by the wire’s count. Japan was shut for Culture Day, so Tokyo had nothing to say and said it all day.
Korea and Taiwan traded lower on syndicated reports, led by chip stocks. US strikes on Iran’s Qeshm Island were reported. December WTI stood at 97.89 at 08:25 UTC, up 1.48% from Monday’s settlement, and spot gold was 0.95% lower at 3,908.87. This book does not hold that the strikes moved crude; it holds that both happened, which is less exciting and more true.
Stock Market Edge
Futures Are 0.4% Lower. Election Day Has Started. Neither Has Decided Anything. A quiet capture after a loud Monday, with AMD tonight
Premarket snapshot:
At the 07:45 to 07:50 UTC capture, December S&P 500 futures stood at 7,559.50, 0.36% below Monday’s final close of 7,587. December Nasdaq 100 futures were 0.31% lower at 28,136.50, Dow futures 0.55% lower at 51,863 and Russell futures 0.34% lower at 2,810.50. All four made their overnight lows between 07:00 and 07:20 UTC. A re-quote at 08:20 UTC read S&P futures 0.33% lower at 7,562.25. The VIX traded at 21.63 in global hours, after a Monday close of 21.15, its highest close in 25 sessions. A 0.36% dip on Election Day morning is not a verdict. It is a turnout figure.
Sector rotation:
Eight of eleven sector proxies rose on Monday, and the spread between best and worst was 6.37 points. Consumer discretionary +2.41%, financials +1.86%, materials +1.76%, staples +1.58%, industrials +1.38%. Energy -3.96%, technology -2.95%, health care -0.15%. NYSE advancers beat decliners 1,669 to 997; on Nasdaq, a count of all listed issues, decliners led 2,524 to 2,438. The semiconductor funds disagreed again, SOXX -3.79% and SMH -2.71%. Most of the sector table had a good day. The technology end of it did not.
Earnings or guidance:
Marvell agreed to buy Lumentum in stock, and both shares fell, Marvell 12.72% to 171.41 and Lumentum 18.59% to 684.40. A merger in which neither side’s shareholders feel richer is at least even-handed. Oracle fell 8.76% and AMD 7.52%, with no cause held for either; AMD reports tonight. Intel fell another 8.80% to 59.97 and Reddit held near Friday’s close at 90.97. Apple reported at 21:30 UTC and Palantir at 21:05 UTC, and write-ups with no quote time put both lower after hours.
Cross-asset nuance:
The 2-year rose 3bp to 4.59% whilst the 10-year and 30-year fell 3bp, and the 2s10s spread narrowed 6bp to 32bp. The VIX rose 8.91% to 21.15; VIX3M closed at 21.60, a ratio of 0.98, still contango. The dollar index slipped 0.16% to 101.80. Spot gold rose 1.90% and December silver 3.27%. Yesterday this book named the Qatar-led talks as the cause for December crude and said WTI would stay under 104.12 through Tuesday. It settled at 96.46 on Monday, which is a hit on the first leg.
Crypto Market Edge
Most of the Cyclicals Had a Good Monday. Bitcoin Was Not Invited. A 1.97% slip, a fresh Strategy purchase and a flow table that still will not load
Price snapshot:
Bitcoin was 76,710.54 on the Tuesday 00:00 UTC mark, 1.97% below Monday’s 78,253.75, and 76,532.67 at 08:25 UTC. Ether was 2,250.31, down 0.98%. On a day the Dow rose and consumer discretionary rose 2.41%, bitcoin went the other way.
Flows and positioning:
Farside’s bitcoin and ether tables both returned errors on two attempts, again. Relays carry figures; this book publishes none of them. Its last frozen bitcoin cumulative is 57,361 million dollars, as at 23 October, which is ancient history by the standards of a flow table.
Leadership and rotation:
Bitcoin ranked third on the Stocktwits crypto board at 07:30 UTC, with its canonical sentiment score bearish. Ether fell less. Attention measures what people are saying, not what prices did.
Catalysts and roadmap:
Strategy’s 2 November 8-K reports 811 bitcoin bought, for 849,327 held. That is a purchase. The count of sales stays at two. Macro risk this week: the vote today, refunding and ISM services Wednesday, payrolls Friday.
TL;DR
- December WTI fell 7.36% to 96.46 on reports of Qatar-led US-Iran talks; about three quarters of the fall came after the first timed report, a quarter in one unstamped hour.
- The 2-year rose 3bp to 4.59%, ending a three-session decline, as the 10-year and 30-year fell 3bp; the 2-year’s rise has no named cause here.
- The Nasdaq 100 opened 0.62% higher and closed 1.39% lower whilst the Dow rose 0.41%; the index fall has no named cause in this book.
- Spot gold rose 1.90% on a down day for the Nasdaq 100, so by the test written in Monday’s Macro Edge, Friday’s 3.68% fall reads as the exception.
- Futures were 0.36% lower at the capture on midterm day; polls close from 23:00 UTC to 06:00 UTC, so overnight futures trade the result before Wednesday’s open.
Fun Fact
The Polls Are Open, and So Is the Market Election Day is a full trading day
The New York Stock Exchange used to close on Election Day, and from 1972 to 1980 only in presidential years. It has opened on Election Day since 1984. Today the bell rings at 09:30 ET, regardless of who is ahead.
Meme of the Day:
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
p.s. There are 3 ways I can help you…
- Option 1: Collect Morning Income
A complete guide to the Premium Popper system.
Written to be clear, concise, and immediately actionable.
>> Learn More Here
- Option 2: Collect Weekly Income
A complete guide to the Tag ‘n Turn system.
>> Learn More Here
- Option 3: Join the Fast Forward Mentorship
>> Join the Fast Forward Mentorship – trade live, twice a week, with me and the crew.
PLUS Monthly on-demand 1-2-1’s
No fluff. Just profits, Tag ‘n Turn Pulse bars, Poppers, and Patterns that actually work.