The VIX fell 4.73% and the MOVE index 4.22% on the eve of the statement, the 2-year rose 2 basis points, the 20-year fell 1, and the committee speaks at 18:00 UTC
⚓ Weathervane. The wind is coming from the long end. The policy rate has been frozen for most of the year whilst the term premium does the tightening, and the price of long money is set by deficits, issuance supply and a synchronised global duration bid rather than by the committee. Higher-for-longer stopped being a Fed decision and became a bond-market fact. The cruise ship is holding this heading.
 Ahoy there, Trader! ⚓️
It’s Phil…
Why did the price of insurance against the Fed fall 4% in bonds and in stocks the day before the Fed decided anything?
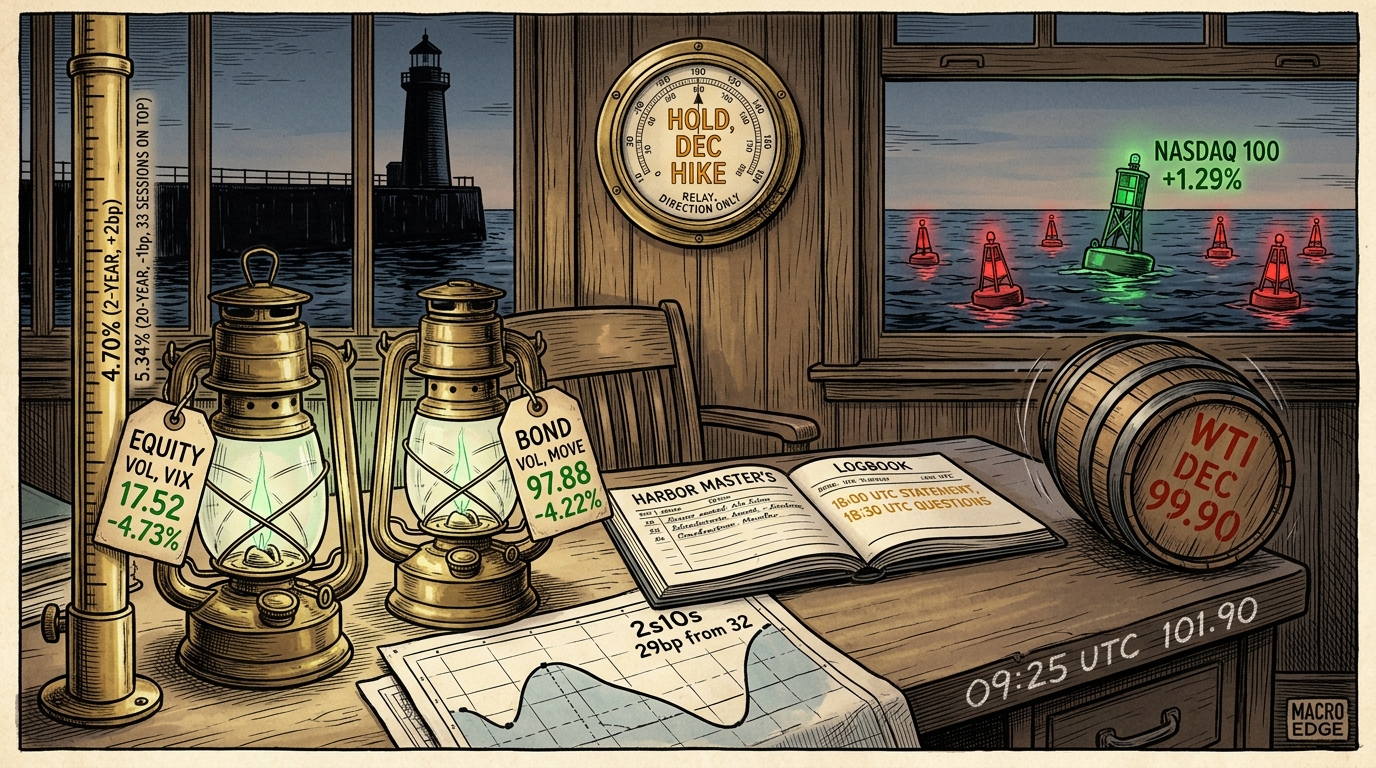
The VIX is the market’s price for being wrong about the S&P 500 over the next month; the MOVE index is the same price for Treasuries. On Tuesday, the session before a Federal Reserve statement at 18:00 UTC and a press conference at 18:30 UTC, the VIX closed 17.52, down 4.73%, and the MOVE 97.88, down 4.22%. Each is at its lowest close since 21 October. The curve was quieter: the 2-year rose 2 basis points to 4.70%, the 10-year fell 1 to 4.99% and the 20-year 1 to 5.34%, the top of the curve for a 33rd session. 2s10s narrowed from 32 to 29. High yield rose 0.52% with long Treasuries 0.06% lower, which on the durations we hold reads as spreads tightening.
The textbook is short: implied volatility is a price for uncertainty, a scheduled decision is a lump of it with a time attached, so the price should rise into the event and fall after it. Desks call the fall the crush. On Tuesday the fall arrived a day early, in both markets, with the decision still to come.
Two readings fit. The first is that the market has read the statement already: the relay we print by direction only has a hold heavily favoured today and a hike favoured by December, and a 2-year at 4.70% against a 3.75 to 4.00% funds range says the same thing in bond form. If the outcome is known, insurance against it is worth less. The second is less comfortable: the price of being wrong fell because nobody expects to be, which is not the same as nobody being able to be.
The two readings make opposite predictions for this afternoon, and both are checkable on the instruments in this letter. If the market has read the statement correctly, the MOVE closes today below Tuesday’s 97.88 and the 2-year within 5 basis points of 4.70%, because nothing was learned. If the market stopped paying for the right to be wrong, the tell is the MOVE closing today above 97.88 while the statement matches the relay’s hold. A hold that moves bond volatility up is a hold the market did not understand. That is tonight’s number, and it is a volatility index, not a rate.
Phil’s Musing
I have never liked buying insurance the morning after the storm, and I have rarely watched a market sell it the night before one. It may know something. Markets often do, right up until they do not. If the MOVE closes today above Tuesday’s 97.88 with the expected hold delivered, then Tuesday’s calm was a price and not a view.
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
P.S. – Phils Footnote I had assumed, without ever checking, that bond volatility always rose into a Fed day. Tuesday’s 4.22% fall is the first time I have put the number beside the calendar rather than assumed it, and I am not sure the assumption survives the look. We will know by this evening whether the market was early or wrong, which is the one question about tonight that a chart can answer.
🗂 Desk Notes – Part 238 | 28 Oct 2026
Raw briefing. Observations, not trades. Everything below is in lock_part238.json (453 figures, validated, zero failures, one intended warning).
Session read (§8.4)
SESSION BRIDGE: prior session (Tue) full reaction [December ES +0.567% on Monday’s settle, 7,758.25 from 7,714.50; cash SPX +0.597% to 7,722.60, NDX +1.291%, DJI +0.030%, RUT +1.164%; VIX 17.52, -4.731%; MOVE 97.884, -4.224%; December WTI 99.90, -1.828%; after the bell on relays Seagate -7.3%, NXP about -9%, Enphase about -16%, Robinhood -5%, Visa -1.2%]; live premarket ES +0.006% / NQ +0.381%, VIX +0.23% (17.56 on the 07:45Z global-hours bar against 17.52); threshold: none.
Reasoning. ES prior session +0.567% is 0.433 short of the 1.0% investigate band. VIX -4.73% is 3.27 short of the 8% volatility leg. December WTI -1.83% is 2.17 short of the 4% commodity leg. Largest overnight move at the 07:45 to 07:50Z capture: NQ +0.3807%, inside the 0.3 to 0.6% normal band, 0.219 points below its ceiling. No manual override.
§8.4.2 limbs: (a) NDX +1.2914% is at most third in absolute size in the held window behind the 22 Oct 2.915% and 14 Oct 2.024% falls: not tripped. (b) Sector spread 3.755 points on the SPDR proxies: not tripped. (c) Boeing -10.690% on its own daily bar is a table constituent: TRIPPED. The board and the decomposition are mandatory and were run.
Close-to-open window. Capture bar 07:45 to 07:50Z read at 08:05Z and 08:11Z on all four December contracts, byte-identical on open, high, low, close and volume; the forming 08:05Z control bar mutated on all four. ES 7,758.75 (+0.006%), NQ 29,925.50 (+0.381%), YM 52,414 (-0.314%), RTY 2,821.60 (-0.244%). Overnight ranges since the Tuesday 22:00Z reopen: ES 7,752.25 to 7,766.50; NQ 29,783.75 to 29,987.00; YM 52,395 to 52,630; RTY 2,819.70 to 2,830.70. A volume spike hit all four contracts on the 07:55Z bar after the capture: ES 5,902 contracts against a capture-bar 1,221; no headline in the sampled feeds.
Contract roll: none due. December equity contracts roll on the third Friday of December. December Brent expires Friday 30 Oct; January is already the front by volume (381,044 against 270,028) and is quoted alongside. December WTI is the front by volume (256,947 against January’s 111,603).
Overnight Excitement (§8.5)
Does not fire. Largest overnight move NQ +0.381% at the capture and +0.424% at the 08:30Z re-quote, inside the normal band both times, 0.619 and 0.576 points short of the 1.0% trigger. Direction with attribution only: Seoul closed sharply higher (SK Hynix +9.1% on a Dow Jones wrap, Kospi about +5.8%), Tokyo higher, Hong Kong and Shanghai marginally higher (DJN 05:27Z). Europe Tuesday: DAX higher, FTSE 100 lower, both on Trading Economics and dpa-AFX relays. RBNZ held at 2.75% against a hike consensus at 01:00Z. No level is printed for any non-US index.
§8.3 candidate cause board
Largest prior-session move at index scope: Nasdaq 100 +1.291%. Decomposition: gap 35.39%, intraday 64.61%. S&P 500: gap 49.53%, intraday 50.47%. Dow: net +15.99 points after an 84.09-point gap down, so the shares are -525.9% and +625.9% and are not published. majority_unexplained is true: 64.61% of the Nasdaq 100’s rise has no named cause.
| Candidate | Class | Stamp (UTC) | Precedes majority | Large enough | Disposition |
|---|---|---|---|---|---|
| Anthropic IPO and AI rotation narrative | 3 | Tue 13:38 (Zacks) | NOT ESTABLISHED, no index path held; a carried narrative | Not testable | Refusal, published; ruling-U follow-through marked in the ledger |
| Nvidia 3 billion dollar stake in Meta’s offering | 3 | Tue 13:12 (Schwab) | No, gap 35.39% at most | No | Coincidence, published: Meta -1.65% on 1.66x volume |
| Boeing results and delivery cut | 2 | Tue 11:58 (TheStreet) | Yes, scoped to BA | Yes, for BA | Published cause, scoped to BA -10.69% |
| SoFi results and raised outlook | 2 | Tue 12:49 (TheStreet) | Yes, scoped to SOFI | Yes, for SOFI | Published cause, scoped to SOFI +13.42% |
| Qatar and Tehran diplomacy wires, crude under 100 | 3 | Tue 13:49 (DJN), 18:52 (dpa-AFX) | NOT ESTABLISHED, no crude path | Unknown | Refusal, published |
| GM listing switch to Nasdaq | 2 | Tue 14:14 (DJ/WSJ) | No: GM opened 78.72 against 76.31, 57% of its 5.54% day, before the stamp | No | Refusal, published |
| After-hours reporters Seagate, NXP, Enphase, Robinhood, Visa | 2 | Tue 20:05 to 20:36 | Yes, before the overnight leg | Loud, moved nothing at index scope | Coincidence, published (the second column) |
| Consumer confidence 91.7 against 81 forecast | 1 | Tue 14:00 | Unclear, 30 minutes after the open | Unverified | Desk Notes only: the TradingView record carries a blank source field and a 10.7 point beat; not verified at conference-board.org; no index intraday path held |
| Durable goods +1.8% against 1.5% | 1 | Tue 12:30 | Gap only | No | Desk Notes only |
| SK Hynix record quarter, Asian AI session | 3 | Wed 05:27 (DJN wrap) | NOT ESTABLISHED | n/a | Desk Notes only: overnight move inside the normal band, nothing to explain |
| Overnight crude re-firming to 102.13 | 3 | Wed 00:22 (DJN), 02:32 (TE) | NOT ESTABLISHED, no path before the stamps | Unknown | Refusal, published: Gulf supply-risk wires not named as a cause |
| 07:55Z futures volume spike | 6 | Wed 07:55 | Post-capture | n/a | Desk Notes only |
| RBNZ surprise hold at 2.75% | 3 | Wed 01:00 | n/a | No US transmission | Desk Notes only |
Causes without effects, the second column: four after-hours names down 5% to 16% and Nasdaq futures up 0.38%; the Nvidia-Meta headline and Meta down a second day; a hold heavily favoured on the relay and both volatility indices down more than 4%.
Null rate per ruling S: fifth consecutive edition naming no index-scope cause. Two scoped causes named (Boeing, SoFi), both pre-market releases with the stock’s own bar behind them.
Mechanism read (§8), full
The front end. 2-year CMT 4.70%, up 2 basis points; 1-year 4.50%, up 3; 3-year 4.80%, up 1. The long end: 5-year 4.82%, down 2; 10-year 4.99%, down 1; 20-year 5.34%, down 1; 30-year 5.30%, down 1. 2s10s 29 from 32; 2s30s 60 from 63; 20s30s -4 unchanged (30-year minus 20-year); 3m10y 77 from 78. Three tenors rose, eight fell, three held. The 20-year is the strict maximum of all fourteen tenors for a 33rd consecutive session (10 Sep to 27 Oct; 9 Sep was a 5.28 tie with the 30-year); the full 20y-less-30y series is in the lock. First CMT fetch was not stale; two cache-busted fetches agreed; header asserted at fifteen fields.
| Tenor | 27 Oct | 26 Oct | bp |
|---|---|---|---|
| 1 Mo | 4.10 | 4.11 | -1 |
| 1.5 Mo | 4.11 | 4.13 | -2 |
| 2 Mo | 4.18 | 4.18 | 0 |
| 3 Mo | 4.22 | 4.22 | 0 |
| 4 Mo | 4.31 | 4.32 | -1 |
| 6 Mo | 4.34 | 4.35 | -1 |
| 1 Yr | 4.50 | 4.47 | +3 |
| 2 Yr | 4.70 | 4.68 | +2 |
| 3 Yr | 4.80 | 4.79 | +1 |
| 5 Yr | 4.82 | 4.84 | -2 |
| 7 Yr | 4.91 | 4.91 | 0 |
| 10 Yr | 4.99 | 5.00 | -1 |
| 20 Yr | 5.34 | 5.35 | -1 |
| 30 Yr | 5.30 | 5.31 | -1 |
The dollar: DXY 102.365, +0.329%; euro 1.112, -0.442%; dollar-yen 157.948, +0.285%; sterling -0.274%; dollar-franc +0.175%. Volatility: VIX 17.52 (-4.731%), range 17.43 to 18.55 over the global-hours bar; VIX3M 19.57; ratio 0.895 from 0.922, contango; MOVE 97.884 (-4.224%), range 97.869 to 100.40. MOVE and VIX are both below every close since 21 Oct (95.949 and 16.68); neither is a longer superlative, and the dated windows are in the lock. Credit: HYG +0.5181%, LQD +0.269%, TLT -0.061% on carried durations 3.17, 7.63, 14.96; with duration held, high yield rising while long Treasuries slipped reads as spread tightening. FRED HY OAS 330 basis points on 26 Oct from 338 (the 27 Oct observation posts this afternoon); IG 90 from 91. The route conflict with the ledger’s 297.81 for 22 Oct, against FRED’s 338 for 23 Oct and 330 for 26 Oct from this route, stands UNVERIFIED; FRED’s series title is quoted verbatim in the lock.
Causal read, stated as what it is. No scheduled release, Fed communication or headline passes the clock at index scope. The cross-asset picture is coherent without a cause: implied volatility down in both markets, the front end up 2 and the back end down 1 into a meeting priced for a hold, credit tighter than duration, equities led by one sector. What is different this morning: a market that has paid less for the right to be wrong about today’s statement than it did on Monday, and a barrel that gave back its whole settlement fall overnight.
The one artery: the pair of volatility indices, MOVE 97.88 and VIX 17.52, both down more than 4% on FOMC eve. Crowned in the letter; everything else enumerated here.
Enumeration of locked single-name moves (R8)
NVDA 217.94 +0.898% (0.93x volume); MSFT 531.33 -0.238% (1.03x); GOOGL 320.58 +1.193% (1.19x); AMZN 253.10 +1.610%; META 620.19 -1.645% (1.66x); AAPL 347.10 +0.928%; TSLA 407.46 +4.045% (0.85x); AVGO 342.33 +3.998% (1.37x); AMD 560.26 +5.455% (1.23x); MU 928.76 +2.773%; LRCX 240.85 +1.411%; LKQ 17.10 -0.870%; T 20.94 +0.432%; TMUS 146.83 -0.068%; AXP 312.91 -0.679%; SOFI 16.40 +13.416% (3.72x); UPS 106.09 +5.752% (1.69x); RCL 295.92 +5.460% (2.07x); BA 168.18 -10.690% (6.09x); PYPL 56.09 +2.000% (1.58x); SHW 326.01 -2.730% (1.96x, no report confirmed); NUE 270.79 +5.222% (report time unconfirmed); GM 80.54 +5.543%; XYL 92.86 -14.209% (3.52x); PNR 62.29 +12.803% (2.12x). Wire superlatives offered without windows and NOT published: “Boeing worst day since 2020”, “SoFi best day in 18 months”.
Sectors (SPDR proxies, tier 2): XLK +1.7014, XLY +1.042, XLB +0.778, XLU +0.705, XLI +0.575, XLV -0.056, XLF -0.250, XLC -0.260, XLRE -0.841, XLP -0.921, XLE -2.053. Five up, six down. SOXX +3.910%, SMH +3.021%, divergence 0.889 points (Part 233 session 5 of 10, not a falsifier session).
Breadth (tier 2): NYSE 1,570 up, 1,127 down; up volume 692.4m, down volume 601.3m, total 1,302.3m; residual +0.661%; down-volume share 46.17% on an up day (Monday 55.29% on an up day; the series for the declined shot now reads 61.63% down day, 55.29% up day, 46.17% up day); new highs 35, new lows 32. Nasdaq 3,172 up, 1,716 down; highs 50, lows 84.
Capture-to-publish re-quote (§11.9.1), both limbs, pre-draft pass 08:38Z to 08:46Z
Every movable locked figure was re-quoted; drift gate 21 checked, zero over 2%, zero movable figures missing. Limb one, price: ES 7,762.75 (+0.058% on settle), NQ 29,938.50 (+0.424%), YM 52,436 (-0.272%), RTY 2,825.50 (-0.106%); December WTI 101.46 (+1.562%, having been 102.13 or +2.232% on the 07:40Z bar), January WTI 99.65 (+1.621%); December Brent 115.13 (+1.098%), January Brent 110.87 (+1.334%), ICE feed 10 to 15 minutes behind; December gold 4,063.50 (-0.272%), spot gold 4,050.12 (-0.230%), December silver 54.035 (-0.877%), December copper 6.646 (-0.090%); VIX 17.52 on the 08:20Z bar (0.000%); bitcoin 81,550.16 (+0.957% on the mark), ether 2,377.29 (+1.309%); DXY 102.382, dollar-yen 157.759.
Limb two, distance to every threshold, both directions. §8.5 on NQ: +0.424%, 0.176 points inside the 0.6% ceiling and 0.576 short of the 1.0% trigger; the capture read was 0.219 inside the ceiling, so the clearance narrowed by 0.043 points. ES +0.058%, below the band floor. §8.4.1 commodity leg on the re-quote: WTI +1.56% on settle, 2.44 short of 4%; at 07:40Z it had been +2.23%, 1.77 short, so crude crossed back towards the threshold and then retreated; neither read fires. Volatility leg: VIX unchanged on the 08:20Z bar, 8.00 short. Prior-session ES +0.567%, 0.433 short of the 1.0% band, unchanged by definition. No threshold crossed in either direction between capture and re-quote.
Pre-delivery re-quote (§11.9.1), second pass 09:28Z to 09:36Z
Drift gate re-run with a fresh live.json: 21 checked, TWO over the 2% threshold, both crude. December WTI 101.90 on the 09:25Z bar, +2.002% on the 99.90 settle; January WTI 100.06, +2.040% on 98.06. Requalified in every reader file: the settle, the 07:40Z, 08:35Z and 09:25Z reads are all carried. Limb two: WTI +2.00% against the 4% commodity leg, 2.00 short, having been 1.77 short at 07:40Z and 2.44 short at 08:35Z; no crossing in either direction. Everything else: ES 7,765.25 (+0.090%), NQ 29,923.75 (+0.375%, 0.225 inside the 0.6% ceiling, 0.625 short of the 1.0% trigger), YM 52,477 (-0.194%), RTY 2,825.30 (-0.113%); Brent Dec 115.22 (+1.177%), Jan 111.01 (+1.462%); December gold 4,064.80 (-0.241%), spot 4,051.42 (-0.198%), silver 53.98 (-0.978%), copper 6.639 (-0.203%); VIX 17.55 (+0.171%); bitcoin 81,368.32 (+0.732%), ether 2,363.14 (+0.706%); DXY 102.395; dollar-yen 157.81. No §8.4.1 or §8.5 threshold crossed.
Divergence flags
- Both volatility indices fell more than 4% into the FOMC. Textbook expectation runs the other way. The spine.
- Six of eleven sector proxies fell on a day the S&P 500 rose 0.60% and the Nasdaq 100 1.29%. Narrow advance; count on the proxies, not the index.
- Boeing -10.69% and the Dow +15.99 points. No divisor held; nothing attributed.
- December WTI -1.83% at the settle and +2.23% off it by 07:40Z; the energy proxy -2.05%. Sector-against-barrel sign series: opposite, same, opposite, SAME (fourth observation of five).
- After-hours names down 5% to 16% and Nasdaq futures up 0.38%.
- DJN wire 2-year 4.731% (TheStreet 15:47 ET) against the CMT 4.70%: different measurements, recorded, not reconciled.
- HY OAS route conflict: FRED 338 (23 Oct) and 330 (26 Oct) against the ledger’s 297.81 (22 Oct, other route), roughly 40 basis points apart on adjacent dates. UNVERIFIED, second edition.
- Treasury auction feed: no 26 Oct 2-year and no 27 Oct 5-year record; calendar relay high yields 4.708% and 4.845%; fiscaldata also carries an oddly dated “5-Year Note” row for 22 Oct with null results. No cover or share published.
- Farside bitcoin 26 Oct row is IBIT-only with eleven printed zeros; carried as complete, watched for revision. The ether page served a launch-era fragment on six reads: route failure, not a session.
- Consumer confidence 91.7 against 81 on a record with a blank source field. Not published outward.
Carry-over note (§10.6)
Does not fire. No §8.4.1 threshold tripped and no manual flag.
Forward catalyst slate
Today: UK Budget 12:30Z; US advance goods trade and inventories 12:30Z; Bank of Canada 13:45Z (a hike the consensus on the calendar route), presser 14:30Z; EIA inventories 14:30Z (API showed a 2.031 million barrel crude draw); 17-week bill 15:30Z; FOMC statement 18:00Z, press conference 18:30Z; Microsoft, Alphabet after the close (two routes each); Meta weakly listed after the close on one aggregator; Caterpillar before the open. Thursday: Q3 GDP advance and September PCE 12:30Z; initial claims; ECB 13:15Z; 4- and 8-week bills 15:30Z; 7-year auction 17:00Z; Amazon after the close; Strategy results. Friday 03:00Z: Bank of Japan on the TradingView calendar, not Thursday; December Brent expires. Not this week: the Bank of Japan on Thursday, which one brief placed there in error.
Regime and sensitivity read (§17.3)
Weathervane carried unchanged. Turn condition progress 0 of 2; no dated Fed communication exists until 18:00Z today, so the first test in fourteen days is this afternoon. Candidate 8 (volatility term structure) is scoreable and does not fire: ratio 0.8952 from 0.922, change -0.027 against a 0.070 condition, below 1.000. Candidate 9 scoreable and does not fire: gap shares 35.39% (NDX) and 49.53% (SPX), both below 80%; both exchanges’ advance-decline ratios above 1.000. Sensitivity running LOOSE, forty-ninth consecutive edition, stated openly: no candidate reads implied volatility against a scheduled event, which is today’s spine, and four of nine candidates still carry no numeric condition. Diagnosis stays specification.
Retrieval and route notes
Twelve Data connector absent; TradingView substitutes used throughout. CBOE:VIX 5-minute global-hours bars exist and are about 15 minutes delayed and revised between reads; the 07:45Z bar was not served at 07:51Z and was served at 08:16Z. ForexFactory returned client_error on both URL forms; the TradingView economic calendar carried names, times and actuals. Fiscaldata carries no 26 or 27 Oct auction record. Farside /eth/ served a launch-era fragment on six attempts, including the all-data path. Stocktwits all-asset board returned a payload identical to the equities board; treated as not captured. TradingView 1-hour equity bar volumes do not reconcile to daily volumes; prices used, volumes discarded. TradingView news carries no feed for FI, EA or KHC. Yahoo earnings calendar served a stale 1 Oct page. Zero 429s across four lanes, the re-quote agent and the main thread; two-call batches throughout. Capture read on time on all four contracts for a sixth consecutive edition. Step Zero again ran after the lanes returned because the dispatch call blocked the main thread, third consecutive edition.