A 4.61% 2-year, its lowest October close, on a 2.1% quarterly inflation print, 12 of 14 tenors down and bond fear at a 5-week low
⚓ Weathervane. The wind is coming from the long end. The policy rate has been frozen for most of the year whilst the term premium does the tightening, and the price of long money is set by deficits, issuance supply and a synchronised global duration bid rather than by the committee. Higher-for-longer stopped being a Fed decision and became a bond-market fact. The cruise ship is holding this heading.
 Ahoy there, Trader! ⚓️
It’s Phil…
Why did the 2-year fall 6 basis points on the day the Nasdaq 100 fell 1.4% after earnings?
Thursday’s bond rally has two candidate buyers, and they keep different hours. The first is the stock market’s bad night: Alphabet reported at 20:02 UTC on Wednesday, ServiceNow and Fortinet that evening, and by Thursday’s close the three were down between 12.64% and 26.95% and the Nasdaq 100 1.38%, while 9 of 11 sector proxies rose. The textbook calls that a flight to safety. The second is the 12:30 UTC release: September PCE 3.6% on the year, core 3.1%, in line with the wires, and the quarter’s PCE price index 2.1% annualised from 5.0%. The textbook calls that a softer inflation path.
The clock separates them, partly. From the first bar this book holds, the 2-year rose from 4.70% at 11:00 UTC to 4.73% at 12:15 UTC with all three results public; in the hours held, the equity news was not buying bonds. The yield fell 3.3 basis points in the release bar, 4.73% to 4.69%. It fell again, 4.68% to 4.66%, in the bar the Nasdaq opened 1.3% lower, and that leg the clock cannot assign: the release and the equity gap share fifteen minutes. The 2-year closed 4.61%, its lowest close of October.
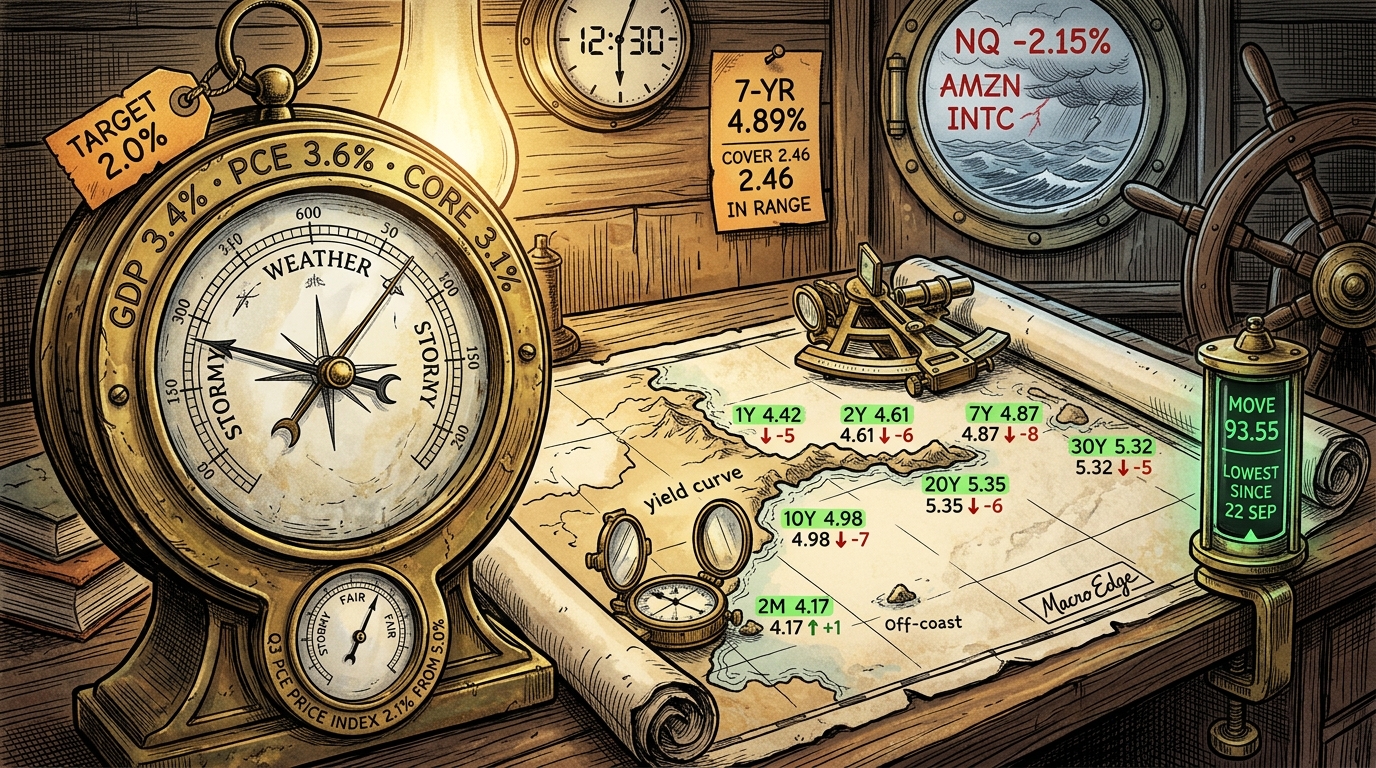
The shape adds a clue. It was not a front-end move alone: the 1-year fell 5, the 2-year 6, the 7-year 8, the 10-year 7, the 30-year 5, a near-parallel rally, on a day the 7-year auction cleared inside its trailing six. A policy re-read leans on the front; a duration bid lifts the lot. We hold no positioning data to say whose bid it was. Equity insurance rose, the VIX up 1.71%; bond insurance fell, the MOVE to 93.55, its lowest since 22 September. Neither settles who bought.
So the honest split: the release bar is the release’s, and it took back the morning’s rise; the open bar is shared; the afternoon’s drift is unassigned, and its largest step is flagged as a possible feed artefact. Nasdaq futures were 2.15% lower again at the capture after Amazon, Intel and Reddit.
What settles it is on the calendar. If the 2-year falls before today’s 12:30 UTC employment cost index, with Nasdaq futures lower and no data yet out, the equity tape is among its buyers. If it waits for the index and moves only on that, the release reading gains. We will know by next Friday evening.
Phil’s Musing
My instinct is that Thursday was the quarter, not the carnage, because the 2-year rose from 11:00 UTC into the release with the results already out. If it rallies this morning before the employment cost index, I am wrong about who was buying.
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
P.S. – Phils Footnote I assumed, when I opened the GDP page, that the morning’s question would be how far the 2-year rose. I had read the headline and not the table beneath it, which is the sort of thing this letter exists to admit. The textbook was right. I was on the wrong chapter.
🗂 Desk Notes – Part 240 | 30 Oct 2026
Raw briefing. Observations, not trades. Marks are against the full Thursday 29 Oct 2026 reaction, cash session plus the after-hours and overnight tail to the 07:45 UTC capture, with the 08:15 UTC and 09:00 UTC re-quotes carried alongside. Settlement figures for the four index contracts are the TradingView daily-bar closes, which the feed marks at the 20:00 UTC window; the 20:00 to 21:00 UTC bar is carried separately as the post-close hour.
Reading taken at the top of the run, stated once. Section 8.5 fired at spine-candidate strength (Nasdaq futures 2.15% under the settle at the capture, 2.25% at the re-quote). The edition as first delivered declined it as spine because every stamp behind it precedes the 22:00 UTC reopen, and ran the rates pair instead (the 2-year -6bp against September PCE 3.6% y/y and the quarterly PCE price index 2.1%). Recut at Phil’s direction after delivery: the spine is now the earnings pair across two nights. December NQ sits 3.517% under Wednesday’s 29,979.5 settle at the capture (ES 1.355% under 7,783.25), against six results-driven falls over 7%: Alphabet (20:02 UTC Wed), ServiceNow and Fortinet (Wednesday after the close, earliest carrier held 01:59:54 UTC Thursday, Stocktwits, tier 3) on Thursday’s cash bars, and Amazon, Intel, Reddit (20:01 to 20:07 UTC Thu) on wire after-hours marks. Relationship: both index legs landed at the open or overnight, after the stamps, while the cash session added 4.55% of the Nasdaq 100’s fall and 9 of 11 sector proxies rose. Each result is published as a cause scoped to its own name; no index weights are held, so no share of either index fall is weighed. Marvell (-13.24%) is a reported Lumentum deal (MarketWatch 00:20 UTC Thursday), not results, and is outside the count. The rates pair is retained as Macro Edge’s spine under the bridging question; the new Macro read adds that the 2-year rose from 4.695 at 11:00 UTC to 4.726 at 12:15 UTC with the three Wednesday results public, fell 3.3bp in the release bar and a further 2.5bp in the 13:30 UTC equity-open bar, which the clock cannot assign.
Session read (§8.4)
SESSION BRIDGE: prior session (Thu) full reaction [December ES 7,754.25 at settlement, -0.373% on Wednesday’s 7,783.25; December NQ 29,562, -1.393%; S&P 500 cash -0.305%, Nasdaq 100 cash -1.377%, Russell 2000 +1.014%; post-close hour NQ -1.163%, ES -0.571%; reopen 22:00 UTC NQ -1.29%, ES -0.58%; overnight low NQ 28,821.50 (-2.50%) and ES 7,665.25 (-1.15%) in the 01:00 to 02:00 UTC bar]; live premarket ES -0.987% / NQ -2.154% on the 07:45 to 07:50 UTC bar (YM -0.067%, RTY -0.443%), re-quoted 08:15 UTC ES -1.041% / NQ -2.246% and 09:00 UTC ES -0.845% / NQ -1.977%; VIX prior cash close 17.20 (+1.71%), global-hours bar 18.55 at 08:10 UTC (+7.85%, feed about fifteen minutes delayed); threshold: soft.
Threshold reasoning. Equity leg: the prior December ES settlement move of -0.37% is inside the normal envelope, none. Premarket leg: ES -0.99% at the capture is outside the 0.6% band and fires the soft trigger on its own leg with the catalyst named (three post-close reporters); at the 08:15 UTC re-quote ES is -1.04%, which crosses the 1.0% section 8.5 trigger it sat 0.013 points short of at the capture. Volatility leg: VIX +1.71% on the day, no; the global-hours re-quote is +7.85%, 0.15 points short of the ±8% leg. Commodity leg: December WTI -0.76%, no; re-quote +1.50%, 2.50 points short of 4%. Section 8.5: NQ -2.15% at the capture and -2.25% at the re-quote, over the 2.0% spine-candidate line by 0.15 and 0.25 points; leads the block.
Section 8.4.2 limbs. (a) The Nasdaq 100’s -1.377% ranks 5th of 25 absolute daily moves in the held window (Composite 4th, S&P 17th, Dow 17th, Russell 7th): not largest or second-largest, does not trip. (b) Sector spread 4.275 points: trips. (c) ServiceNow -26.95%, Fortinet -20.09%, Marvell -13.24%, Alphabet -12.64% are table-adjacent constituents over 10%: trips. The board and the decomposition were mandatory and were run.
Capture protocol. The 07:45 UTC 5-minute bar was read at 08:05:05 and 08:06:05 UTC (ES, NQ; YM, RTY) and again at 08:10:20 and 08:11:24 UTC, byte-identical on open, high, low, close and volume on all four December contracts; the forming 08:05 UTC bar mutated on all four, the control. Zero 429s across four lanes, the re-quote agent and the main thread. Eighth consecutive on-time four-contract capture. UK is on GMT, so 07:45 UK is 07:45 UTC and 03:45 EDT; from Sunday 1 November the US goes to EST and ET becomes UTC minus five.
Contract roll. No roll this week. December Brent (ICEEUR:BRNZ2026) has its last trading day today; January (BRNF2027) was the front by volume on Thursday at 430,603 lots against 120,323, and December’s expiry-day bars are thin on the re-quote. December WTI remains the front at 248,405 lots against January’s 105,946.
The mechanism read (full)
What moved. Twelve of fourteen tenors fell on the day. One tenor rose, twelve fell, one held, recomputed in code over all fourteen.
| Tenor | 28 Oct | 29 Oct | bp |
|---|---|---|---|
| 1 Mo | 4.07 | 4.06 | -1 |
| 1.5 Mo | 4.10 | 4.08 | -2 |
| 2 Mo | 4.16 | 4.17 | +1 |
| 3 Mo | 4.18 | 4.18 | 0 |
| 4 Mo | 4.22 | 4.21 | -1 |
| 6 Mo | 4.32 | 4.28 | -4 |
| 1 Yr | 4.47 | 4.42 | -5 |
| 2 Yr | 4.67 | 4.61 | -6 |
| 3 Yr | 4.80 | 4.73 | -7 |
| 5 Yr | 4.85 | 4.78 | -7 |
| 7 Yr | 4.95 | 4.87 | -8 |
| 10 Yr | 5.05 | 4.98 | -7 |
| 20 Yr | 5.41 | 5.35 | -6 |
| 30 Yr | 5.37 | 5.32 | -5 |
Spreads: 2s10s 37bp from 38; 2s30s 71 from 70; 3m10y 80 from 87; 20s30s -3 from -4. The 20-year holds the strict maximum of all fourteen tenors for a 35th consecutive session, 10 September to 29 October, window in the lock (9 September was a 5.28 tie with the 30-year). The 2-year’s 4.61 is its lowest close of October, window 1 to 29 October in the lock; the lane asserted “lowest since 10 September” and the lock holds no September closes for the 2-year, so the claim is narrowed to the window held. The 10-, 20- and 30-year are not October lows (22 October: 4.96, 5.32, 5.29). CMT: fetch one stale as presumed (top row 26 October), fetches two and three both top row 29 October and byte-identical; header asserted at 15 fields and 14 tenors; the 28 October ledger values reproduce exactly; H.15 carries 22 to 28 October and matches 55 of 55 cells. EFFR 3.88.
Shape, TradingView yields, never mixed with CMT magnitudes. US02Y peaked in the 12:15 UTC bar at 4.726, closed the 12:30 UTC release bar at 4.693, 4.658 at 13:30 UTC, drifted to 4.639 by 14:30 UTC, sat 4.666 to 4.671 through the 17:00 UTC auction bar, and stepped from 4.646 to 4.606 in the 20:00 UTC bar, the single largest step of the day, after the equity close; last 4.602. US10Y 5.028 at 12:15 UTC, 5.007 at 12:30 UTC, 4.974 at 13:30 UTC, about 5.00 through the auction, 4.945 at 20:00 UTC, 4.937 last. US30Y 5.354, 5.335, 5.311, 5.339 at 17:00 UTC, 5.297 last. The dollar (TVC:DXY, 15m) printed 102.16 in the 12:30 UTC bar, spiked to 102.45 in the 13:15 UTC bar, slid to 101.96 by 15:00 UTC and closed 101.853, -0.29%.
The data. BEA 12:30 UTC: Q3 GDP advance +3.4% annualised; PCE price index Q3 2.1%, core 2.5%; gross domestic purchases prices 3.0%; real final sales to private domestic purchasers 4.9%; current-dollar GDP 5.6%. The GDP price index of 2.2% is a TradingView-only field, single-sourced, not published. September personal income and outlays, same stamp: PCE prices +0.5% m/m, +3.6% y/y; core +0.3% m/m, +3.1% y/y; income +0.2%, spending +0.5%, real PCE 0.0%, saving rate 3.8%. Initial claims for the week of 24 October 194,000 (prior revised 195,000; four-week average 196,750; continuing 1,701,000). Every actual present on both routes agreed between the BEA page and the TradingView calendar (core PCE y/y has no TradingView row; the GDP price index has no BEA line); ForexFactory returned a client error on the one URL tried, a third consecutive edition of failure, so no forecast or previous is published. The TradingView calendar’s forecasts (GDP 3.2, PCE y/y 3.6 per a Mace flash) are single-route and not published as point figures; the year-on-year print was in line with that expectation on the wire’s own account.
The auction. 7-year, $44bn, high yield 4.894% (prior 5.085%), cover 2.46 (prior 2.42; trailing six 2.51, 2.52, 2.50, 2.49, 2.50, 2.42, mean 2.49), indirects 57.8% (prior 57.2%), all on a Dow Jones wire via Marketscreener at tier 2; direct 32.8% and dealer 9.4% from a tier-3 aggregator only. Fiscaldata carries no record for 26, 27, 28 or 29 October; the 2-year and 5-year records are still absent. No when-issued level is available on any route; no tail is computed. Read against its own run: cover inside the trailing six, indirects a touch above the prior, high yield 19bp under last month’s; a mid-run auction and nothing more.
Volatility. VIX 17.20 (+1.71%); VIX3M 19.37 (from 19.22); ratio 0.888 from 0.880, contango. MOVE 93.549 from 94.550, -1.06%, the lowest close of the 75-bar window held and the lowest since 22 September (78.56), window in the lock. Bond vol fell on the day the whole curve rallied; equity vol rose on the day the Nasdaq gapped. VIX global-hours series from 07:15 UTC confirmed for a third consecutive edition (07:15 UTC bar 18.42, 08:10 UTC bar 18.55, feed about fifteen minutes delayed); the registry’s “permanent absence” entry remains wrong and unrewritten.
Credit, duration-aware, seventh edition. HYG -0.013%, LQD +0.144%, TLT +0.617% on durations 3.17, 7.63, 14.96 against a 7bp fall in the 10-year (5bp in the 30-year). TLT’s duration implies roughly +0.75% to +1.05% on those moves; it rose 0.62%. LQD’s implies about +0.5%; it rose 0.14%. HYG’s implies about +0.2%; it was flat. All three captured less than their durations owe. The ETFs close at 20:00 UTC and the TradingView yield path shows a further step lower in the 20:00 UTC bar, so whether the shortfall is spread or the timing of the funds’ close against the rates path is not resolved; neither reading is published. The HY OAS level stays UNVERIFIED (clock 4 of 5; the side-by-side read of the two routes was not run this edition).
Equities. S&P 500 7,720.39, -0.305% (-23.59); Nasdaq 100 29,402.508, -1.377% (-410.65); Composite 26,184.724, -1.375%; Dow 52,342.56, -0.253% (-132.54); Russell 2000 2,859.217, +1.014% (closes only on TVC:RUT). Gap-versus-intraday, from the 13:30 UTC open: Nasdaq 100 gap -391.98 (95.45%), intraday -18.67 (4.55%); S&P gap -44.37, intraday +20.78 (shares 188.09% and -88.09%); Dow gap -388.97, intraday +256.43 (293.47% and -193.47%). S&P cash-session high 7,732.21 in the 15:30 UTC bar, low 7,690.94 in the 17:45 UTC bar; Nasdaq 100 high 29,517.80 at 15:30 UTC, low 29,257.05 in the opening bar. Sectors on the SPDR proxies, tier 2: XLV +2.4037, XLRE +2.208, XLP +1.543, XLU +1.530, XLF +1.443, XLB +1.292, XLI +0.973, XLY +0.754, XLE +0.380, XLK -1.183, XLC -1.871; spread 4.275; 9 up, 2 down. Breadth: NYSE 1,873 advancers to 801 decliners (2.338), up-volume share 69.643%, residual +1.022% (28 October +0.949%); Nasdaq 2,379 to 2,539 (0.937). Semiconductors: SOXX -1.5481%, SMH -1.057%, divergence 0.491.
Basis, by index name. es_spx_basis 33.86 (7,754.25 less 7,720.39); nq_ndx_basis 159.49; ym_dji_basis 169.44; rty_rut_basis 8.08. No implied open is published.
Causal read. Rates: the 12:30 UTC release precedes the fall; the year-on-year PCE was in line with expectation and the quarterly PCE price index decelerated to 2.1% from 5.0%, which carries the fall’s sign; the release is published as the cause, class 1, scoped to the front end, share unweighed. The auction bar moved the 2-year half a basis point. The TradingView path’s 20:00 UTC step holds the 20:01 UTC results flashes, sits after the Treasury’s afternoon mark, and the lane flags it as a possible feed close-mark effect; it is not a candidate for the CMT move and is recorded as shape only. Equities: the Nasdaq 100’s 95.45% gap is consistent with Alphabet’s 20:02 UTC Wednesday stamp, scoped to GOOGL (-12.64%); the index share cannot be weighed, no index weights held. The cash session’s 4.55% is not attributed. Overnight: Amazon, Intel and Reddit (20:01 to 20:07 UTC) precede the 22:00 UTC reopen and every locked read; the majority test passes at 100% by construction; share unweighed. Crypto: the Binance transfer (20:24 UTC) precedes bitcoin’s fall, scoped to bitcoin.
The refusal, in its required form. Routes checked: Dow Jones wires via the TradingView feed, the BEA release, the fiscaldata auction API, the Board’s 2026 speeches page (two cache-busted reads, nothing after 14 October), the Trading Economics and Seeking Alpha wraps, Stocktwits narratives. Stamps found: 12:30 UTC prints; 12:31 UTC Mace data flash (PCE 3.6% against 3.6% expected); 13:39 UTC Zacks read of the print as benign; 17:00 UTC auction; 17:01 UTC Seeking Alpha wrap carrying “December hike talk” whilst reporting yields lower. Test run against the locked reads: the 2-year’s path (12:15 UTC peak 4.726, 12:30 UTC 4.693, 13:30 UTC 4.658, 19:45 UTC 4.646) had made most of its fall by 13:30 UTC; the release precedes it and the quarterly components carry its sign; the hike wrap post-dates it by four and a half hours; the auction bar is flat. Result: the release is published as the cause with the share unweighed; the hike narrative is published as a coincidence; the auction as a refusal.
Section 8.3 candidate board (both columns)
| Candidate | Class | Stamp (UTC) | Precedes majority | Large enough | Disposition |
|---|---|---|---|---|---|
| Alphabet results (Wed) | 2 | 28 Oct 20:02 | yes, whole Thu gap | scoped to GOOGL; index share unweighed | published cause (spine) |
| ServiceNow and Fortinet results (Wed after the close) | 2 | 29 Oct 01:59 (earliest carrier held, tier 3) | yes, before the Thu open | scoped to NOW and FTNT; index share unweighed | published cause (spine) |
| Marvell: reported Lumentum talks | 2 | 29 Oct 00:20 (MarketWatch) | yes, before the Thu open | scoped to MRVL; a deal, not results | published cause (stock), outside the earnings count |
| Q3 GDP and September PCE, with the quarterly PCE price index at 2.1% | 1 | 29 Oct 12:30 | yes (precede the 2-year fall) | sign matches on the quarterly components; share unweighed | published cause (rates) |
| The 20:00 UTC rates-path step against the 20:01 UTC results flashes | 2 | 29 Oct 20:01 | no (after the CMT mark; minority of the path) | possible feed close-mark effect | refusal, shape only |
| 7-year auction | 1 | 29 Oct 17:00 | no (largest step at 20:00) | half a basis point in its bar | refusal |
| December hike narrative | 3 | 29 Oct 17:01 | no (four and a half hours after the fall began) | describes the opposite tape | coincidence |
| Rotation into non-AI names | 4 | 29 Oct 14:04 | no | narrative; breadth measurable, motive not | coincidence |
| Amazon results | 2 | 29 Oct 20:01 | yes (before the 22:00 reopen) | scoped; unweighed | published cause (overnight) |
| Intel results and Q4 guide | 2 | 29 Oct 20:01 | yes | scoped; unweighed | published cause (overnight) |
| Reddit results and guide | 2 | 29 Oct 20:07 | yes | scoped to the stock | published cause (overnight) |
| Binance breach | 3 | 29 Oct 20:24 (first transfer) | yes, for bitcoin | scoped to bitcoin; size unmeasurable | published cause (bitcoin) |
| Tokyo and Seoul selling | 3 | 30 Oct 05:22 (wrap; the opens are 00:00 UTC) | not established (the NQ low printed during the Asian morning; no stamp before it is held) | n/a | coincidence, not attributed either way |
| Bank of Japan hold, faster ETF selling | 3 | 30 Oct 03:03 | no (after the NQ low) | n/a | desk notes only: no US transmission established |
| Hormuz tanker and strike-options reports | 3 | 30 Oct 05:49 (earliest retrievable) | no (barrel spiked 01:30) | n/a | refusal: chain not established |
| ECB hold | 3 | 29 Oct 13:15 | no | moved nothing measurable in US rates | desk notes only |
| Vance outreach to Tehran | 3 | 29 Oct 07:02 | yes for the Thursday barrel low | barrel then rallied 3.21 to its high with no stamp | desk notes only |
Effects without causes: the 20:00 UTC rates-path step; the WTI overnight spike to 104.99 at 01:45 UTC; the NQ deepening from -1.53% at 00:00 UTC to -2.50% by 02:00 UTC; silver -2.40% and copper -1.03% on a weaker dollar and lower yields, unaddressed. Causes without effects: the hike narrative (17:01 UTC) against a 2-year already lower; the ECB’s hold; the 7-year auction, which moved the 2-year half a basis point. Null rate under ruling S: one class-1 cause on the rates spine (the release, sign-matched and unweighed), one stock-scope cause (Alphabet, Thursday gap), and the overnight causes (trivial by construction). Seventh edition of the series: index-scope causes found only on overnight legs where the stamp precedes the reopen.
R8 enumeration: every locked single-name move above 3%, with disposition
| Name | 29 Oct move | Where it went |
|---|---|---|
| ServiceNow | -26.95% | spine: headline, cold-open, read block, TL;DR |
| Fortinet | -20.09% | spine: cold-open, read block, TL;DR |
| Marvell | -13.24% | cold-open and read block, named as a deal and outside the earnings count |
| Alphabet | -12.64% | letter, published cause for the Thursday gap |
| Amazon (cash) | -4.25% | read block (closed lower before it reported); the after-hours leg is the spine |
| Microsoft | -0.16% | letter, as the ruling-U miss |
| Meta | +1.96% | read block |
| Apple | +1.48% | read block |
| Strategy | -2.44% | excluded below the 3% floor; in the crypto table as a reporter |
After-hours relays (tier 3, no exchange bars): Intel -23.03%, Reddit -18.21%, Amazon -8.7% to -6% to -7.3% (three stamps, conflict carried), Rivian +5.59%, Sandisk -3.84% (direction reversed from a 20:16 UTC “perks up”), Starbucks -3%, Coinbase +1.2%, Strategy “slips” then “more than 6%” on a Stocktwits relay that attributes most of it to the Binance event.
Overnight Excitement (§8.5)
Fires at spine-candidate strength: December NQ -2.154% at the capture, -2.246% at 08:15 UTC, -1.977% at 09:00 UTC (back under the 2.0% line by 0.023 points, still over the 1.5% lead line); ES -0.987%, -1.041% and -0.845% (crossed the 1.0% line on the 08:15 UTC read and back under it by 09:00 UTC). Hourly closes against the settle, NQ: 23:00 UTC -1.72, 00:00 -1.53, 01:00 -2.05, 02:00 -2.36 (low 28,821.50, -2.50%), 03:00 -2.20, 04:00 -2.05, 05:00 -1.87, 06:00 -1.97, 07:00 -1.91, 07:45 -2.15, 08:15 -2.25. ES: 23:00 -0.71, 00:00 -0.62, 01:00 -0.82, 02:00 -1.06 (low 7,665.25, -1.15%), 03:00 -1.00, 04:00 -0.94, 05:00 -0.89, 06:00 -0.91, 07:00 -0.86, 07:45 -0.99, 08:15 -1.04. The majority test clock: half of the capture move (1.077 points) was first exceeded in the 20:00 to 21:00 UTC post-close bar (-1.16%), and on the locked hourly reads at 23:00 UTC; every published cause is stamped before 21:00 UTC. Foreign colour, direction only with attribution: Nikkei down, Kospi down sharply with a brief halt after futures fell 5%, Hang Seng up, Shanghai down, Taiex down, ASX up (Dow Jones and Seeking Alpha relays 05:22 to 05:49 UTC; the two disagree on Seoul’s magnitude). Japan open confirmed (TSE:7203 carries a 30 October bar). Bank of Japan held at 1.25%, 8-1 (Takata for 1.50%), ETF selling raised to 0.1% of trading value from 0.05% (Mace News 03:03 UTC). ECB held on Thursday (13:15 UTC); Lagarde said the council debated a hike and will step down early on 7 February 2027 (10:38 UTC). Europe’s open was not captured.
Commodities, crypto and flows
December WTI 102.00 (-0.759%), January 100.14 (-0.842%), December less January 1.86 from 1.79; trade-date high 103.00 in the 20:15 UTC bar, low 99.79 in the 13:45 UTC bar; reopen 102.80 at 22:00 UTC; overnight high 104.99 in the 01:45 UTC bar, low 102.43 at 01:00 UTC; re-quote 103.53 at 08:20 UTC (+1.50%). Brent December 114.88 (-0.382%, expiring today), January 110.80 (-0.752%); January Brent less December WTI 8.80 from 8.86; December-December 12.88, distorted by the expiry. Thursday’s barrel: the Vance outreach wires ran from 07:02 UTC and the low printed at 13:45 UTC, then the barrel rallied 3.21 to its high with no stamp; the overnight spike’s earliest timed wire (Trading Economics 01:39 UTC) sits inside the spike bar and the substantive reports (a tanker hit in Hormuz, strike options briefed) were retrievable only through a 05:49 UTC wrap at tier 3. Chain not established in either direction. Gold spot 4,020.88 (-1.130%), 3,988.40 at 08:20 UTC; December gold 4,031.40 (-0.499%), 3,998.20; December silver 52.38 (-2.40%), 50.88 (-2.86% on the settle); December copper 6.603 (-1.03%), 6.516. Bitcoin 77,903.65 on the Friday mark (-4.104%), Coinbase 77,780.33 (0.159% apart), 77,976.35 at 08:20 UTC; ether 2,251.06 (-4.477%), 2,229.46. Flows: Farside bitcoin client_error on a fifth cache-busted read across two editions; ether fragment (20 July to 6 August rows, MSSE column absent) on two reads for a fourth edition; the all-data path is blocklisted. Relays, not carried: bitcoin +17.07m (29 Oct, KuCoin, provider unnamed), +137.33m (28 Oct, SoSoValue); ether -105m (29 Oct), -21m (28 Oct). No 27 October row on any route. Cumulatives frozen at 57,361 and 12,748, carried.
Attention (ruling V, stored)
Boards bracketed 07:32:00 to 07:32:07 UTC. Equities top 10: INTC, AMZN, IOVA, RDDT, MAGS, NVDA, SBUX, BMNR, CMCSA, SLV. Crypto top 10: PEPE.X, BTC.X, ZBCN.X, GLD.X (tokenised tracker, by deeplink), AERO.X, BNB.X, XRP.X, ADA.X, SOL.X, UNI.X; ETH.X 11. All-asset top 10: INTC, AMZN, IOVA, RDDT, RIVN, MAGS, SBUX, SLV, MSFT, BMNR; BTC.X 14, NVDA absent from the top 25. Canonical sentiment: INTC 69, AMZN 82, GOOGL 84, MSFT 69, BTC.X 34 (from 29), ETH.X 28, MSTR 18, AAPL 17. Zacks popular: AAPL, MU, NVDA, SPCX, SNDK, META, AVGO, AMZN, BE, MSFT. New unresolved symbols: ANTHZZX.P (a private-market tracker), GEOM.X, BOBO.X, XCN.X; SKY.X still unresolved. Under-covered by the wires: IOVA (rank 3, volume 87), MAGS, BMNR, CMCSA, ZBCN.X. Third observation in the stored panel; nothing published as a shift.
Forward catalyst slate
Today: employment cost index Q3 12:30 UTC; Chicago PMI 13:45 UTC; Musalem 16:30 UTC on the TradingView calendar only, the St Louis Fed’s own pages not confirming; Exxon and Chevron before the open (XOM consensus conflicts across two routes, $4.08 and $4.12, neither published); December Brent expiry; month-end. Next week: Monday 2 November ISM manufacturing, Apple’s results (corroborated on two routes, both via the TradingView connector); Tuesday 3 November the midterms and JOLTS; Wednesday 4 November ISM services; Friday 6 November October payrolls at 13:30 UTC (BLS schedule page), prior +29,000 and 4.2%. US clocks change Sunday 1 November: 08:30 ET releases move to 13:30 UTC and the FOMC-era 18:00 UTC statement slot becomes 19:00 UTC. No Board speech is scheduled through 31 October on the Board’s page. Open-shot test: the Part 233 divergence shot is secured; the Part 232 ether shot is closed on failure of measurement with a re-opening condition.
Divergence flags
- The 2-year fell 6bp on a morning the year read 3.6% and the quarter 2.1%; the quarterly components carry the fall’s sign; the release is the published cause. (New.)
- The index fell and 9 of 11 sector proxies rose; NYSE 2.34:1 positive on a down day. Wednesday was the mirror, 7 of 11 proxies lower on an up index. Second consecutive edition of index-against-proxies, opposite signs; recorded, not promoted.
- Bond volatility at its lowest since 22 September whilst equity volatility rose into a 2% overnight gap: the two fear gauges parted for the first time in three editions.
- Credit funds captured less than their durations owe on a rally day; spread or close-timing, unresolved. Recorded as checked.
- The wires’ December hike narrative (17:01 UTC) against a 2-year that fell from 12:30 UTC. (New; third-edition clock for ruling Y starts.)
- Microsoft’s +2 to +5% relay against a -0.16% close: the relay class failed on follow-through for the first time this week.
Carry-over note (§10.6)
Fires on the premarket leg. Nasdaq futures opened 1.29% lower and were 2.15% lower at the capture after three stamped results, the explained kind, and after the recut that leg, joined to Thursday’s, is the spine. The other side of the bridge, a front end that fell 6bp on a mixed print, goes to Macro Edge. AVE takes the night shift; the Snippet takes the departures board; Macro Edge takes the dissection.
Regime and sensitivity read (§17.3)
Weathervane turn condition: 2 sessions in which a dated Federal Reserve communication moves DGS2 by 10bp or more whilst DGS30 moves by less than half. No dated communication on 29 October (the Board’s page lists nothing after 14 October; Musalem is a Reserve Bank president, on Friday). Not testable; thirtieth consecutive non-advance, the first after a test. The Weathervane is carried unchanged; “frozen for most of the year” beside a 25bp hike on 16 September is flagged for a twenty-second edition and is Phil’s. Candidates: 1 (dollar non-response) not scored, the dollar fell 0.29% on a 6bp 2-year fall, a response of the candidate’s sign; 2 retired; 3 retired, replacement leg thirty-five editions overdue, and this is the session it was for: bond vol fell to a five-week low whilst equity vol rose; 4 retired without a return condition; 5 counter 3, auctions unscored now twenty; 6 no threshold text, and a 6bp front-end rally on a mixed print, hot on the year and soft on the quarter, with no policy move is at least adjacent to its point; 7 scoreable, does not fire; 8 ratio 0.888 from 0.880, moved 0.008 against a 0.070 condition, silent; 9 limb one gap share 95.45% (NDX) is above 80%, trips; limb two NYSE advance-decline 2.34 above 1.00 with the index down, the carried rule requires both limbs and limb two’s sign is the wrong way for the rule as written: does not fire, and the rule text wants a ruling.
Sensitivity: running LOOSE, fifty-first consecutive edition, stated openly. Diagnosis stays specification: the one candidate that would have read today’s bond-versus-data session (6) has no threshold text, and the one that would have read the fear gauges parting (3’s replacement) has not been written.
Route and record notes for the registry
Treasury CMT first fetch stale (26 October top row), fetches two and three clean; stale-first count stands at 10 of the last 17. fiscaldata empty for 26 to 29 October, fourth consecutive edition with auctions missing. ForexFactory client_error, third edition. Farside bitcoin client_error (fifth read), ether fragment (fourth edition), all-data path blocklisted; both Lesson 27 conditions met and the blocklist decision stays Phil’s. CBOE:VIX global-hours bars served from 07:15 UTC, third confirmation. ICE Brent 5-minute feed about 10 minutes delayed, re-quote taken one bar back. TVC:US30Y resolves on a direct fetch (new). BEA release URL slug differs from the brief’s guess; the lane recovered it by search. St Louis Fed speaking-schedule page 404. investing.com rate monitor stamped 27 October on both reads, pre-FOMC and stale; direction only (December hike favoured on a stale page) and not carried into any reader file. Stocktwits all-asset board distinct from the equities board (NVDA rank 6 on equities, absent from the all-asset top 25). No 429s anywhere in the run.
Drift gate at delivery (§11.9.1, both limbs)
Fresh re-quote at 09:00 to 09:10 UTC, every movable locked figure in the key set (20 checked, 0 missing). Limb one, price distance: December silver 50.915 against the 52.38 settle, -2.80%, carried in copy as the settle and the 08:20 UTC re-quote of 50.88; VIX 18.08 on the 08:55 UTC global-hours bar against 17.20, +5.12%, carried in copy; every other figure inside 2%. Limb two, distance to each threshold, both directions: December NQ -1.98% at 09:00 UTC is 0.02 points back under the 2.0% spine-candidate line (crossed between 08:15 and 09:00 UTC) and 0.48 over the 1.5% lead line; December ES -0.84% is 0.16 short of the 1.0% §8.5 trigger it crossed at 08:15 UTC and 0.24 outside the 0.6% band; VIX +5.12% is 2.88 short of the ±8% volatility leg; December WTI 103.42 is +1.39% on the settle, 2.61 short of the 4% commodity leg. Section 8.5 still fires and still leads the block; the spine-candidate reading at the capture is stated with its 09:00 UTC requalification in every letter.
Re-quote after the earnings recut (10:15 UTC bar, ES and NQ only; other movables carried from 09:00 UTC). December NQ 28,843.25, -2.43% on Thursday’s settle and -3.79% on Wednesday’s: back over the 2.0% spine-candidate line by 0.43 points, and the two-night fall is 0.27 points deeper than the 3.52% the headlines carry at the capture. December ES 7,670.25, -1.08% on Thursday’s and -1.45% on Wednesday’s: back over the 1.0% §8.5 trigger by 0.08 points. Every letter ties the 3.5% and 2.15% figures to the 07:45 UTC capture in the past tense; the futures have moved further the same way since.