Equities panicked, bonds rallied, credit barely moved: three readings of one Thursday
⚓ Weathervane. The wind is coming from the long end. The policy rate has been frozen for most of the year whilst the term premium does the tightening, and the price of long money is set by deficits, issuance supply and a synchronised global duration bid rather than by the committee. Higher-for-longer stopped being a Fed decision and became a bond-market fact. The cruise ship is holding this heading.
 Ahoy there, Trader! ⚓️
It’s Phil…
When chips fall 11.2% and the 2-year yield falls 12bp on the same day, is the market pricing an AI problem or a growth problem?
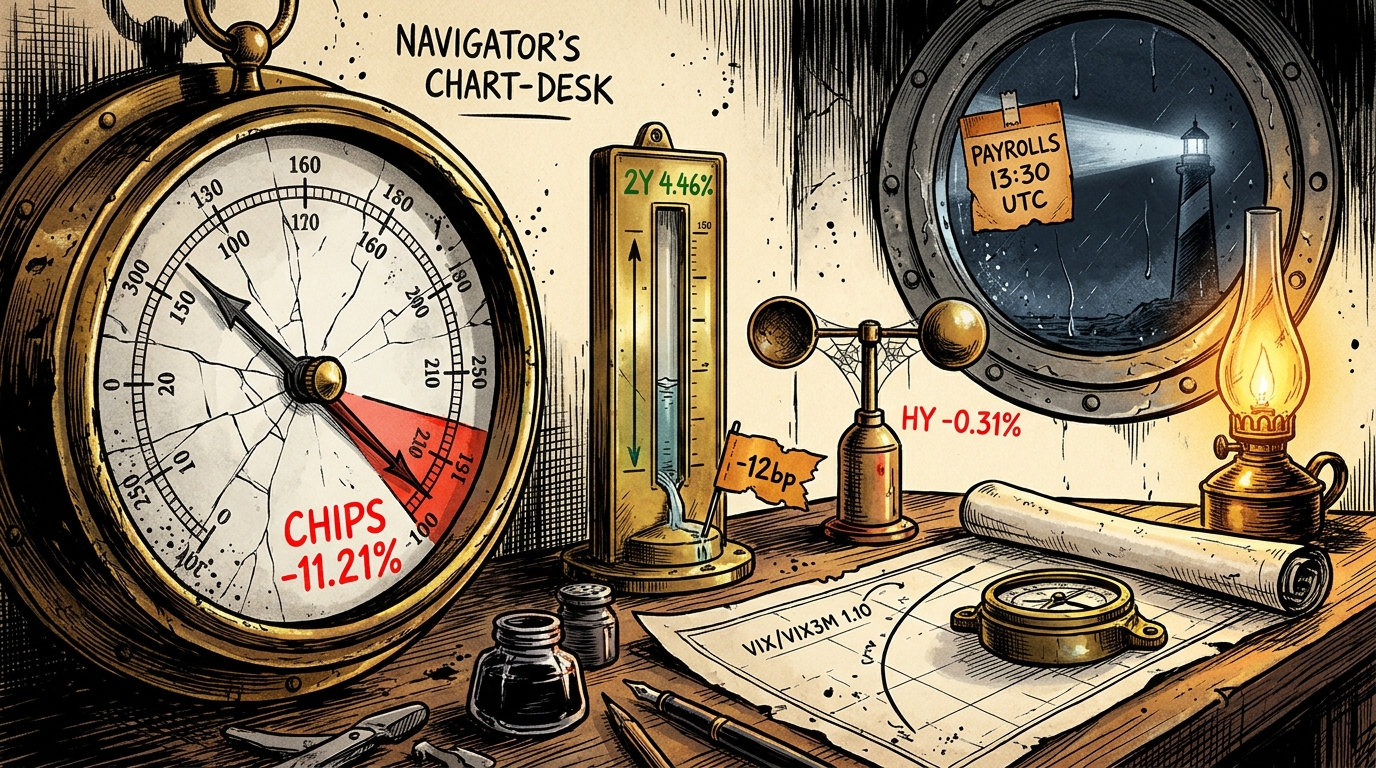
Start with what moved. The chip fund SMH lost 11.21%, the Nasdaq 100 6.36% and the S&P 500 4.36%. The VIX rose 69.66% to 28.18 and, more tellingly, closed above VIX3M at 25.55, a ratio of 1.10 against 0.88 the day before. A volatility curve that inverts is the market paying more to insure this month than the next three. That is fear with a date on it.
Then the bonds. The 2-year yield fell 12bp to 4.46%, the 10-year 6bp and the 30-year 3bp, so the curve steepened from the front: 2s10s widened to 38bp. A front-end rally of that size usually reads as the market pulling forward the Fed’s next move toward easing. If that is what it is, it is not a semiconductor thought. It is a growth thought.
The textbook says a crash confined to one sector should leave the front end alone, because the Fed does not set rates for chipmakers. It also says a genuine growth scare shows up in credit, because weaker growth means weaker borrowers. So here is the useful pair of numbers. High yield fell 0.31% on a day the Nasdaq 100 fell 6.36%: roughly a twentieth of the size. Bond volatility, the MOVE index, rose 4.3% against the VIX’s 69.66%. If the economy were the problem, credit and rates volatility would have been in the room. They sent apologies.
So the two-year and the credit market disagree. One possibility is that the 2-year rally was a haven bid, money leaving equities and parking at the short end, rather than a forecast; TLT rose only 0.21%, which fits a short-end bid more than a long-duration one. Another is that bonds are simply earlier than credit, which is often the order things happen in. This book holds no positioning or flow data that would separate those two, and says so.
What would settle it is on the calendar for 13:30 UTC. If October payrolls come in firm and the 2-year gives back its 12bp, Thursday was an AI problem with a haven bid attached. If payrolls are soft and credit starts to follow the front end, the chips were the first to read a growth problem everyone else is about to read.
Phil’s Musing
My instinct is that this is a crowded trade meeting a narrow door, and the bond rally is people hiding rather than forecasting. But the inverted VIX curve bothers me. Fear that wants protecting this month, not next quarter, usually knows something about the calendar, and the calendar today says payrolls.
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
🗂 Desk Notes – Part 245 | 6 Nov 2026
Session read (§8.4)
SESSION BRIDGE: prior session (Thu) full reaction [ES Dec settle -4.37%, SPX cash -4.36%, NDX -6.36%, VIX +69.66% to 28.18, SMH -11.21%; overnight NQ Dec range -1.44% to +1.52%]; live premarket ES +0.04% / NQ +1.05% at the 07:45Z capture (ES +0.09% / NQ +0.95% at the 08:15Z bar), VIX +69.66% (prior-session close, no global-hours print); threshold: HARD.
- Equity leg: ES Dec settle -4.37% is past the 2.0% hard line. Volatility leg: VIX +69.66% fires on its own. Commodity leg silent (WTI Dec +2.72%).
- Cash trigger (§8.4.2): sector spread 7.41pp (over 4.0); named constituents over 10% (AMD, MU, SNDK, WDC, LITE, INTC). Board and decomposition mandatory and run.
- Decomposition: SPX gap 3.0% / intraday 97.0%; NDX gap 19.9% / intraday 80.1%.
- Capture: four-contract two-read, 07:45-07:50Z bar, byte-identical at 08:05Z and 08:10Z with the adjacent bar mutating (control held). Thirteenth consecutive on-time four-contract capture.
- Basis: es_spx 29.27, nq_ndx 122.19. No contract roll (Dec expiry 18 Dec).
Hot News board
- AI and tech rout – ROLLING, LEAD (escalated). Thu: SMH -11.21%, SOXX -12.15%, AMD -17.26%, MU -17.46%, NVDA -9.26%. Fri: Kospi 20-minute halt, Nikkei sharply lower at open (AP via WSLS 00:43Z; Euronews 07:01Z). Not known: whether any data-centre restriction follows; whether this is de-grossing that exhausts. Next: payrolls 13:30Z; Nvidia 17 Nov.
- US midterms 2026 – ROLLING. AP 253 Democratic House seats (22:49Z Thu); CBS projects 251-268. Jeffries Speaker bid unopposed. Mississippi uncalled, lead 1,138-1,818 depending on count (Part 244’s “65 votes” unsupported, corrected in AVE). Alaska RCV not before about 18 Nov. Lawler conceded NY-17. Trump blamed “Dumocrats” (Bloomberg via Yahoo 00:36Z). Next: Mississippi cure deadline 10 Nov.
- Middle East / Iran – ROLLING. NYT (19:38Z Thu): Iran weighing Qatari proposals. No acceptance, no talks date. UKMTO: tanker hit north of Qatar Thu. Brent Jan +3.88% to 98.29. A Stocktwits claim of a Reuters “major combat operations” order was found on no wire and is not published.
Mechanism read
| Tenor | 5 Nov | Change |
|---|---|---|
| 2-year | 4.46% | -12bp |
| 10-year | 4.84% | -6bp |
| 20-year | 5.27% | -3bp |
| 30-year | 5.25% | -3bp |
2s10s 38bp (+6), 2s30s 79bp. Bull steepening led from the front. VIX 28.18 / VIX3M 25.55 = 1.103, inverted (0.884 prior). MOVE 97.93 (+4.3%). HYG -0.31%, LQD +0.15%, TLT +0.21%. DXY 101.565 (+0.07%), USDJPY -0.47%.
The one artery: equity-specific de-risking concentrated in AI hardware, with a front-end haven or growth bid alongside and credit largely absent. Spine crowned: SMH -11.21%.
Cause board (§8.3)
Effects without causes: the intraday 97.0% of the SPX fall and 80.1% of the NDX fall; the overnight NQ-up / YM-down split.
Causes without effects: Bank of England hike to 4.00% (12:00Z, 8-1) moved no US instrument visibly; US jobless claims 189k (13:30Z, tier 2) printed before the open, which carried 3.0% of the SPX move.
The refusal, with its search:
- Routes checked: TradingView news and news-story, Yahoo Finance live, Fox Business, AP syndication, Euronews, Benzinga via TradingView.
- Stamps found (no intraday index path held, so the stamps are tested against the open, which carried 3.0% of the SPX fall): UBS data-centre estimate on Reuters 11:21Z (5 Nov special report); SOXX opened 4.70% lower; Nomura/Vanda de-grossing 20:06Z and 20:45Z; Hennion & Walsh AI doubt 19:03Z; eToro data-centre reading 20:52Z; Goldman capacity estimate 21:09Z; Qualcomm results 21:00Z on 4 Nov (stock scope).
- Test run: majority test against the SPX cash path (open 14:30Z, 3.0% gap) and NQ Dec reads. Every index-scope candidate is stamped after 19:00Z, long after the open; with no intraday index path held, no candidate can be shown to precede the majority of the move; the midterm result (04:40Z 4 Nov) precedes it but preceded a 1.58% SPX rise the day before. Result: the data-centre news precedes the chip leg (sector scope, priced before the bell) but no new stamp precedes the index’s post-open majority. No named cause at index scope; majority_unexplained. Thursday’s special report (antivestor.com/news-edge-05-nov-2026) carries the full clock.
Candidate dispositions: data-centre regulation reading (class 3) coincidence; de-grossing (class 4) coincidence; Qualcomm and Arm outlooks (class 2) refusal at index scope; midterm result (class 3) refusal; Bank of England and jobless claims to Desk Notes as causes without effects. Ruling S null rate: index-scope NULL this edition.
Overnight Excitement (§8.5)
Fires and leads on the range: NQ Dec high +1.52%, low -1.44% vs settle (window 21:00Z 5 Nov to 08:15Z 6 Nov). Capture +1.05%, re-quote +0.95%, now 0.05pp below the 1.0% fire line. YM Dec -1.03% capture, -0.91% re-quote. Asia sharply lower (direction only): Kospi halted 20 minutes, Nikkei, Taiex lower. After-hours: NET +16.51% (21:15Z), ABNB +11.0% (21:03Z), TEAM -17.62% (21:05Z), AXON -11.94% (21:01Z); DKNG direction lower, size unresolved.
Forward catalyst slate
- Fri 6 Nov: Williams 09:30Z; October payrolls 13:30Z (consensus conflicts 65k vs 59k, not published); Michigan sentiment 15:00Z; Bowman 17:15Z (supervision); consumer credit 20:00Z.
- Ledger closes today: gold spot vs 4,061.11 (re-quote 4,065.99, above the line by about 5); Dec WTI below 96.09 through Friday (90.33, holding).
- Next week: CPI Tue 10 Nov 13:30Z; Waller Tue 10 Nov; Veterans Day Wed 11 Nov; PPI Fri 13 Nov. Refunding auction dates unconfirmed (fiscaldata empty).
- Nvidia results 17 Nov.
Divergence flags
- 2-year -12bp against HYG -0.31%: the front end rallied, credit did not.
- VIX +69.66% against MOVE +4.3%.
- NQ Dec +0.95% against YM Dec -0.91% at 08:15Z, after Asia sold chips.
- Gold haven flag: Thursday spot gold rose on a risk-off day, so the Wednesday divergence (gold up, VIX down) did not recur. Two editions, not three; not promoted.
Carry-over note (§10.6)
Fires (HARD). The market spent Wednesday pricing the midterm result as good news and Thursday pricing something nobody had stamped. The real tell was the 2-year, not the chips.
Regime and sensitivity read (§17.3)
Weathervane carried, NEUTRAL: the move was front-end led and the 20-year held the curve maximum for a 40th session. Turn condition (a dated Fed communication moving DGS2 10bp+ with DGS30 under half) not advanced: Thursday’s 12bp/3bp shape matches the ratio but carries no Fed communication. Thirty-fifth non-advance. Regime flag not tripped; a VIX curve inversion is a candidate signal with no pre-stated condition. Sensitivity running LOOSE, stated openly.