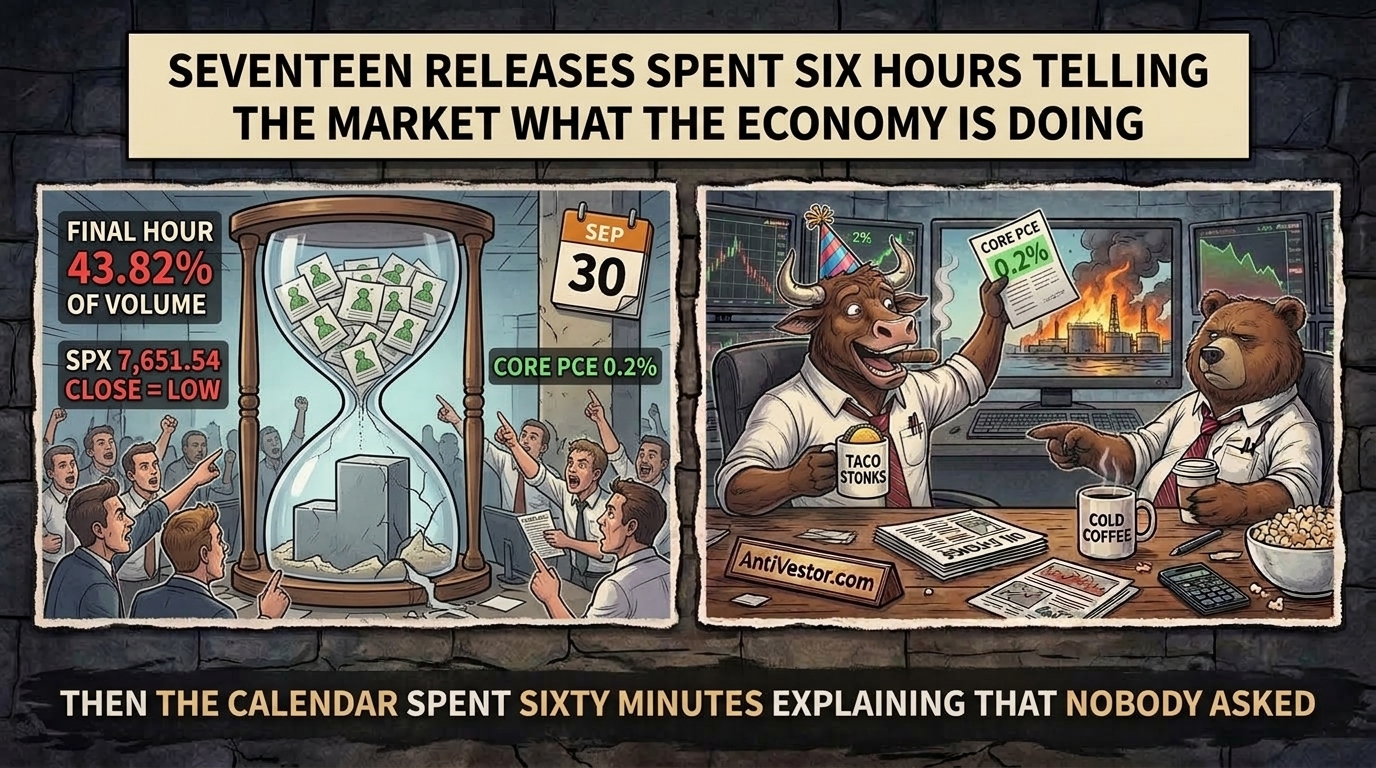
Markets spent 6 hours agreeing with the data and 60 minutes agreeing with the calendar
 Ahoy there, Trader! ⚓️
It’s Phil…
$37.7bn of Profit Landed After the Quarter Had Already Closed Micron’s numbers arrived to a settled book and an empty room
Markets Agreed With the Data All Day, Then Changed Their Minds for Admin Reasons 17 releases, 1 timestamp, and a close that ignored all of them
Seventeen economic releases hit one 08:30 timestamp on Wednesday and they could not have been clearer, because the two halves of the data set pointed opposite ways. Both inflation cuts undershot: core PCE 0.2% against 0.3% expected, 3.0% annual against 3.3%. The growth cuts overshot, with the GDP third estimate revised up to 2.2% against 1.5% and personal spending at 0.9%. Chicago PMI arrived an hour and a quarter later at 58.8 from 47.1.
The Treasury curve did the sensible thing and finished split in two. The front end believed the inflation and richened, five basis points at the 3-month. The long end believed the growth and cheapened, five at the 30-year. Two-year to thirty-year widened 70 to 76, the widest in ten sessions. Two halves of one instrument, reading one page, closing on opposite sides, both of them defensible.
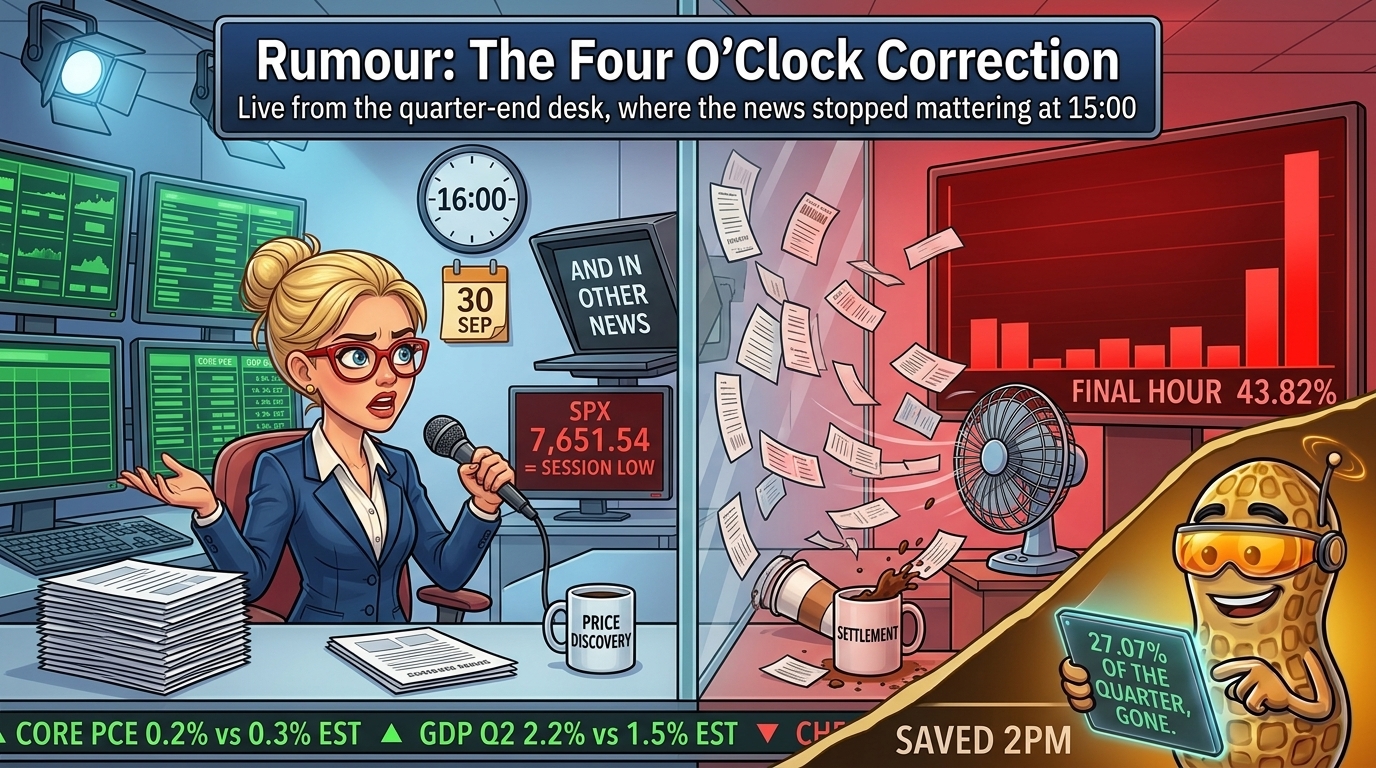
Equities read the same page and rallied 0.6784% by midday. Then four o’clock arrived and the quarter ended, and in sixty minutes the S&P 500 gave back 41.20 points on 1.37 billion shares, 43.82% of the whole session’s volume at 4.68 times the prior six hours’ pace. It closed at 7,651.54, which was also, to the decimal, its low. So did the other three.
The tape did not change its mind about the economy. It was closing its books.
The One That Mattered
Seventeen releases is a lot of information, and the market processed all of it beautifully for six hours. The curve split, the front end rallied, equities took the inflation print and went up. Then 43.82% of the day’s volume arrived in one hour and undid the lot, carrying four separate indices to four exact lows on the same print. That single hour erased 27.07% of the entire quarter’s S&P gain. Nothing in the news flow explains it. A rebalancing calendar would, and nobody writes a rebalancing calendar into a market narrative.
When a calendar moves a market more than a data set does, which one should we be reading? We went down the rabbit hole in today’s Macro Edge. https://antivestor.com/macro-edge
Overnight Excitement
Micron reported past the cash close and Asia took it personally. December NQ ran 1.3299% overnight, clearing the threshold on its own, whilst December ES managed 0.5832% and December YM a pointed 0.1521%. A 0.75 percentage point spread between two US index futures on one night is not an index bid; it is a semiconductor bid that has borrowed the index’s clothes. Tokyo’s chip names did the heavy lifting on memory demand, on syndicated reports, which also have Korea and Singapore opening lower whilst Hong Kong was shut for the National Day holiday. So the bid did not generalise so much as pick a sector and stay there. NQ also dipped below its prior close before deciding otherwise, which ES never did. One qualifier, and it is the honest one: re-quoted at 07:55 UTC the same contracts read NQ at 0.4471% and ES at 0.0032%, so most of this had gone before breakfast. The dispersion was real for about ninety minutes.
Stock Market Edge
The Last Hour Was 43.82% of the Day and 27.07% of the Quarter Six hours of analysis, sixty minutes of paperwork
Premarket snapshot:
December ES traded 7,760.50 on the 06:30:00 to 06:34:59 UTC five-minute bar, captured at 07:30 UK and read twice past its close byte-identical on both reads, up 0.5832% on Wednesday’s 7,715.50. December NQ was up 1.3299%, December YM 0.1521% and December RTY 0.3549%. Cash closed 7,651.54, and the overnight ran 7,717.50 to 7,767.75 without once dipping under the prior close, which is more conviction than the cash session managed all day.
Sector rotation:
Ten of the eleven sector proxies fell and technology alone rose, at 0.6427%. Staples led lower at 1.5272%, health care 1.353%, industrials 1.2712%. The tell is not the ranking: all eleven closed in the bottom 30% of their daily ranges, the highest at 27.2%. Eleven sectors do not independently decide to finish near their lows. One order book with a deadline leaves exactly that shape.
Earnings or guidance:
Jabil beat on revenue at 10.62 billion dollars against 9.71 billion expected, beat on earnings, guided fiscal 2027 revenue up 24%, and fell 10.0301%. FactSet guided fiscal 2027 below estimates and rose 3.8389%. Micron, reporting after the bell, booked 54.23 billion dollars of fiscal fourth-quarter revenue, up 379.3%, and 37.7 billion of net income, which is a 69.52% net margin. Its shares had closed the session, hours before any of that was public, three cents higher.
Cross-asset nuance:
The dollar added 0.0838% alongside a long-end selloff, 71.5% of it the euro leg, which is a thin response for a 5 basis point move at the thirty-year. November WTI settled 90.42 dollars, up 1.1636%, whilst the same-date November-to-December backwardation narrowed to 2.00 dollars flat. Prices up, urgency down. December gold settled 4,186.7 and volatility closed 16.34, having watched all of the above and reached no conclusion whatsoever.
Crypto Market Edge
847,666 Coins Bought at 85,681 Into a 37-Dollar Day The structural bid turned up, looked around and left
Price snapshot:
Bitcoin closed 83,587.83, down 0.0438%, which is about thirty-seven dollars, and two independent exchange routes agreed to 0.0379%. Ether closed 2,684.86, up 0.3026%. The 07:00 UTC marks read 84,137.13 and 2,718.22, both still forming, both above Wednesday. On a session when a quarter gave back a quarter of its gain in one hour, the asset class built to overreact simply did not turn up.
Flows and positioning:
US spot bitcoin funds went out 148.7 million dollars, the first negative reading in the nine sessions this book holds, after six sessions of decay from a 999.0 million peak. One issuer was 125.6 million of it, 84.5% of the day. We are not scoring it, and the reason is instructive: nine of twelve issuer cells read as zeros on one pull of the table and as blanks on another pull minutes later. Ether, in the same run, rendered every cell numeric both times and went out 59.6 million.
Leadership and rotation:
Bitcoin, XRP and Solana held no place on the crypto-only or the all-asset top 25 at the 07:06 UTC capture, a third consecutive session, whilst ether and Dogecoin wandered back at ranks 6 and 10. Before anyone declares the retail bid dead, bitcoin’s annual normalised message volume reads 59 and high. The talking continues. The ranking has other priorities, which this morning meant a tokenised gold wrapper.
Catalysts and roadmap:
Strategy’s 847,666 bitcoin are now confirmed from the filing document rather than carried forward, after 1,665 coins at an average of 85,681 dollars in the week to 27 September. Wednesday settled 83,587.83. The 142.7 million dollars went out of the door roughly 2,093 dollars a coin too early, and 13.6% above the firm’s own book average of 75,437.
TL;DR
- Seventeen releases landed on one timestamp, inflation undershot and growth overshot, so the front end richened up to 5 basis points whilst the 30-year cheapened 5 regardless.
- The S&P 500 traded 43.82% of its entire session volume in the final hour, which erased 27.07% of the whole quarter’s gain in sixty minutes.
- All 4 indices closed at their exact lows and all eleven sector proxies inside the bottom 30% of range, which is one order book rather than eleven opinions.
- Jabil beat both lines and guided up 24% and fell 10.0301%, whilst FactSet guided below estimates and rose 3.8389%, same tape, same hour.
- Strategy paid 85,681 a coin for bitcoin that settled 83,587.83, then watched the asset move about thirty-seven dollars and the funds lose 148.7 million.
Fun Fact
There Were 2 Brent Settlements on Wednesday, $5.50 Apart And the one above $100 was the one nobody was trading
November Brent’s last trading day was Wednesday, so it settled at 103.53 dollars on 22,419 lots whilst December, the contract that actually matters now, settled 98.03 on 448,472. Any headline quoting Brent above a hundred that day was quoting a contract on the final afternoon of its life.
Meme of the Day:
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
p.s. There are 3 ways I can help you…
- Option 1: Collect Morning Income
A complete guide to the Premium Popper system.
Written to be clear, concise, and immediately actionable.
>> Learn More Here
- Option 2: Collect Weekly Income
A complete guide to the Tag ‘n Turn system.
>> Learn More Here
- Option 3: Join the Fast Forward Mentorship
>> Join the Fast Forward Mentorship – trade live, twice a week, with me and the crew.
PLUS Monthly on-demand 1-2-1’s
No fluff. Just profits, Tag ‘n Turn Pulse bars, Poppers, and Patterns that actually work.