CoreWeave traded 1.46x its whole previous session in 1 hour. Investment grade credit rose 0.11%.
 Ahoy there, Trader! ⚓️
It’s Phil…
Something Large Was Sold Yesterday and High Yield Credit Moved 0.36% The worst Nasdaq-100 day in 6 weeks, and the market that funds leverage used a third of its own weekly range
The Nasdaq-100 fell 2.023799%, which is the largest single-day decline of the 29 daily moves this book holds. The next worst is 1.394%. So whatever happened on Wednesday was not a drift, and it deserves an explanation rather than a shrug.
The explanation on offer is September inflation at 3.7% against a 3.6% consensus. It does not fit, and the clock is why. The print landed at 12:30 UTC, an hour before the open. It bought the gap: 253.4563 points, 40.968262% of the day. The other 365.2087 points, 59.031738%, arrived during the session, grinding lower until the low at half past two in the afternoon. A tenth of a percentage point on consumer prices paid for the opening and not for the rest.
What the rest looks like is one theme being sold. The semiconductor proxy fell 4.500827%, its second-worst session of the same window. CoreWeave gapped 7.794628% and then traded 3,999,467 shares in the first hour alone, which is 1.458849 times its entire previous session, closing 15.460738% down on 3.894134 times the prior day’s volume. Dell lost 11.27%.
And every hedge fell with it. Gold spot 1.327303%, December silver 6.128517%, bitcoin 1.758%. Only duration and the defensives rose.
The One That Mattered
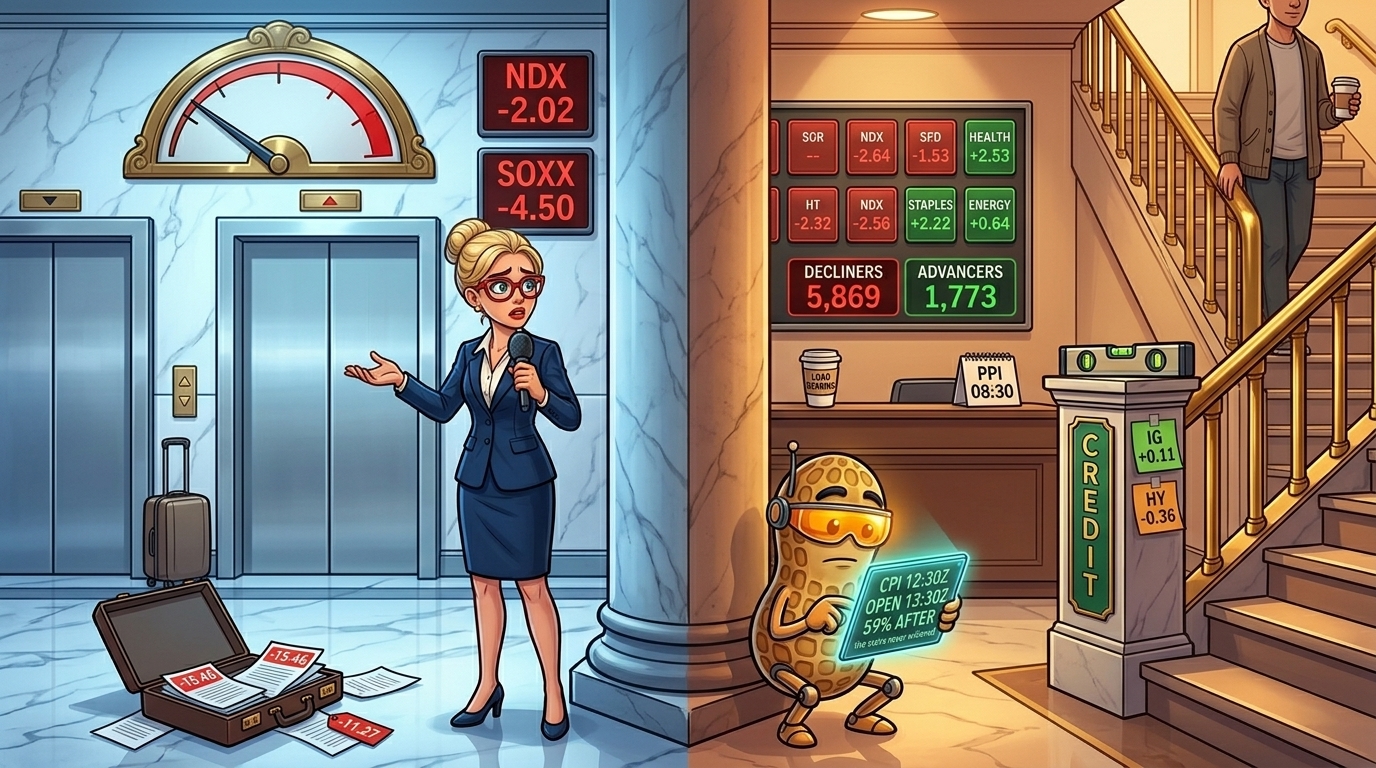
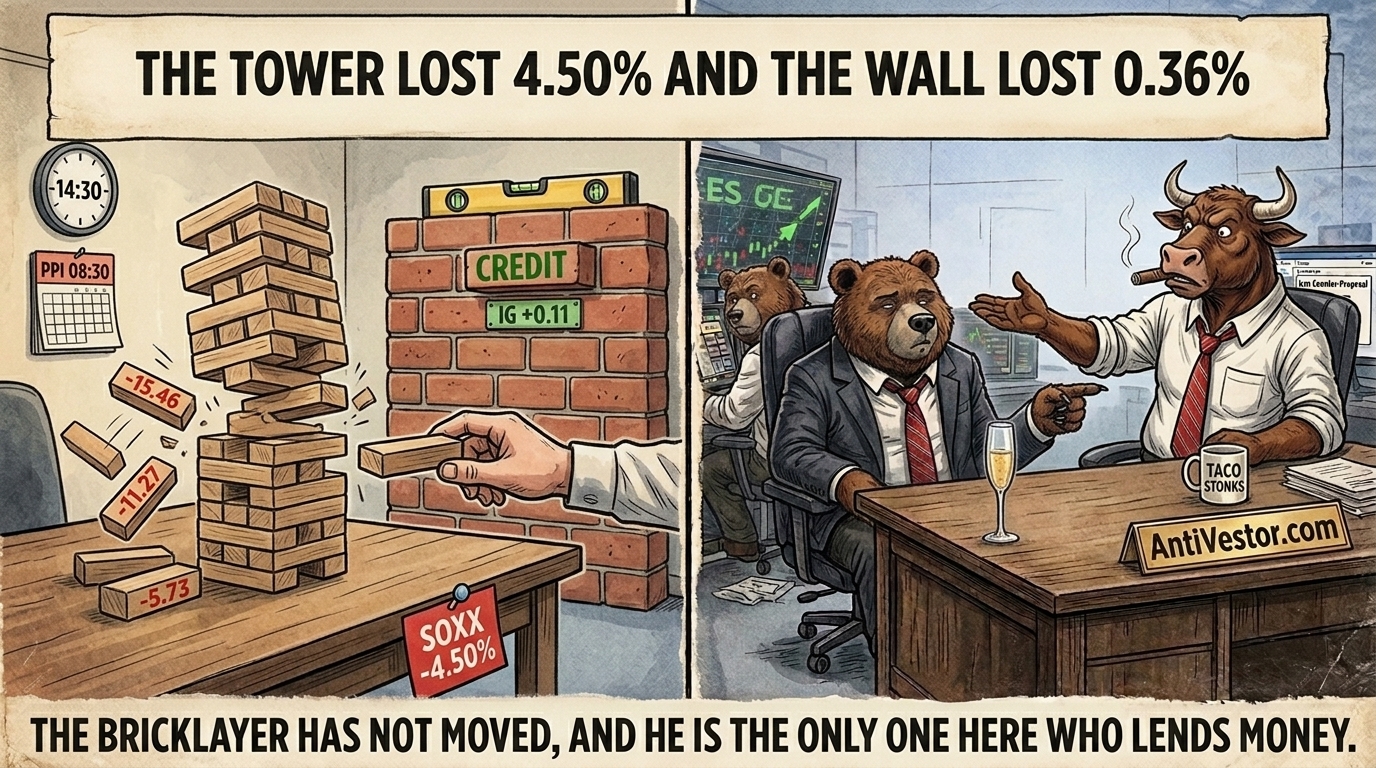
Everybody will crown the 2% Nasdaq day and most will pin it on the inflation print, and the number worth having is one almost nobody will print: high yield credit fell 0.363212% whilst investment grade rose 0.107265%. High yield fell further than investment grade, which is the right order. It fell a third of one per cent against a 15.460738% fall in the equity of the same theme, which is not the right size. Two cautions we will not bury. The long Treasury proxy rose 0.663519% whilst investment grade managed 0.107265%, a gap of 0.556254 points, and this book holds no duration for either, so none of it converts into a spread. And a broad high yield fund is not this theme’s own financing, which we cannot see at all. If the AI trade was unwinding on leverage, why did high-yield credit barely move? We went down the rabbit hole in today’s Macro Edge. [link]
Overnight Excitement
1.14% left the December Nasdaq contract while Taiwan was raising guidance.
December NQ printed 29,840.00 on the capture bar, lower by 1.135582% on Wednesday’s settlement proxy. December ES is off 0.398957%. December RTY is up 0.236794%, a dispersion of 1.372376 percentage points, which is the overnight equivalent of two people describing the same weather. Taiwan Semiconductor reported in Asian hours, posted a 66.4% gross margin and lifted its revenue growth guidance to roughly 44%, and the semiconductor-heavy contract is the one still being sold. Asia and Europe opened lower on syndicated reports. The small-cap contract, which fell 1.93426% in the cash session, is the one bid this morning.
Stock Market Edge
One Desk Was Cleared Out and the Floor Called It 0.09% Health care and staples absorbed what came out of the semiconductors
Premarket snapshot:
December ES traded 7,739.25 on the 06:30:00 to 06:34:59 UTC five-minute bar, captured at 07:30 UK and read twice to be sure, lower by 0.398957% on Wednesday’s 7,770.25 settlement proxy. December NQ sat at 29,840.00, down 1.135582%. Both the Dow and small-cap contracts are higher, though the Russell cash session closed 1.93426% lower, so this is a premarket observation and not a verdict.
Sector rotation:
Three of eleven proxies rose: health care at 2.534481%, staples at 2.221166% and energy at 0.639881%, against information technology down 2.980436%, a 5.514917 point spread. Materials closed five cents lower. That nickel is the entire difference between a three-up count and a four-up one.
Earnings or guidance:
Five of the six US reporters this book tracked beat on adjusted or reported earnings per share. Morgan Stanley beat by nine cents and BlackRock, on an adjusted basis, by 1.63 dollars. Bank of America was the lone miss at 0.91 against 1.10, with fixed income revenue of 2,565 million dollars, down 17% on the year. The three whose closes this book holds all fell, by 4.1% to 4.8%.
Cross-asset nuance:
The dollar firmed 0.306217% to 102.528. Gold spot fell 1.33% and December gold futures 1.66%, two different numbers for one metal, which is why each is named with its own basis here. The long Treasury proxy rose 0.663519% on 1.727743 times its prior volume, the one thing in this book that rose on rising volume. On receipts: this edition’s first cut crowned the inflation print as the cause of the whole 2.023799% fall. The clock does not allow it, the print bought 40.968262% of the day, and the cut was withdrawn and rebuilt before you read this. The other 59.031738% still has no name in these pages.
Crypto Market Edge
Every Hedge Sold on the Same Afternoon 1 session of inflow, then 109.8 million dollars back out of a single issuer
Price snapshot:
Bitcoin closed 81,606.65 from 83,066.82, down 1.758%, inside a high of 84,053.01 and a low of 81,377.53. Ether closed 2,419.42 from 2,494.86, lower by 3.024%, between 2,527.26 and 2,403.10. Two independent feeds agreed on bitcoin to 0.04946%, which is wider than this book has been seeing and is being watched rather than smoothed.
Flows and positioning:
Bitcoin funds shed 261.4 million dollars. FBTC supplied 152.7 of it against IBIT’s 110.9, with BITB the only inflow at 2.2 and nine of twelve issuers flat. Ether funds lost 129.5 million, of which one fund was 109.8, or 84.787645%.
Leadership and rotation:
Eleven of the thirteen visible ether sessions are outflows. The ten-session run ended on Tuesday with a 24.8 million inflow in which ETHA contributed precisely nothing, and then ETHA came back on Wednesday as the dominant selling leg. Composition moved before direction did, and only the issuer columns ever showed it.
Catalysts and roadmap:
The 6 October bitcoin row that sat incomplete for five editions now renders in full and reconciles to its own total, an inflow of 118.8 million dollars, which is how a number stops being a rumour. Market-structure legislation still has no vehicle and no scheduled vote. The visible series starts 28 September and loses a trading session every edition, so nobody here is making a monthly claim.
TL;DR
- The Nasdaq-100 fell 2.023799%, its largest daily decline of the 30 sessions held, against a next-worst of 1.394% on 8 October.
- The inflation print landed an hour before the open and bought 40.968262% of that fall. The other 59.031738% arrived during the session with no named cause.
- Semiconductors fell 4.500827%, their second-worst session of the same window, and CoreWeave 15.460738%, trading 1.458849 times its whole prior session inside the first hour.
- High yield credit moved only 0.363212% and investment grade actually rose 0.107265%, and that is the wrong order of events for a financing problem.
- Producer prices land at 08:30 ET with the two-year at 4.82%, and three sessions remain before this book’s front-end flag is settled.
Fun Fact
The Curve Twisted and the 5-Year Was the Hinge Everything from 3 months to 3 years got cheaper and everything from 7 years out got dearer
On Wednesday the five-year Treasury closed at 5.00%, exactly where it closed on Tuesday, whilst every tenor from three months to three years cheapened and every tenor from seven years out richened. A curve that twists has to pivot somewhere, and three of the fourteen tenors sat still, two of them at the short end.
Meme of the Day:
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
p.s. There are 3 ways I can help you…
- Option 1: Collect Morning Income
A complete guide to the Premium Popper system.
Written to be clear, concise, and immediately actionable.
>> Learn More Here
- Option 2: Collect Weekly Income
A complete guide to the Tag ‘n Turn system.
>> Learn More Here
- Option 3: Join the Fast Forward Mentorship
>> Join the Fast Forward Mentorship – trade live, twice a week, with me and the crew.
PLUS Monthly on-demand 1-2-1’s
No fluff. Just profits, Tag ‘n Turn Pulse bars, Poppers, and Patterns that actually work.