Up volume beat down volume 3.56 to 1 and the Composite closed lower anyway
 Ahoy there, Trader! ⚓️
It’s Phil…
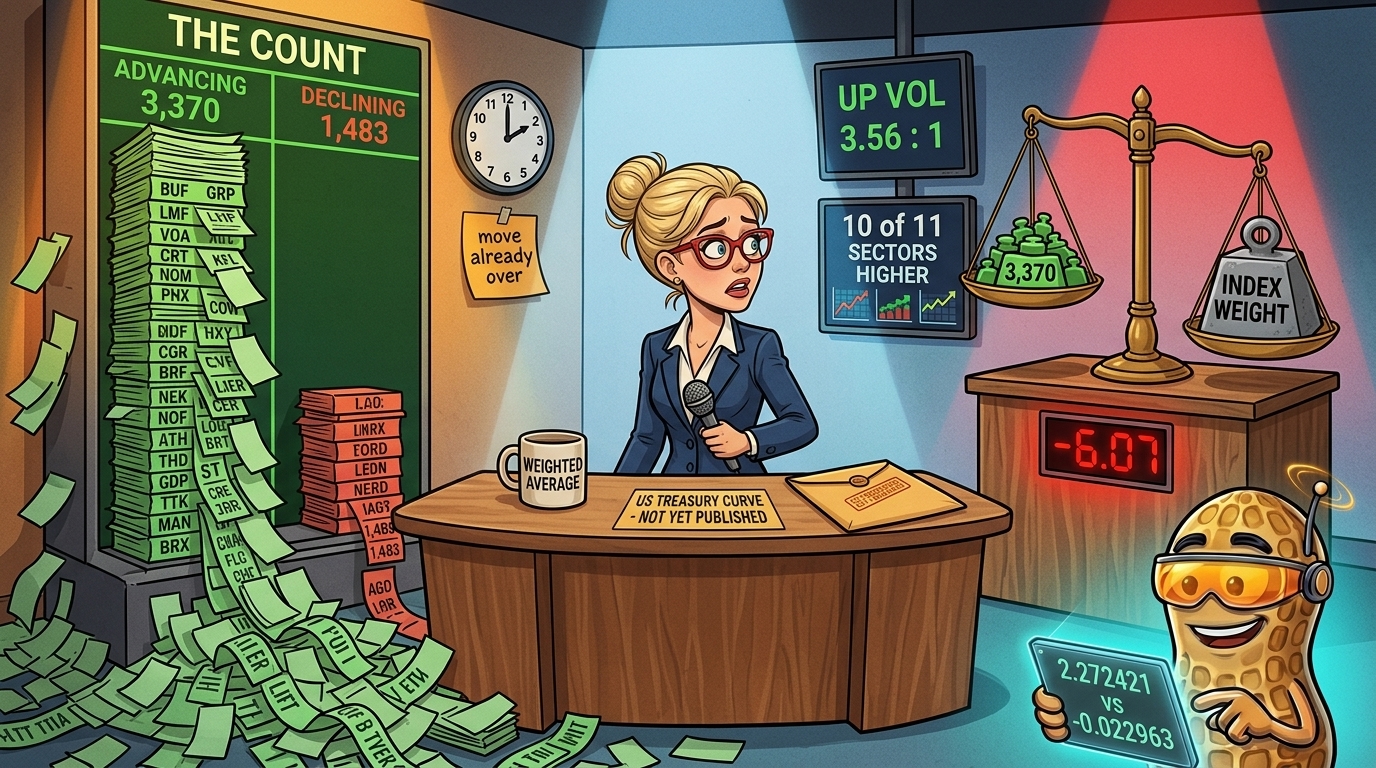
Tuesday was a landslide. On the Nasdaq, 3,370 issues advanced against 1,483 declining, a ratio of 2.272421. Up volume beat down volume 3.56207 to one, the strongest of the four breadth readings on either exchange. New York agreed: 1,825 up, 864 down.
The Composite closed 6.0693 points lower.
Six points. Not a correction, not a flush, not a de-risking. Six points, on a day two-thirds of the list went the other way, which is roughly the amount an index moves when somebody sneezes near a server.
A capitalisation-weighted index does not count companies, it weighs them, and on Tuesday the Nasdaq’s counting and its weighing filed separate reports. This book holds no Nasdaq constituent decomposition, so it cannot tell you which weights did it, and it is not going to guess.
Here is the part that makes it worth a letter. Ten of eleven SPDR sector proxies rose and the eleventh was technology, down 0.27963%. Those proxies partition the S&P 500, not the Nasdaq, and the S&P closed up 0.283978%. So two exchanges held the same shaped vote, 10 to 1 in one and 2.27 to 1 in the other, and only one index agreed with its own members.
The honest version, and it is wider than one paragraph usually gets: this book names no cause for the broad rally at all. Not for the Dow’s 1.019608%, not for ten of eleven sectors closing higher, not for 1,825 New York issues advancing against 864. Nor for the three loudest single moves inside it. A 4.925746% move in a software company was over inside thirty minutes and its two explanatory wires are stamped 86 and 88 minutes later. December crude gave back 6.12 dollars across the full trade date, from 101.37 to 95.25, with 88.2% of that complete before the first timestamped marker this book’s feed carries. Health care gapped up against a tape that gapped down. Nothing here has a clock that supports a cause.
What the admission does not cover, so you know where its edges are: the breadth divergence itself, which is arithmetic rather than a mystery, and the rates leg, which is one session older than everything else here because Treasury has not published Tuesday’s curve.
And one thing we can say at full strength, because it needs no mechanism and no duration figure. At 15:37 on Tuesday a wire explained crude’s fall by unconfirmed Iran peace talks. Two minutes later, at 15:39, a second wire explained rising defence stocks by the war in Iran. Northrop closed up 4.573%. Crude’s low is stamped 38 minutes before the first of those sentences existed. The wires filed peace and war inside two minutes, the tape bought both, and we cannot connect either to a single thing the equity market did. That everybody tried is the more interesting observation.
One receipt, since the ledger is the only thing in this letter that can be wrong on the record. On 15 October this book filed that a crowded equity unwind was not a financing event, and pre-registered the test: high yield closing within 0.3% of 76.81 confirms it, high yield more than 0.8% below that whilst investment grade also falls kills it. Tuesday high yield closed 76.83. Unchanged. Not approximately unchanged, unchanged, 0.026038% off an anchor set five days earlier. Investment grade closed 103.22, above its own 102.66 line, so neither limb of the killer fired. That shot is marked a hit today, and it is cited with its defects attached because a receipt that flatters itself is worth nothing: its pre-registered killer was unmeasurable on Monday for want of a published Treasury curve, and the duration figures that would turn a price move into a spread are stamped a day before the move they are meant to corroborate, so the sign of that spread is indicative and not established. The other two open are a breadth shot filed on 9 October, which on current arithmetic is more likely than not to be marked a miss on Friday, and a crypto-flow shot filed yesterday. All of it was written down before the tape ran.
The One That Mattered
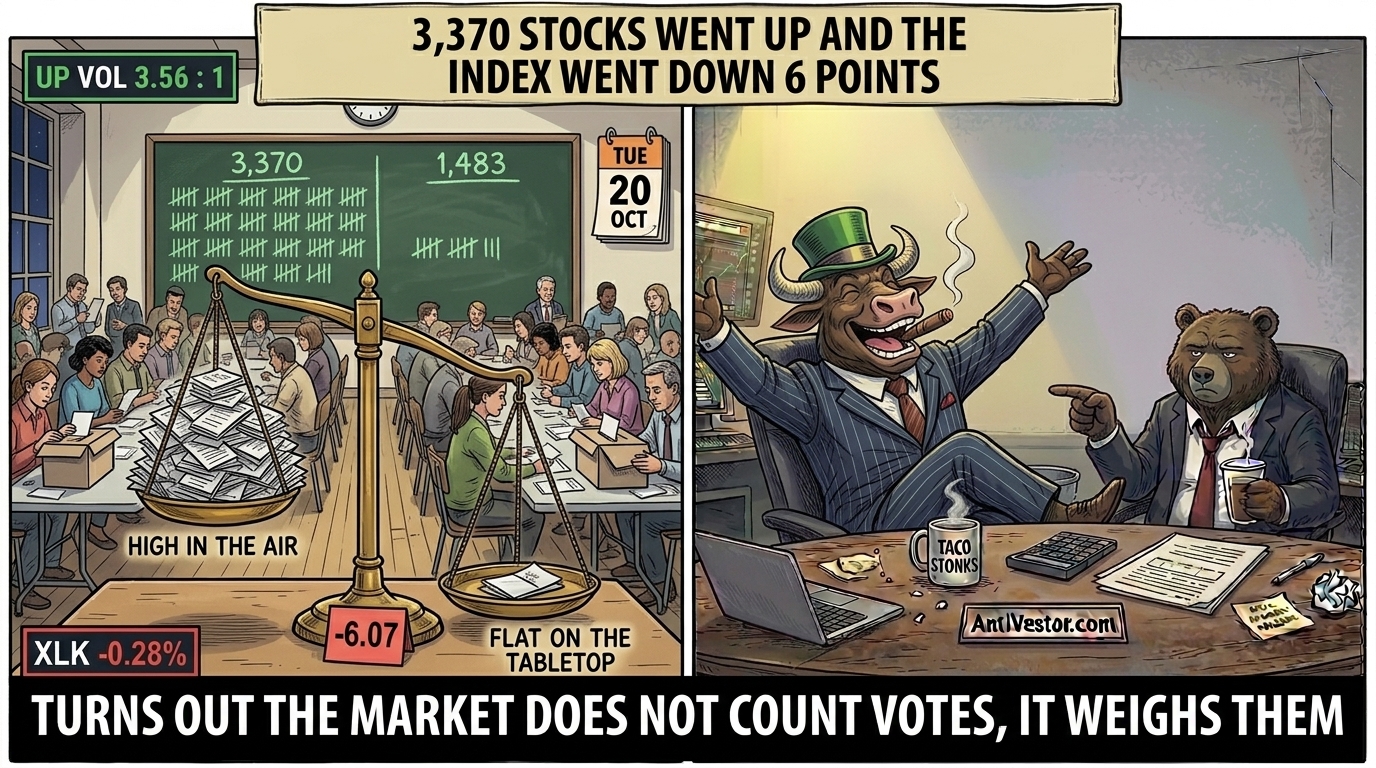
Ten sectors rose. One fell. The index went with the one, and the one was technology, because an index does not count its members, it weighs them. Wall Street spent the session congratulating itself on a 2.27-to-1 advance and then booked a loss of six points, which is the market equivalent of winning every argument and losing the marriage. Breadth is a count. The index is a weighted average. On Tuesday they disagreed, and this book holds three sessions of that measure rather than a month of it, so no record is claimed.
If 3,370 Nasdaq names rose and the index still fell, which of those two numbers is the market? We went down the rabbit hole in today’s Macro Edge. https://antivestor.com/macro-edge
Stock Market Edge
Breadth Filed a Landslide, the Index Filed a Loss Both documents are correct and only one is weighted
Premarket snapshot:
At the 07:30 UK capture, the 06:30 to 06:35 UTC bar, December S&P futures sat 7,773.5, up 0.235324% on their own prior settlement. December Nasdaq futures led at 29,849.0, up 0.585505%, which was 0.014495 points short of this book’s abnormal line and therefore technically normal by about one and a half basis points. It did not stay there, and then it came back: re-quoted at 07:55 UTC it read 0.778426%, through that line, and re-quoted again at 08:35 UTC it reads 0.236729%, back under the 0.3% typical marker. A round trip across two of this book’s own boundaries in sixty-five minutes, and not once within 0.2 points of anything it would call exciting. December Russell futures were lower by 0.104058%. The overnight dispersion of 0.689563 points runs large growth over small cap, which inverts the ordering of Tuesday’s cash session, because of course it does. One thing the index futures conceal and this book will not: a named large-cap technology maker was up 17.185% on the overnight attention board at the 06:26 UTC capture, second by rank, and no index contract came within 0.414495 points of a section 8.5 trigger. A quiet premarket at the index level is not a quiet premarket.
Sector rotation:
Health care 2.374039%, real estate 1.703864%, utilities 1.257253%, financials 1.198692%. Technology, alone of eleven, minus 0.27963%. The best-to-worst spread narrowed to 2.653669 points, a second consecutive compression from 5.547454. These are exchange-traded fund proxies at tier 2, not the cap-weighted indices, which this book lost a route to in September and has not replaced.
Earnings or guidance:
No company primary release was reconciled for the session, so no earnings number appears here. The loudest named constituent added 4.925746% to 142.72 on 0.9703 times its mean volume, which is to say on no extra volume at all, and finished the entire net move inside the first thirty minutes. A cloud-computing name traded 2.0604 times its mean volume to move 1.652487%, having compounded minus 20.151651% over five sessions. Maximum participation, minimum displacement.
Cross-asset nuance:
Volatility fell 6.12798% to 17.31 whilst bond volatility rose 0.39118%, which is two markets disagreeing about which one is nervous. The three-month volatility measure fell to 18.99, deepening contango to 1.68 points from 1.16, so nothing inverted and nothing was meant to. December crude settled 97.82 after a 6.12 dollar round trip, having been reported at 08:28 on a Middle East risk premium and at 18:45 on hopes of US-Iran diplomacy, which is one commodity carrying two incompatible stories in ten hours. Gold spot lost 0.402568% and December gold 0.420663%, which are two instruments and two numbers. The two semiconductor proxies fell 0.382523% and 0.38289%, a divergence of 0.000367 points, which is the narrowest of the six readings this book holds and the reason it filed a shot on them this morning.
Crypto Market Edge
One Issuer, Ten Passengers, Five Consecutive Outflows The ether complex continues to be a market in name only
Price snapshot:
Bitcoin closed 82,928.50 on the 23:59 UTC mark, up 1.333873%, with a second venue at 82,938.26. Ether closed 2,446.25, up 1.710948%, second venue 2,446.62. Both pairs agreed inside tolerance, which is the dullest sentence in this letter and the reason the rest of it can be trusted.
Flows and positioning:
The bitcoin complex netted 23.2 million dollars: one issuer at 29.9 million, another at 3.6 million, a third at minus 10.3 million, summing exactly. Nine of twelve columns printed a genuine zero on both cache-busted reads. The ether complex lost 26.1 million dollars, a fifth consecutive outflow, the largest issuer at minus 33.0 million against inflows of 3.6 million and 3.3 million.
Leadership and rotation:
Ether’s move magnitude was 1.282692 times bitcoin’s, having been 0.467365 the session before. Four observations, straddling parity, supporting nothing. The largest ether issuer took 82.706767% of the complex’s gross flow, which this book filed a shot on yesterday and which duly obliged on the first scorable session.
Catalysts and roadmap:
A 13 billion dollar 20-year reopening prices today at 13:00 ET against a 5.42 stop and a 2.57 cover on the identical bond in September. Yesterday a 95 billion dollar 6-week bill, the largest single operation of the session, cleared with its stop moving about half a basis point. The loudest thing on the calendar moved nothing at all, and that is the one causal claim this book can make at full strength today.
TL;DR
- Nasdaq advancers beat decliners 2.272421 to one and up volume 3.56207 to one, and the Composite closed 6.0693 points lower anyway.
- Ten of eleven sector proxies rose and the single decliner was technology, which is also where every ounce of index weight happens to live.
- One wire blamed crude’s fall on Iran peace talks at 15:37 and another credited defence gains to the war in Iran at 15:39, two minutes apart.
- A 4.925746% move finished inside thirty minutes on no extra volume, and the wire purporting to explain it arrived 86 minutes later asking what happened.
- High yield closed unchanged at 76.83, inside a band this book pre-registered on 15 October, and that shot is marked a hit today.
Fun Fact
A Calendar That Changed Its Own Time Zone Overnight Yesterday it was New York, today it is Chicago, and nobody announced it
The economic calendar this book reads stated its own time zone as New York on Monday and as Chicago on Tuesday. Nothing else changed. Applying yesterday’s rule to today’s page would have mis-stamped four release times by exactly one hour, which is why the only safe thing to trust on a page is the page’s own account of what it is doing.
Meme of the Day:
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
p.s. There are 3 ways I can help you…
- Option 1: Collect Morning Income
A complete guide to the Premium Popper system.
Written to be clear, concise, and immediately actionable.
>> Learn More Here
- Option 2: Collect Weekly Income
A complete guide to the Tag ‘n Turn system.
>> Learn More Here
- Option 3: Join the Fast Forward Mentorship
>> Join the Fast Forward Mentorship – trade live, twice a week, with me and the crew.
PLUS Monthly on-demand 1-2-1’s
No fluff. Just profits, Tag ‘n Turn Pulse bars, Poppers, and Patterns that actually work.