The Nasdaq 100 lost 2.9% and 6 of the 11 sectors finished higher
 Ahoy there, Trader! ⚓️
It’s Phil…
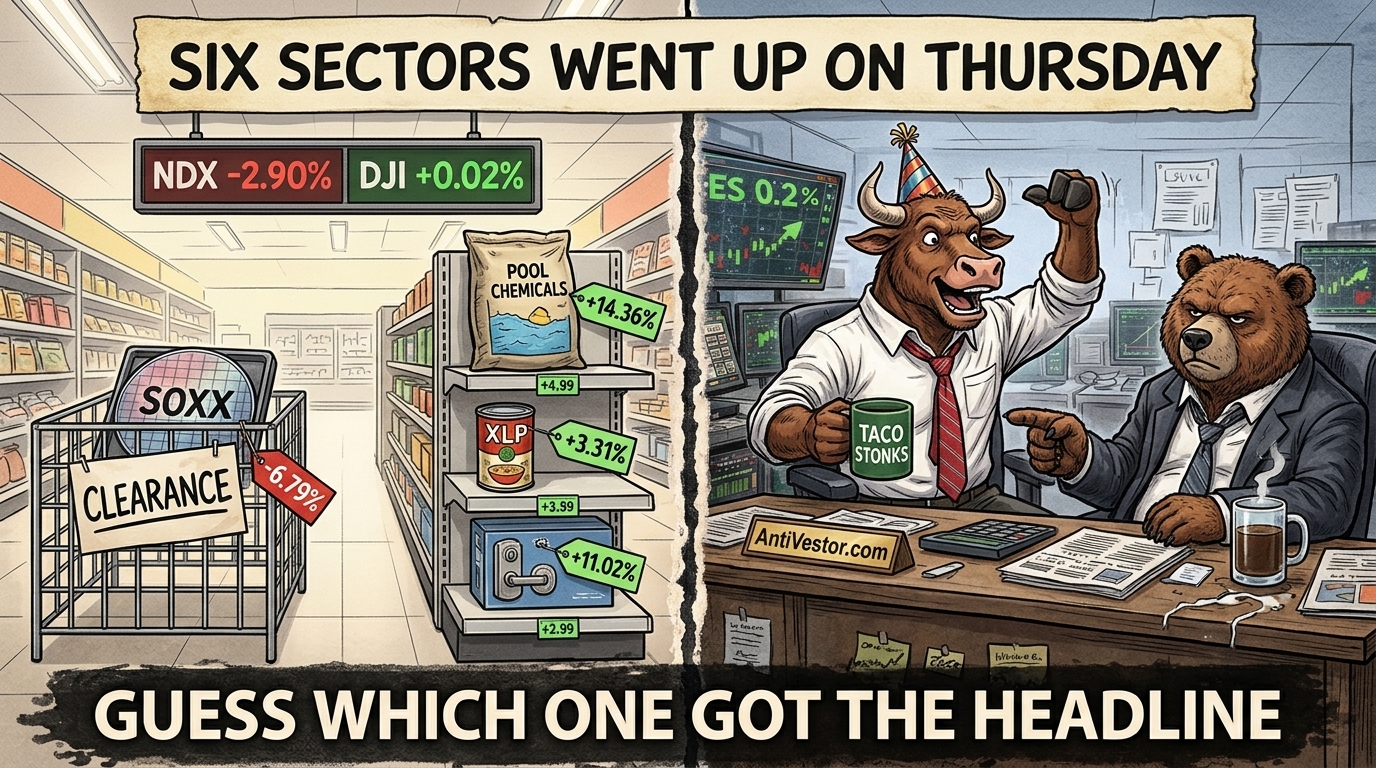
Semiconductors Fell 6.8%, Pool Supplies Rose 14.4%, and the Dow Closed Green The Nasdaq 100 lost 2.9% and 6 of the 11 sectors finished higher
Everybody is going to tell you stocks fell on Thursday. The Dow closed higher. So did the Russell 2000. So did six of the eleven sector proxies, led by consumer staples at 3.31% and utilities at 2.07%.
What fell was one thing, and it fell properly. The iShares semiconductor fund took 6.79%. The VanEck fund took 5.99%. Lam Research took 11.76%, Advanced Micro Devices 8.10%, Meta 6.98%. The deepest of the eleven sectors was technology at 3.29%, which is less than half the iShares fund’s 6.79%. Sectors that behaved like semiconductors on Thursday: 1. Semiconductors.
Pool Corp sells swimming pool supplies and added 14.36%. Lam Research sells the machines that print chips and lost 11.76%. Thursday paid better for chlorine than for lithography.
The index arithmetic simply followed the sector down. The Nasdaq 100 lost 2.90%, its largest daily fall of the thirteen sessions from 6 to 22 October. The Composite lost 2.60%. The S&P 500 lost 1.21%. The Dow gained 0.02%, which is eleven points and change, and nobody is going to write that down.
Here is the part that decides whether Thursday was a warning, and it is what else happened in the same session. The long Treasury fund rose 1.87% on 65,635,115 shares, roughly double each of the three previous sessions. Investment grade rose 1.04%. The ten-year constant maturity fell 17 basis points to 4.96%. Staples, utilities and health care all rose. And high yield, the one instrument whose job is to panic first, rose 0.16%. Read as a price, that is a third rally in a row of them. Read against its own published duration of 3.20 years it is 38.75% of what the long bond’s move implies, which is credit lagging rather than credit cracking, and the spread that would settle which of those it is gets published a day late.
One receipt, because the ledger is the only thing here that can be wrong on the record and twice this month it was. On 9 October this book filed a shot that the two US exchanges would keep disagreeing about breadth, with the falsifier set at fewer than three straddles across ten named sessions. Parts 232 and 233 both said it was more likely than not to be marked a miss. Yesterday’s edition revised that to a coin toss. Thursday straddled: New York counted 1.33 advancers to decliners and Nasdaq counted 0.76. That is the third straddle in nine scored sessions, the falsifier can no longer fire, and the shot is secured. The two editions that leaned against it were this book being wrong about itself in public, which is the only kind of wrong worth printing. One caveat it owes you: the filed ten-session window omits Monday 12 October, which this book has flagged for three editions and has not corrected.
The One That Mattered
The one number is 6.79%, the semiconductor fund, and it is the number because everything else in the session is downstream of it. The index fall is the sector fall with the weightings applied. The staples and the 1.87% in the long bond sat in the same session, and this book holds no equity flow data, so it cannot see money move between them. And the instrument that would settle whether this was a de-risking or a reshuffle, high yield, rose 0.16% and then lagged its own duration, which points two ways at once. Sixty per cent of the index fall was done before the bell and 40.0% of the move has no named cause in this book. Neither leg has one at sector or index scope, and the semiconductor sector’s own 6.79% has no named cause either.
Semiconductors fell 6.8% and six of eleven sectors rose, so was Thursday a de-risking or a rotation? We went down the rabbit hole in today’s Macro Edge. https://antivestor.com/macro-edge
Stock Market Edge
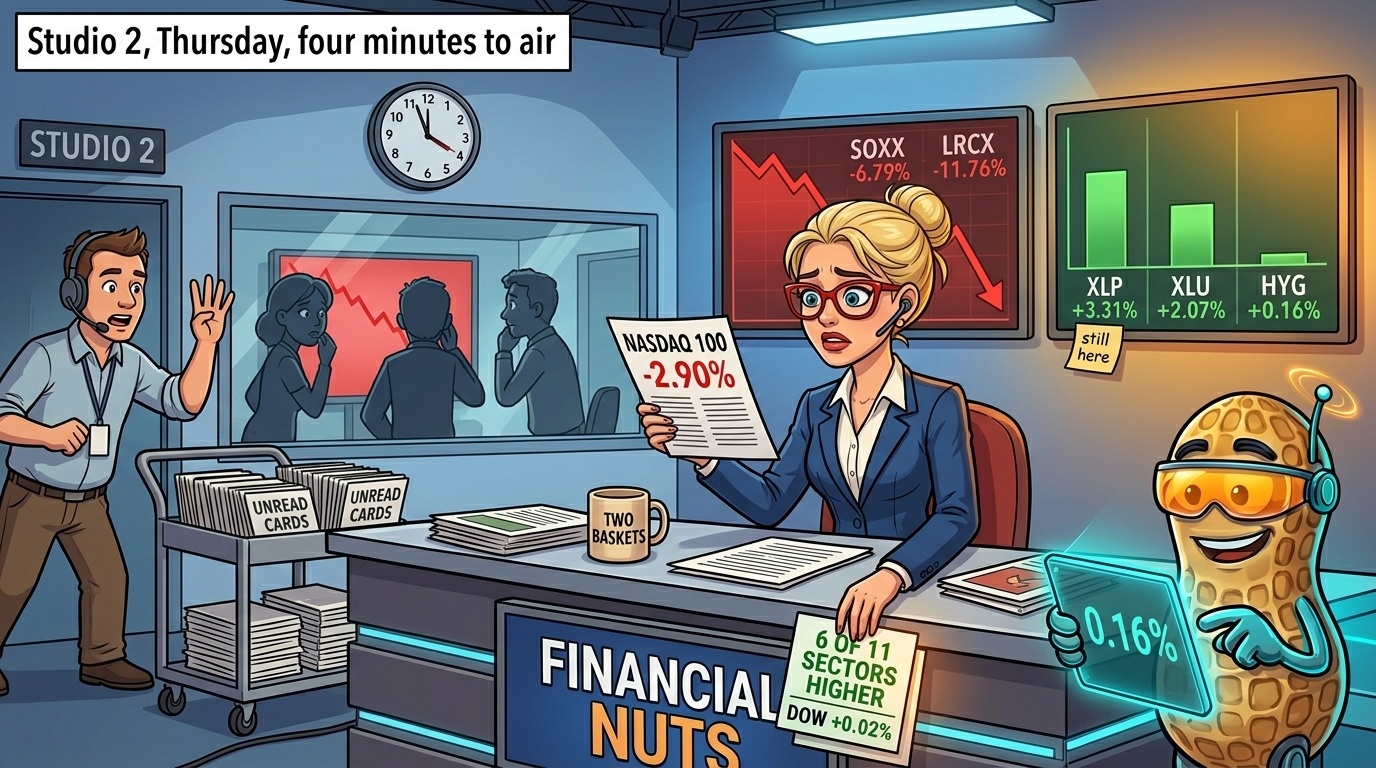
The Chips Took 6.79% and 6 of 11 Sectors Closed Higher New York counted 1.33 advancers to decliners, Nasdaq counted 0.76, both on the same afternoon
Premarket snapshot:
At the 06:45 to 06:50 UTC capture bar, read twice on all four December contracts with the adjacent bar moving on all four between reads, S&P futures sat 7,709.00 and Nasdaq futures 29,231.25, up 0.06% and 0.31%. At the 07:30 UTC re-quote both are lower, 7,698.75 and 29,181.00. Equity volatility reads 19.17 on the 07:15 UTC bar, the first observation after the overnight publication break, against a 19.03 close. Nothing here clears this book’s 1.00% overnight line, and two contracts crossed the 0.30% line in opposite directions on a price drift of under a quarter of one per cent, which is the sort of thing that only matters if you have written the line down.
Sector rotation:
Six of eleven higher, five lower. Staples 3.31%, utilities 2.07%, health care 1.32%, real estate 1.09%, financials 1.09%, materials 0.72%. Against them technology at 3.29% lower, communication services 1.42%, industrials 0.94%, energy 0.87% and consumer discretionary 0.45%. Best to worst spread 6.59 points, which is well past the 4.00 point line that makes this book go and look for a cause rather than assume one. These are tier 2 exchange-traded fund proxies and they partition the S&P 500, not the index that did the falling. The two semiconductor proxies finished 0.80 percentage points apart, and the shot this book filed on 21 October dies if that divergence falls below 0.10 points on four or more of ten sessions: two sessions scored, none of the four in.
Earnings or guidance:
Lam Research opened 234.50 from a 260.81 close and finished 230.15. So 85.8% of its move was the opening gap and 14.2% was the entire session that followed, and its filing went in on 21 October, before the bell. That is the only cause this edition names and it is scoped to Lam Research and nothing else. Meta filed the same night and the arithmetic refuses it: 43.5% gap, 56.5% after the bell, so the majority of Meta’s move arrived after the thing offered to explain it. Pool Corp 14.36% higher, Spotify 11.10%, Allegion 11.02%, Procter and Gamble 5.58%.
Cross-asset nuance:
The barrel and the companies went opposite ways. December Brent settled 113.17, up 4.00%, December WTI 99.47, up 2.39%, and the energy sector proxy closed 0.87% lower. The strike-plan report this book retrieved is stamped 19:11 UTC, forty-one minutes after the December WTI settlement it is being offered to explain, so it is published here as a stamp and not as a reason. No Brent settlement time is held, so the same test is not run on the contract that moved most. Gold went the other way from every other haven: spot fell 2.82% to 4,023.93 whilst the yen gained 0.87%, the franc 0.48% and the long bond 1.87%. Three of those four moved one way and gold moved the other, and no cause for it is named here. Bond volatility rose 11.36% to 106.85 with nothing timestamped before it, and no cause is named for that either. Initial claims printed 194,000 against a 200,000 forecast at 12:30 UTC, which argues for higher yields, and the daily yield change went 17 basis points the other way.
Crypto Market Edge
Wednesday’s Turn Lasted Exactly 1 Session Both assets lower, both flow products reversed, and a shot one session from dying
Price snapshot:
Bitcoin closed 81,350.77 on the 23:59 UTC mark, down 3.16%. Ether closed 2,387.21, down 3.40%. At the 07:30 UTC re-quote both are slightly higher, which is the dullest sentence in this letter and the reason the rest of them are allowed.
Flows and positioning:
US spot bitcoin funds netted minus 635.6 million dollars against plus 524.8 million on Wednesday. Ether funds netted minus 110.6 million against plus 14.9 million. Twelve bitcoin columns and eleven ether columns enumerated, every row reconciling to its own stated total, no row provisional and the asymmetry diagnostic returning a null for a seventh consecutive edition. Both products reversed sign on the same date as both prices fell.
Leadership and rotation:
Against 115.4 million dollars of gross absolute issuer flow the largest ether fund took 65.42%. On 20 October it was 82.71% and on 21 October 39.86%. The shot this book filed on 20 October dies if that share closes below 70.00% on three or more of six scorable sessions, and Thursday is the second of the three. Three scorable sessions accumulated, two falsifier sessions in, one more and it is a marked miss. Stated here rather than described, because a shot nobody can count is not a shot.
Catalysts and roadmap:
The flow table’s earliest row did not move at all: 5 October, exactly where the prior edition left it, against nine consecutive observations of one trading session per edition and a published prediction of 6 October. Anything cumulative is frozen into this edition rather than left to be rebuilt from a table that is eating itself. A two-year note prices on the twenty-sixth, a five-year on the twenty-seventh and a seven-year on the twenty-ninth, and the committee meets on the twenty-seventh and twenty-eighth with no further inflation print in hand. Thursday’s five-year inflation-indexed auction has no published result at all.
TL;DR
- Semiconductor proxies fell 6.79% and 5.99% whilst six of eleven sector proxies closed higher, and the worst actual sector was technology at 3.29%.
- The Nasdaq 100 lost 2.90%, its largest daily fall of the thirteen sessions from 6 to 22 October, and the Dow closed 0.02% higher on the same afternoon.
- High yield rose 0.16% and the long Treasury fund 1.87% on double volume, which is a rotation signature on the tape rather than a de-risking one.
- December Brent settled 4.00% dearer whilst the energy sector proxy fell 0.87%, and the strike report this book holds is stamped after the settlement.
- Gold spot fell 2.82% whilst the yen, the franc and the long bond all rose, which makes it the only haven that went the other way.
Fun Fact
The Count and the Index Do Not Count the Same Things One of them includes warrants. The other threw them out on purpose.
The advancing and declining issue counts this book quotes for Nasdaq cover every listed issue on the exchange, which means warrants, rights, units, preferred shares and exchange-traded funds are all in there voting. The Composite index built on that same exchange deliberately excludes all of them. The two numbers sit side by side every session, describe different populations, and are routinely subtracted from one another by people who should know better.
Meme of the Day:
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
p.s. There are 3 ways I can help you…
- Option 1: Collect Morning Income
A complete guide to the Premium Popper system.
Written to be clear, concise, and immediately actionable.
>> Learn More Here
- Option 2: Collect Weekly Income
A complete guide to the Tag ‘n Turn system.
>> Learn More Here
- Option 3: Join the Fast Forward Mentorship
>> Join the Fast Forward Mentorship – trade live, twice a week, with me and the crew.
PLUS Monthly on-demand 1-2-1’s
No fluff. Just profits, Tag ‘n Turn Pulse bars, Poppers, and Patterns that actually work.