Tuesday’s tape said nothing happened. Tuesday’s internals disagreed.
 Ahoy there, Trader! ⚓️
It’s Phil…
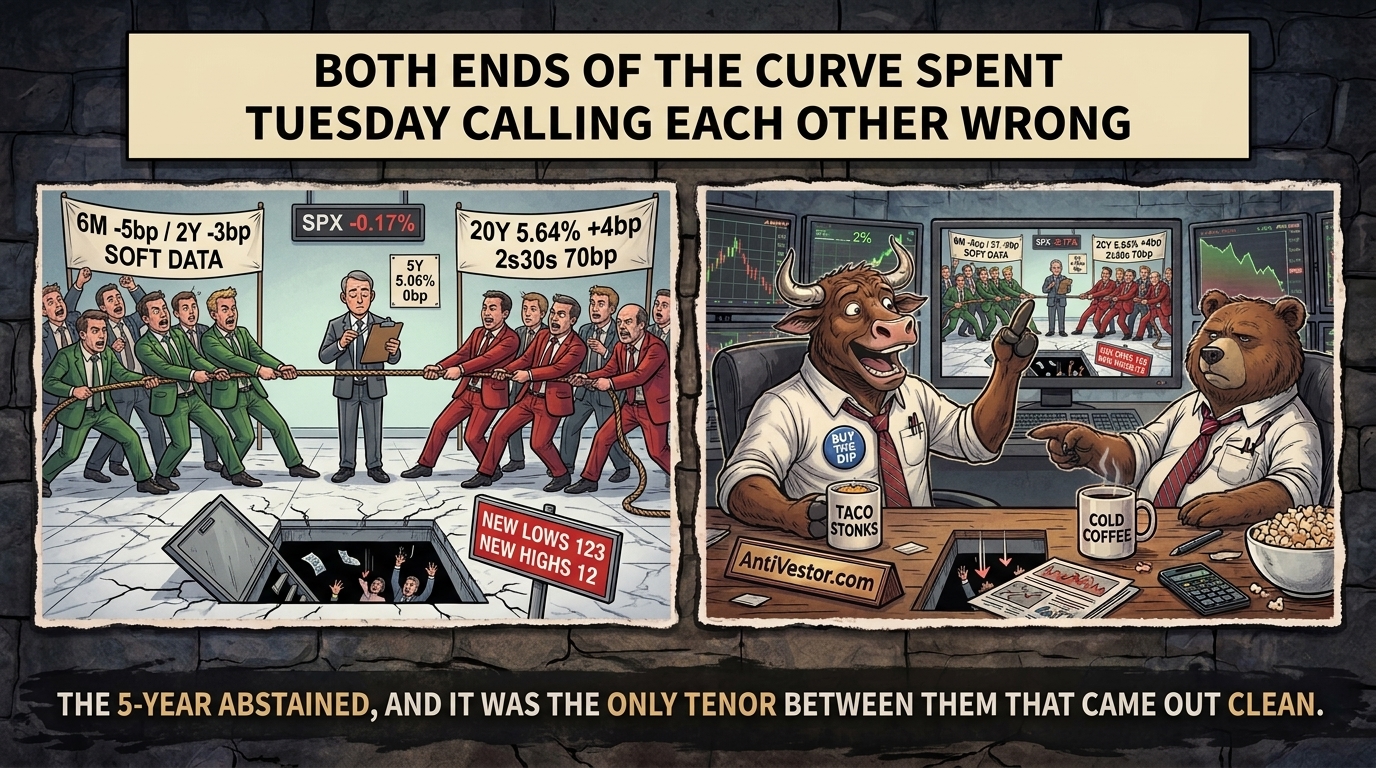
Both Ends of the Curve Had an Argument. The Middle Abstained. Soft data at the front, dearer money at the back, 0 in between
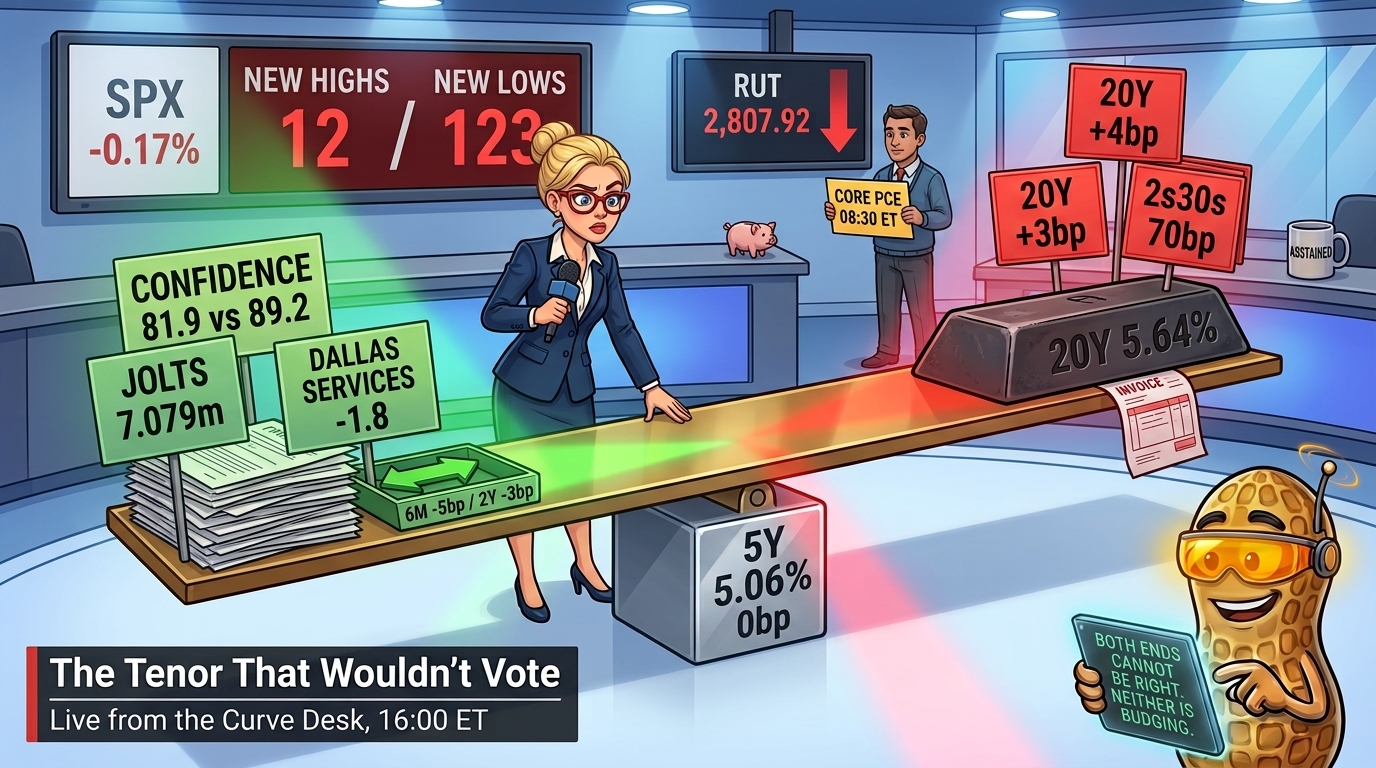
Consumer confidence came in at 81.9 against 89.2 expected, which is the sort of miss that normally gets a paragraph of its own. Job openings fell for a third consecutive month. The front end of the Treasury curve took both prints entirely at face value: the 6-month richened 5 basis points, the 2-year 3, and everything from the 2-month out to the 3-year rallied like a market that had just been given permission to relax.
The long end considered the same information and cheapened. The 20-year went to 5.64%, the 30-year to 5.59%, and 2s30s widened from 64 basis points to 70. Two halves of one instrument, reading one data set, reaching opposite conclusions before the close.
And between them the 5-year moved 0. Not a rounding-down zero. Unchanged, 5.06% to 5.06%, the tenor where the two arguments met and cancelled exactly. The 1-month and the 1.5-month also printed 0, but they had nothing to cancel.
The S&P 500 logged this as a 0.16724% day, which is the market equivalent of a shrug. Underneath the shrug, 123 NYSE issues made new lows against 12 new highs, and the Russell 2000 closed 2,807.92, its lowest close of the quarter. Core PCE lands at 08:30 ET, sharing one timestamp with fifteen other releases.
The One That Mattered
The tape spent Tuesday looking calm, and it had every reason to. Two soft prints, a front end rallying, a volatility index that finished at 16.04 and barely moved. But the number worth keeping is the 0 on the 5-year, because it is the point on the curve where both stories were priced at once and cancelled: a gentler Fed at the front, dearer money at the back, and one tenor where the two exactly offset. Markets do not usually hold two incompatible views that neatly. When they do, the middle is where the fight is, not where the peace is.
If the front end believed Tuesday’s data and the long end ignored it, why did the equity market side with the long end? We went down the rabbit hole in today’s Macro Edge.
Stock Market Edge
The 5-Year Was the Pivot and It Did Not Move The front end rallied, the long end sold off, and the pivot printed 0
Premarket snapshot:
December ES traded 7,739.00 on the 06:30:00 to 06:34:59 UTC five-minute bar, captured at 07:30 UK, read twice past its close and byte-identical both times, up 0.0905% on Tuesday’s 7,732.00 settlement. December NQ was down 0.1494%, December YM up 0.3075%, December RTY up 0.1697%. Cash closed 7,670.84 and the overnight ran 7,738.00 to 7,755.75, never once below the settlement, which is the most committed thing the S&P contract did overnight.
Sector rotation:
Seven of the eleven cap-weighted sectors fell. Energy led lower at 0.9018%, materials 0.7479%, staples 0.5226%. Technology finished at minus 0.0154%, which is negative in the same way a rounding error is negative. Utilities added 1.172% on a session when the price of long money went up, and a bond proxy that outperforms into higher long yields has stopped being a bond proxy and started being a power company.
Earnings or guidance:
No results landed after Tuesday’s close, so the calendar’s entire contribution was anticipation. Micron, Jabil, FactSet, Conagra and Cal-Maine all report today. Consensus has Micron at 50.9 billion dollars of revenue.
Cross-asset nuance:
The dollar added 0.20%, three-quarters of it the euro, on a six-leg rebuild that closes to within 3%. Volatility closed 16.04, down 0.19%, having watched all of the above.
Crypto Market Edge
847,666 Coins, and 1 That Nobody Bought Bitcoin added 148 dollars whilst the money behind it kept leaving
Price snapshot:
Bitcoin closed 83,624.47, up 0.1779%, which is 148 dollars, and two independent exchange routes agreed to within 0.0167%. Ether closed 2,676.76, down 0.4159%. On a day when November crude moved 3.4773% and the Russell closed the quarter at its floor, the asset class that exists to have opinions declined to have one.
Flows and positioning:
Ether funds posted a net outflow of 2.8 million dollars, complete across all eleven issuers on two independent reads and the first negative session since 17 September. The bitcoin table printed 66.2 million with eight of twelve issuer cells simply blank, both Grayscale vehicles among them. We are not scoring that. The last row that looked like it published 32.4 million and completed five days later at 346.9 million.
Leadership and rotation:
Bitcoin, ether, XRP, Solana and Dogecoin held no place at all in the crypto-only or all-asset top 25 at the 06:33 UTC capture, a second consecutive session. Before anyone declares retail has left, four of the five carry a high normalised message-volume reading somewhere in their series. The chatter is there. The ranking simply has better things to do, which this morning meant a gold token with 432 followers.
Catalysts and roadmap:
Strategy paid 85,681 a coin for 1,665 coins in a week bitcoin closed at 83,624. Holdings now read 847,666 against last week’s 846,000, and 846,000 plus 1,665 is 847,665.
TL;DR
- Confidence fell 6.7 points to 81.9 and job openings fell a third month, so the front end rallied by up to 5 basis points whilst the 20-year cheapened 4 regardless.
- The 5-year finished exactly where it started at 5.06%, the pivot between a rallying front end and a cheapening long end, where the two exactly cancelled.
- The index lost 0.16724% and called it quiet, whilst 123 NYSE issues made new lows against 12 new highs and the Russell closed the quarter at its floor.
- Utilities led the board at 1.172% on a day long yields rose, which is either a broken bond proxy or an electricity bill nobody has finished pricing.
- Bitcoin added 148 dollars, ether funds went negative for the first time in 8 sessions, and Strategy paid 2.5% above the market for its weekly coins.
Fun Fact
A 200 Million Dollar Gas Plant, Fuelled Entirely by Pigs In a town called Turkey
On 15 September a renewable-gas operator opened a 200 million dollar facility in Turkey, North Carolina, which captures methane from hog manure and converts it into renewable natural gas and grid power, under long-term agreements with over 80 farming locations covering more than 415,000 hog spaces. The leftover is biochar. Turkey the town, hogs the fuel, biochar the remains.
Meme of the Day:
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
p.s. There are 3 ways I can help you…
- Option 1: Collect Morning Income
A complete guide to the Premium Popper system.
Written to be clear, concise, and immediately actionable.
>> Learn More Here
- Option 2: Collect Weekly Income
A complete guide to the Tag ‘n Turn system.
>> Learn More Here
- Option 3: Join the Fast Forward Mentorship
>> Join the Fast Forward Mentorship – trade live, twice a week, with me and the crew.
PLUS Monthly on-demand 1-2-1’s
No fluff. Just profits, Tag ‘n Turn Pulse bars, Poppers, and Patterns that actually work.