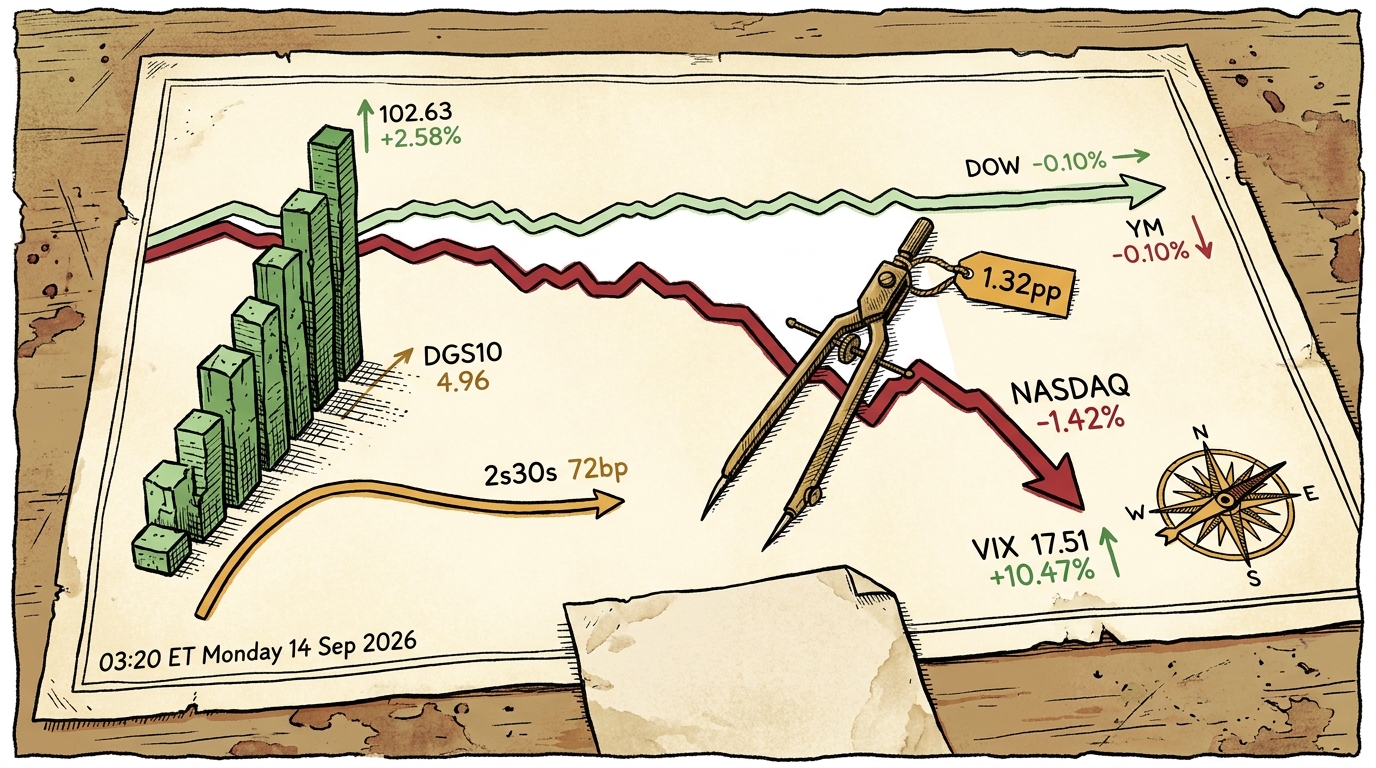
A committee sits down to set a rate the market moved past four sessions ago
⚓ Weathervane. The wind still comes from the long end. The policy rate has been frozen at 3.50% to 3.75% since July whilst the term premium does the tightening, and the price of long money is now set by deficits, issuance supply and a synchronised global duration bid rather than by the committee. Higher-for-longer has stopped being a Fed decision and become a bond-market fact. The cruise ship is holding this heading, and this morning is the clearest confirmation it has had.
 Ahoy there, Trader! ⚓️
It’s Phil…
The turn condition still stands at nought of two. Wednesday is the first dated Federal Reserve communication since the blackout began on 5 September, and so the first chance in over a week to test the banner rather than carry it.
Who is setting the price of money now, the committee that meets tomorrow or the ten-year that has already moved?
The surface read on Monday was artificial intelligence. Two frontier firms asked the industry to slow capability growth, one conceded its listing would slip, the semiconductor index lost roughly 5.9%, and most desks filed that before lunch. It is a good story and the numbers in it are real.
What actually happened is that the ten-year took twenty-one basis points across four sessions and printed 5.041% at 04:02 this morning, the highest since 2007. It has not closed above 5% since July of that year, and by mid-morning it had slipped to 4.9895%, so the level is contested rather than settled. Gold fell 1.51% on Monday to a five-week low, the dollar reached a two-week high, and the thirty-year sat near 5.33%.
Trace those together. If the metal falls whilst a supply shock is live and the currency firms at the same time, the move is driven by real yields rather than by fear. That is a term premium story with energy pass-through behind it, not a policy-path story.
Here is where it gets awkward. The textbook has the central bank setting the short rate whilst the curve prices expectations of what it does next, which makes the long end downstream. The tape shows a long end repriced 104 basis points above the range the committee is expected to set on Wednesday, and it got there whilst the committee was contractually silent. Mr Market did not anticipate the Fed. He overtook it.
So what is a hike for in that world. One answer is ratification. Another is that a committee which does not move risks the long end doing more of the work, less politely. Which of those Wednesday represents is not something we can settle from here, and the projections are the document most likely to say.
Phil’s Musing
The bit I keep circling is the direction of causation. I have spent years assuming the committee leads and the curve follows, and for four weeks the curve has been out in front. If that holds through Wednesday, the useful question stops being what the Fed will do and becomes what the bond market will let it do. That is slower and less comfortable than a rate call, and it is the lean I would take.
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
P.S. – Phils Footnote I got Monday wrong in a small way that bothers me. I read the semiconductor fall as the day’s event because it was loudest and came with a narrative attached. The larger number had no press release, so it took me until this morning to look at it properly. Wall Street often says the market is a discounting machine. Nobody mentions that it discounts in whichever market you are not watching.