The implied gap is the steepest in 44 sessions and nothing that steep has fully reversed
 Ahoy there, Trader! ⚓️
It’s Phil…
Both Fear Gauges Fell on Wednesday and Volatility Is 10.6% Higher Before the Open The implied gap is the steepest in 44 sessions and nothing that steep has fully reversed
Wednesday handed the market a five-star review. The Nasdaq 100 added 1.1%, the S&P 0.6%, the Dow 0.7%. Both fear gauges came down, equity volatility 3.6% to 16.68 and bond volatility 5.7% to 95.9, its biggest single-session fall of the nine we hold. Technology led the eleven sectors and was the only one above 1%. The two exchanges did disagree about who turned up, New York with slightly more fallers than risers and Nasdaq the other way round, but the review got framed and hung in the window regardless.
Then the kitchen caught fire.
By 09:15 UTC equity volatility was 18.44, up 10.6% on the close. December Nasdaq futures were 1.9% lower, having been 1.6% lower at the 07:30 UK capture and deeper on every read since. December Brent was 112.03, up 2.9%, and WTI up 2.5%. On the same-index basis that Nasdaq contract implies a cash open around 29,257, a hole of 565 points, or 1.9%, which is steeper than any opening gap in the 44 sessions from 20 August to 21 October. Not second steepest. Steepest. Bond volatility has no premarket series, so anybody telling you the whole of Wednesday has been unwound is describing two legs and calling it four.
Here is the part worth the stamp. A gap this size does not get fully reversed. Of the 22 sessions in that window that opened lower, four closed above the prior close, and the steepest of those was 24 September at 0.8%, less than half this morning’s. Twenty-two observations, no counter-example. What a gap this size does get is clawed back, by amounts that run from almost nothing to almost everything: 15 October opened a shallower hole and recovered 96% of it by the close; 1 September recovered 5%. Same setup. So the direction is close to settled and the size is anybody’s, and this book is at least telling you which half it is guessing.
Now the why, and we are going to do something we normally refuse. Speculation follows. None of it is a retrieved cause. A future edition confirms or buries it. The candidates with timestamps: Meta, reported up 4% at 05:33 UTC on a revenue beat and by 09:00 being offered as the reason the whole complex is lower; Tesla, reported down about 3% from 05:49; Brent, 2.9% dearer; French bonds, tumbling in the same 08:38 headline, with no level held here. And then the clock turns on the first of them. December Nasdaq was already 1.8% lower by 08:05, which is 98% of the eventual move. The Meta story arrived after the thing it explains. Experts have since confirmed the cause of the fall, eleven reasons, each confirmed by a different expert.
One receipt, because the ledger is the only thing here that can be wrong on the record, and yesterday it was. This book made Tuesday’s 2.11 breadth reading sound like an event, leaning on a base rate of thirty-two sessions with nothing above 2.0, whilst noting in the same breath that a four-week stretch had never been pulled. This morning it was pulled. 15 October printed 3.03. The refusal held. The frame around it did not.
The One That Mattered
Wednesday priced calm on both fear gauges and the Nasdaq 100 took 1.1%. Thursday’s premarket has volatility 10.6% higher, the futures 1.9% lower and Brent 2.9% dearer, which is a five-star review arriving after the kitchen has shut and the bill turning up on a bike. The hole implied at the open is the steepest in 44 sessions, nothing that steep has closed green in that window, and the five steepest clawed back anywhere between 2% and 96% of it by the bell.
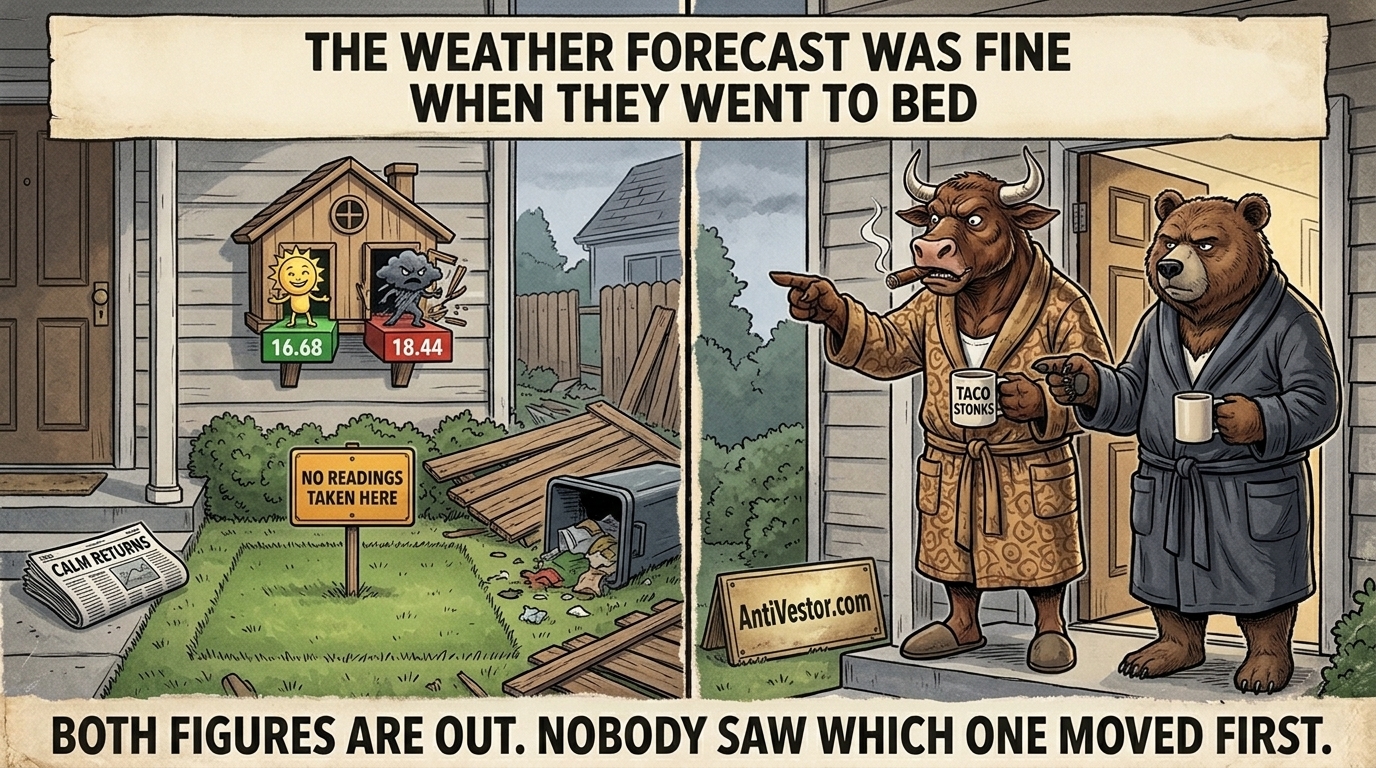
If both volatility measures fell on Wednesday and equity volatility is 10.6% higher before Thursday’s open, which of those two prices was wrong? We went down the rabbit hole in today’s Macro Edge. https://antivestor.com/macro-edge
Overnight Excitement
December Nasdaq futures 29,442.0 on the 09:20 to 09:24:59 UTC bar, down 1.9% from a 30,007 settlement, which clears this book’s 1.0% line by 0.9 points and its 1.5% line by 0.4, and falls 0.1 short of the 2.0% mark where a figure becomes a story in its own right. December S&P futures crossed the 1.0% line on the way to minus 1.1%. Dow minus 0.7%, Russell minus 0.9%. All four read twice at the capture, byte-identical, and all four lower on every read since.
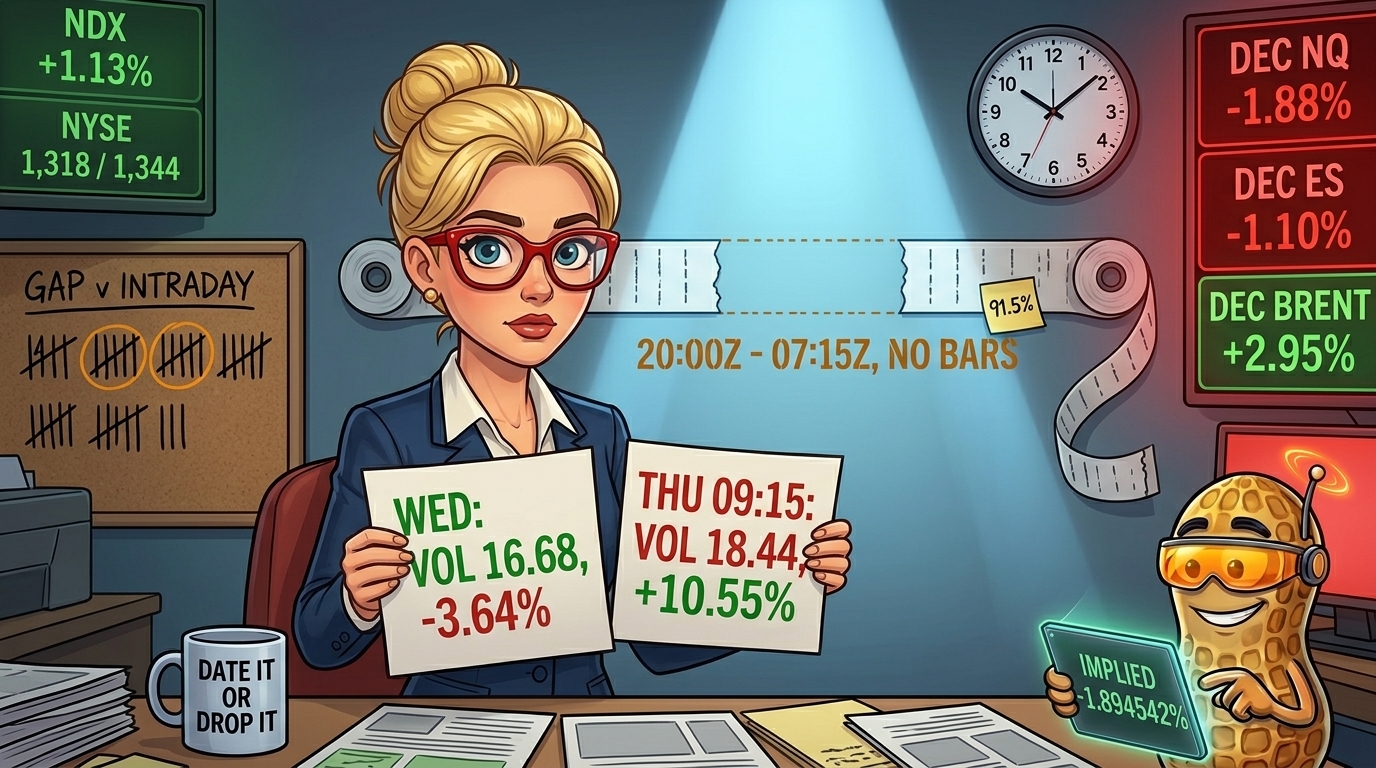
Equity volatility moved most and cannot be timed. The premarket series reads 18.44 on the 09:15 UTC bar, high 18.57, low 18.18 across nine fifteen-minute bars. But nothing publishes from 20:15 UTC on Wednesday to 07:15 UTC on Thursday, and the first bar after that eleven-hour hole opens at 18.29. So 1.61 of the 1.76 points, 91% of the move, happened where there are no observations. Things that happened in the dark this month: 1. The bit that mattered.
Stock Market Edge
Wednesday’s Calm Has Been Repriced 10.6% Dearer Before the Bell New York counted 0.98, Nasdaq counted 1.28, and the premarket is undoing both
Premarket snapshot:
At the 07:30 UK capture December S&P futures sat 7,728.25, minus 0.9%, and December Nasdaq 29,512.25, minus 1.6%. Re-quoted at 09:25 UTC every contract is lower: S&P 7,714.75 at minus 1.1%, Nasdaq 29,442.0 at minus 1.9%, Dow 52,695 at minus 0.7%, Russell 2,768.8 at minus 0.9%. The growth end is taking the most of it, which is Wednesday’s ordering read backwards. The implied 565-point hole has a base rate: of the 22 down gaps in the window, four closed green, on 26 and 31 August and 2 and 24 September, and the steepest of those was 0.8%. The five steepest down gaps recovered 96% of the gap on 15 October, 63% on 13 October, 49% on 14 September, 5% on 1 September and 2% on 10 September.
Sector rotation:
Seven of eleven higher and four lower. Technology 1.7%, industrials 0.9%, financials 0.6%, utilities 0.3%. The fallers are communication services minus 1.1%, real estate minus 0.8%, staples minus 0.7% and health care minus 0.5%, so the worst of them is the one that is not a defensive. Consumer discretionary at 0.03% is three cents on a fund that closed 115.53. These are tier 2 proxies and they partition the S&P 500, which is not the index this morning’s futures are about.
Earnings or guidance:
No company primary release was reconciled for a figure, so no earnings number appears and no fiscal period is named, a trap this book has walked into four editions running and is declining to walk into a fifth. Five reporters are confirmed on filings dated 21 October. Dell’s 5.3% is the one move with a clock behind it: a product release at 11:50 UTC and a gap that was 145.7% of the whole net move, because the rest of the day took 45.7% of it back.
Cross-asset nuance:
The newest published curve is still 20 October, and Treasury has filed no result at all for Wednesday’s 13 billion dollar 20-year reopening, against a 5.42 stop on the identical bond in September. Seven result fields, all empty. On that 20 October cross-section the 20-year still holds the maximum of all fourteen tenors at 5.47. December WTI settled 97.15, minus 0.7%; December Brent 108.82, plus 0.03%. The two crudes finished Wednesday on opposite sides, so anybody writing that crude fell was right about one of them. Then both went up a great deal more than either moved on Wednesday: Brent 112.03 at the 09:20 UTC re-quote, plus 2.9%, WTI 99.56, plus 2.5%, the spread widening from 11.67 to 12.47. Weekly inventories landed at 14:30 UTC, four and a half hours after WTI’s 100.40 high of the full trade date, and a wire called crude a 5-week high at 10:45 UTC, inside the hour of that high, after which the contract travelled 4.14 dollars lower by the afternoon.
Crypto Market Edge
1 Fund Stopped Being the Whole Market and the Market Noticed The ether complex turned positive whilst its largest member kept walking out
Price snapshot:
Bitcoin closed 84,008.52 on the 23:59 UTC mark, up 1.3%. Ether closed 2,471.18, up 1.0%. Both pairs agreed inside tolerance on two routes, which is the dullest paragraph in this letter and the only reason the exciting ones are allowed.
Flows and positioning:
US spot bitcoin funds netted 524.8 million dollars, a third consecutive inflow, twelve issuer columns counted and the row summing to its own total. The ether complex took 14.9 million and ended five consecutive outflows. The largest ether fund was minus 29.3 million on the session the complex turned positive. Two other funds carried it. The headline and the biggest fund in the headline are pointing opposite ways.
Leadership and rotation:
Against 73.5 million dollars of gross issuer flow the largest ether fund took 39.9%, down from 82.7% the session before. This book filed a shot on Tuesday that dies if that share closes below 70% on three or more scorable sessions out of six. Tuesday was the first at 82.7%. Wednesday is the second, and at 39.9% it is the first session under the line. Two of six scored, one of the three it needs to be killed. Not a comfortable position, and the threshold, the count and the direction are all stated here rather than described.
Catalysts and roadmap:
A 26 billion dollar 5-year inflation-indexed auction prices today at 13:00 ET against a 1.96% prior real yield. The committee meets 27 and 28 October with no projection round and no inflation print in hand. Flow-table truncation ate exactly one more trading session, so any cumulative figure is frozen into this edition rather than left to be rebuilt later.
TL;DR
- Both volatility measures fell on Wednesday, equity 3.6% to 16.68 and bond 5.7% to 95.9, and equity volatility reads 18.44 before the open, up 10.6%.
- December Nasdaq futures went from 1.6% lower at the 07:30 UK capture to 1.9% lower by 09:25, and the S&P contract crossed 1% on the way.
- The implied Nasdaq 100 open is a 565-point hole, steeper than any opening gap in the 44 sessions from 20 August to 21 October.
- The steepest down gap to close green in that window was 24 September’s 0.8%, under half this morning’s, so a full reversal has no precedent at this size.
- 91% of the volatility move landed inside an 11-hour break in the series with no bars in it, so the level is measured and the minute is not.
Fun Fact
A Fund Page Where the Address Bar Outranks the Words Ask for high yield with the wrong 6 digits and it hands you investment grade, identically
The fund factsheets this book reads are addressed by a six-digit product number and a human-readable name, and only the number does any work. Ask for the high-yield fund using the investment-grade number and the page returns the investment-grade duration and spread, to the decimal, with the high-yield name still sitting in the address exactly where you left it.
Meme of the Day:
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
p.s. There are 3 ways I can help you…
- Option 1: Collect Morning Income
A complete guide to the Premium Popper system.
Written to be clear, concise, and immediately actionable.
>> Learn More Here
- Option 2: Collect Weekly Income
A complete guide to the Tag ‘n Turn system.
>> Learn More Here
- Option 3: Join the Fast Forward Mentorship
>> Join the Fast Forward Mentorship – trade live, twice a week, with me and the crew.
PLUS Monthly on-demand 1-2-1’s
No fluff. Just profits, Tag ‘n Turn Pulse bars, Poppers, and Patterns that actually work.