Friday’s sell-off and Monday’s rally each traded about 736m shares in falling stocks. Monday added 134m in rising ones.
 Ahoy there, Trader! ⚓️
It’s Phil…
The S&P 500 Rose 0.7% and 55% of New York’s Volume Went the Other Way Friday’s sell-off and Monday’s rally each traded about 736m shares in falling stocks. Monday added 134m in rising ones.
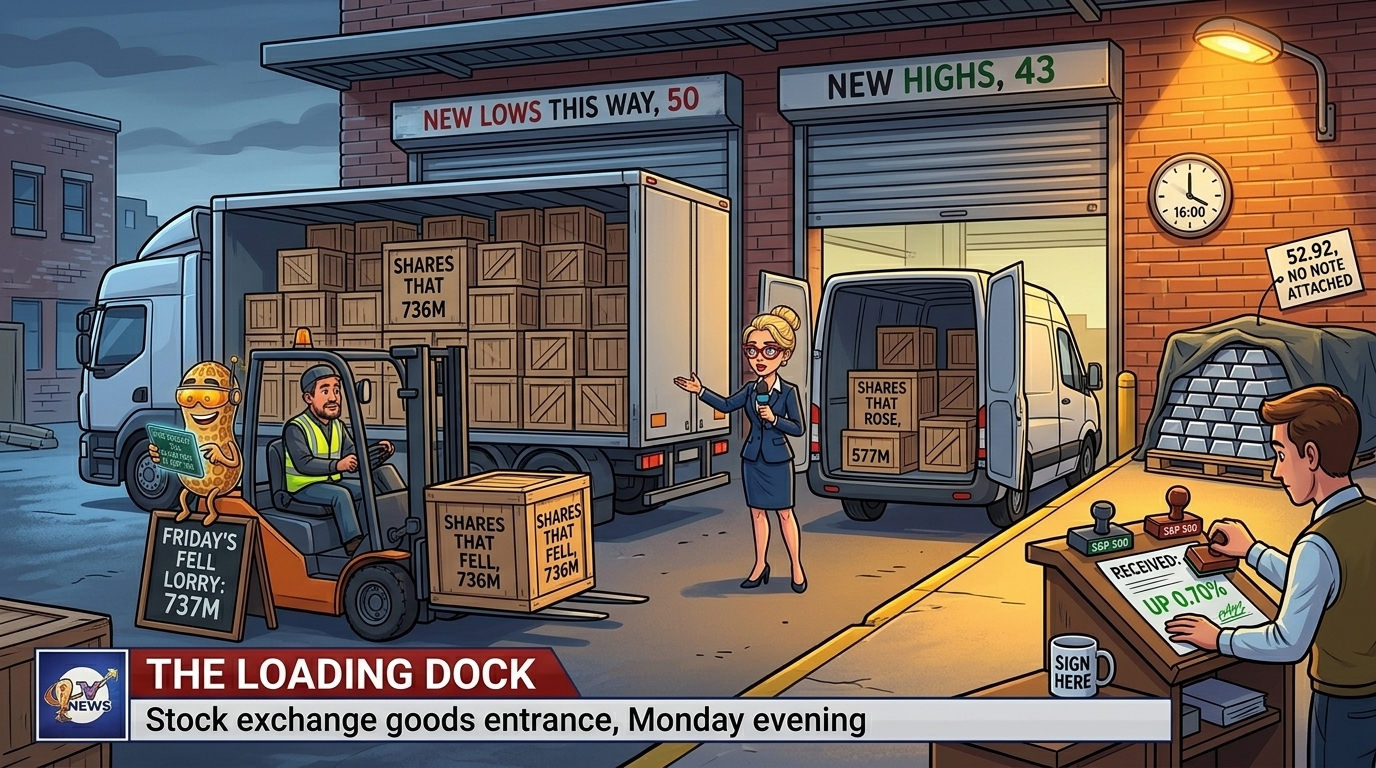
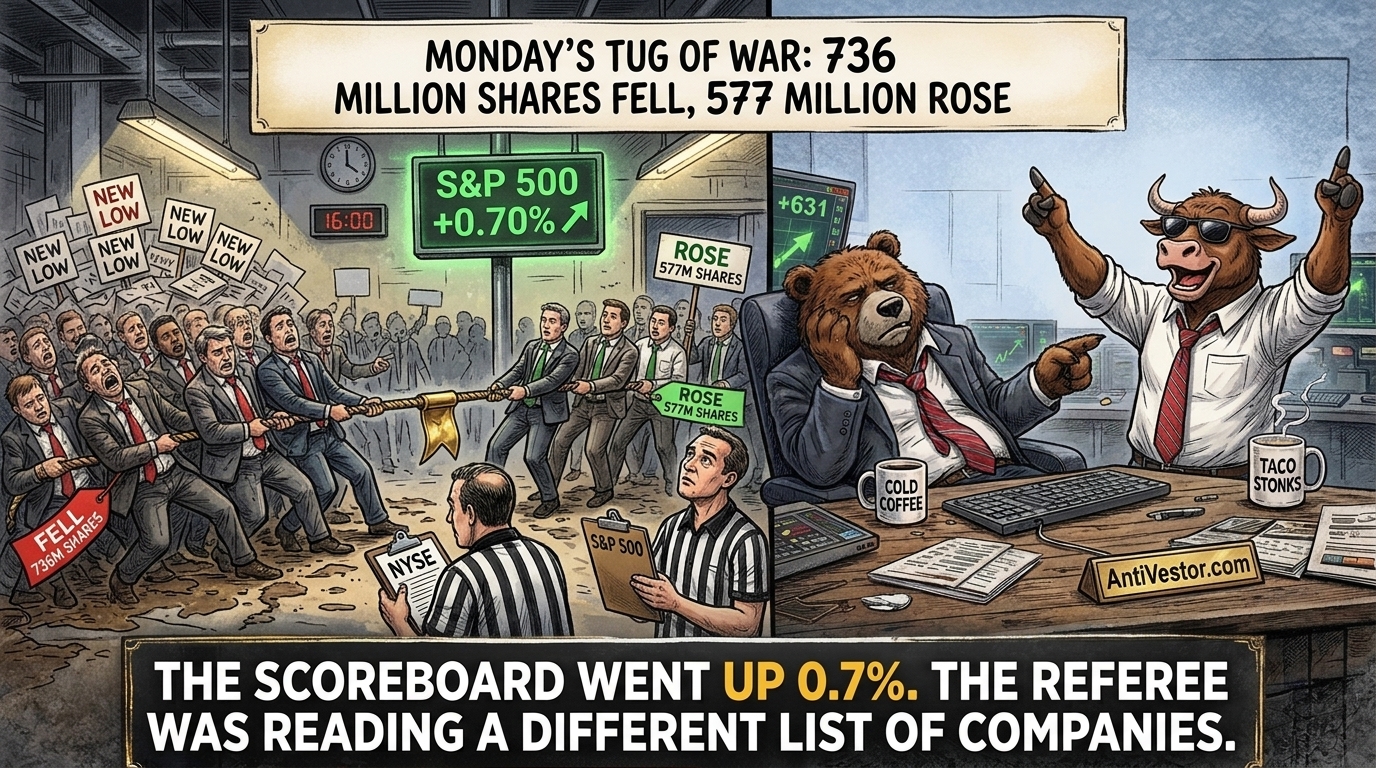
On Friday the New York Stock Exchange traded 737 million shares in stocks that fell, and the market fell. On Monday it traded 736 million shares in stocks that fell, and the market rose 0.7%. Friday had 973 risers to 1,691 fallers; Monday had 1,400 to 1,273. The volume in rising stocks was 134 million shares higher on Monday, 577 million against 443 million, and the index called that a rally. Every share that trades has a buyer and a seller, so this book will not tell you who was doing which.
Scorecard. Rose: 1,400 issues. Fell: 1,273. Shares traded by the ones that fell: 736 million. Shares traded by the ones that rose: 577 million. New lows: 50. New highs: 43. Winner, on points: the index.
The index is a different list of companies from the exchange tape, and this book holds nothing that joins the two, so it will not tell you that the fallers were small and the risers were large, however much the shape invites it. It can tell you the Nasdaq 100 rose 1.1%, the chip funds 2.9% and 2.7%, health care closed to the cent where it closed on Friday, and 125 Nasdaq stocks made a one-year low on the way up.
Now the why. First the test: 69.82% of the S&P 500’s rise and 70.23% of the Nasdaq 100’s came after the open, and nothing stamped inside the session carries that leg. 70% of the move has no named cause in this book.
Speculation, not a cause
Speculation follows. None of it is a retrieved cause. A future edition confirms or buries it. Anthropic filed to go public, and the earliest wire stamp this book holds is 13:22 UTC, eight minutes before the bell. The clock lets it in. The size does not: a filing stamped before the open can be tied to the gap, which was 30% of the move, and to nothing after it.
End of speculation. The rest are refusals. Microsoft closed 1.54% higher on a day a buyout headline crossed at 16:49 UTC and technology rose 1.69%, which is the sound of a loud thing beside nothing. Meta fell 1.88% on twice Friday’s volume; the stamps this book holds on its stock-offering plan run from 13:11 UTC, but it holds no intraday path for the shares, so the test cannot be run and no cause is named. Tesla rose 5.21%; the Barclays upgrade this book holds only on a midday wrap is not the cause. The Brazilian broker XP fell 48.4% the day after an election and the S&P 500 did not look up.
One receipt. Somebody will tell you today how Monday’s 2-year auction went. The Treasury’s own results feed, read this morning, carries no record of it, no yield, no cover, no shares. Until that feed has a row, this book has no auction, and it would rather print nothing than print a wire’s adjective. The 2-year did close 1 basis point lower. The 6-month closed 5 higher. The 20-year, top of the curve for a 32nd session, closed 2 lower, two days before the people who set the overnight rate say anything at all.
In a world where the committee has said nothing since the 14th, one statement lands Wednesday at 18:00 UTC. Rated: Hold.
Oil settled 101.76 on the December contract, down 1.46%, through five wires about diplomacy in Tehran that this book cannot test against a barrel path it does not hold, and read 102.40 before the open. Gold spot closed 4,016.52. December silver settled 54.34 and read 52.92 on the 08:25 UTC bar, 2.61% lower, with nothing stamped in front of it. Bitcoin marked 80,040.16, seven dollars and sixty cents short of doing nothing, and was 79,668.93 by breakfast.
The One That Mattered
The one number is a pair: the S&P 500 rose 0.70% and 55.29% of the New York Stock Exchange’s volume traded in falling shares. Friday’s sell-off and Monday’s rally each had about 736 million shares trade in fallers; Monday had 134 million more trade in risers, and 0.7% more on the index. The count of risers agreed with the index. The volume and the new-low tally did not. This book cannot see who bought or who sold, so it will not use any word with a mechanism folded inside it. It can tell you three breadth measures voted and one of them agreed with the price.
If 55% of Monday’s New York volume traded in falling shares, what exactly went up? We went down the rabbit hole in today’s Macro Edge. https://antivestor.com/macro-edge
Stock Market Edge
736 Million Shares Traded in Fallers, 577 Million in Risers, and the Scoreboard Said 0.7% A 3.26 point sector spread, a 32nd session of the 20-year on top, and a premarket that drifted back under the band
Premarket snapshot:
On the 07:45 to 07:50 UTC capture bar, read twice on all four December contracts, S&P futures were 7,706.00, down 0.11% on Monday’s settlement, Nasdaq futures 29,329.25, down 0.37%, Dow futures 52,566, up 0.03%, Russell futures 2,793.1, down 0.16%. The S&P contract ran 7,702.75 to 7,731.00 since the Monday reopen. Equity volatility closed 18.39, down 5.45%, and the 07:15 UTC global-hours bar read 18.42, so the premarket fear gauge exists after all and had nothing to say. Re-quoted on the 08:20 UTC bar, every contract sat within 0.09% of Monday’s settlement; by then none of the four was inside the 0.3 to 0.6% overnight band, and only the Nasdaq contract had been.
Sector rotation:
Seven of eleven sector proxies rose, three fell. We asked the health care sector what it did on Monday. It closed at 179.28. We asked what it did on Friday. 179.28. Technology 1.69%, industrials 1.42%, discretionary 1.03%, real estate 0.54%, energy 0.45% on a day the barrel fell; communication services 1.57% lower, staples 0.34% lower. Spread 3.26 points, inside the 4.00 line, on proxies that partition the S&P 500. The semiconductor funds rose 2.85% and 2.74%, 0.12 points apart, above the 0.10 line of the shot filed on 21 October: four sessions scored, none against it. New York counted 1,400 advancers to 1,273 decliners and the Nasdaq 2,555 to 2,293, both above one.
Earnings or guidance:
After the bell on Monday, on a feed that carries no after-hours bars, Celestica was reported 13.18% higher, Whirlpool 8.88% lower, Cadence 2.28% higher and Amkor 4.32% higher; index futures slept through all four. Teradyne reports after the close today on its own release. Microsoft and Alphabet are listed for Wednesday and Amazon for Thursday on one calendar route each. Tesla’s 5.21% and Meta’s 1.88% fall are in the letter above, with their stamps and their refusals.
Cross-asset nuance:
Eight of fourteen Treasury tenors rose, three fell, three held. The 6-month 4.35%, up 5 basis points; the 1-year 4.47%, up 3; the 2-year 4.68%, down 1; the 10-year 5.00%, flat; the 20-year 5.35%, down 2, the top of the curve for a 32nd consecutive session; the 30-year 5.31%, down 2. The 2s10s spread is 32 basis points from 31. The relay this book prints only by direction favours a hold heavily on Wednesday and a hike by December. Bond volatility fell 1.08% to 102.20; the three-month equity volatility index read 19.94 against 18.39 spot, a ratio of 0.92, contango. The dollar closed 102.03, up 0.27%, dollar-yen 157.50, up 0.44%. High yield rose 0.19%, investment grade 0.16%, long Treasuries 0.42%. December WTI 101.76, down 1.46%, January 99.49; December Brent 115.81, January Brent 110.74 and the front month by volume, with December expiring Friday. The Tuesday 08:20 UTC bar had December WTI at 102.40, up 0.63% on its settlement. Gold spot 4,016.52, up 0.56%; December gold 4,038.4. December silver 54.34 at settlement, 52.92 on the 08:25 UTC bar, down 2.61%, and 53.08 on the 09:00 UTC bar; no cause named. Syndicated wraps had Tokyo and Seoul higher and Hong Kong and Shanghai lower; no level is printed.
Crypto Market Edge
0.01% Short of Unchanged, 12 Blank Cells, and 684,969 Watchers Nobody Counted Bitcoin 80,040.16 on the midnight mark, 79,668.93 by the re-quote, and Friday’s flow rows finally complete
Price snapshot:
Bitcoin marked 80,040.16 at 00:00 UTC, 0.01% under Sunday’s 80,047.76, then 79,536.45 on the 06:00 UTC bar and 79,668.93 on the 08:25 UTC bar, 0.46% under the mark. Ether marked 2,321.43, down 0.24%, and read 2,309.94. The Coinbase and composite feeds agreed to 0.04% on bitcoin and 0.05% on ether.
Flows and positioning:
Friday’s rows are complete on both products. US spot bitcoin funds netted minus 137.9 million dollars, IBIT minus 110.3 million, FBTC minus 31.8 million, MSBT plus 4.2 million, every cell numeric and the row reconciling to its total. Ether funds netted plus 4.4 million. Monday’s rows were not populated at 07:33 UTC: twelve dashes on bitcoin, seven dashes and four zeros on ether. A dash is an absence. Cumulatives stay frozen at 57,251 million dollars and 12,748 million.
Leadership and rotation:
Gross absolute ether issuer flow on Friday’s completed row was 4.4 million dollars against the 20.0 million floor, so the shot filed on 20 October stays at three scorable sessions, two of them against it, and needs three more scorable ones by 10 November. On the boards at 07:31 UTC bitcoin was crypto rank 3 at a canonical sentiment score of 31 on 684,969 watchers and absent from the all-asset top 25; ether read 18. Strategy held equities rank 2 at a score of 20 on posts about a paused purchase, and the sale count moves on a filing this book has opened, which is none.
Catalysts and roadmap:
Wednesday 18:00 UTC is the statement and 18:30 UTC the press conference. Thursday 12:30 UTC is Q3 GDP and September PCE, Thursday 13:15 UTC the ECB. Strategy’s results are listed for 29 October on one route. Monday’s flow rows want a second read before anyone marks anything on them.
TL;DR
- The S&P 500 rose 0.70% to 7,676.77 while 55.29% of NYSE volume traded in falling issues, 736 million shares against Friday’s 737 million on a down day.
- New lows beat new highs on both exchanges, 50 to 43 and 125 to 74, on a session the Nasdaq 100 gained 1.09% and the chip funds nearly 3%.
- 70% of the index gain came after the open and has no named cause here; an Anthropic filing stamped before the bell sits under a speculation heading, not a cause.
- The 6-month bill rose 5 basis points and the 20-year fell 2 before Wednesday’s statement; Monday’s 2-year auction has no result on the Treasury feed yet.
- Bitcoin marked 80,040.16, flat on Sunday, then 79,668.93 by the re-quote; Friday’s fund row completed at minus 137.9 million and Monday’s is twelve dashes.
Fun Fact
21,000 Stores, 1 Shelf Price, Another Price at the Till The Federal Trade Commission and 20 states sued Dollar General on Monday
The complaint, reported by CBS News, alleges that the register price exceeded the shelf price across the chain’s roughly 21,000 stores. On the same afternoon the stock exchange reported the opposite problem: the price went up and most of the volume did not.
Meme of the Day:
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
p.s. There are 3 ways I can help you…
- Option 1: Collect Morning Income
A complete guide to the Premium Popper system.
Written to be clear, concise, and immediately actionable.
>> Learn More Here
- Option 2: Collect Weekly Income
A complete guide to the Tag ‘n Turn system.
>> Learn More Here
- Option 3: Join the Fast Forward Mentorship
>> Join the Fast Forward Mentorship – trade live, twice a week, with me and the crew.
PLUS Monthly on-demand 1-2-1’s
No fluff. Just profits, Tag ‘n Turn Pulse bars, Poppers, and Patterns that actually work.