Every participation measure improved on the one number that should have frightened them
 Ahoy there, Trader! ⚓️
It’s Phil…
Nobody Told the Front End That 29,000 Was Bad News 29,000 jobs, 4.2% unemployment, 60,000 revised away, and a 2-year that closed up
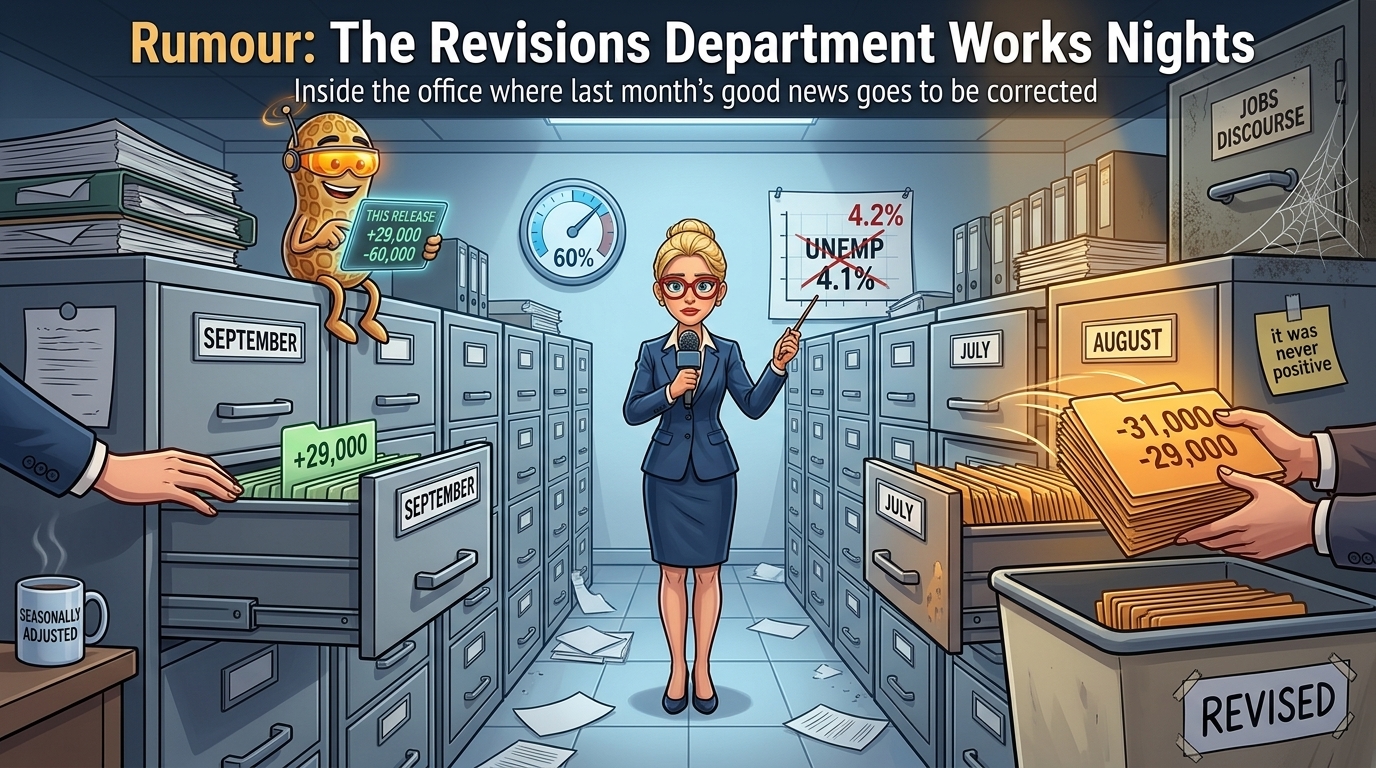
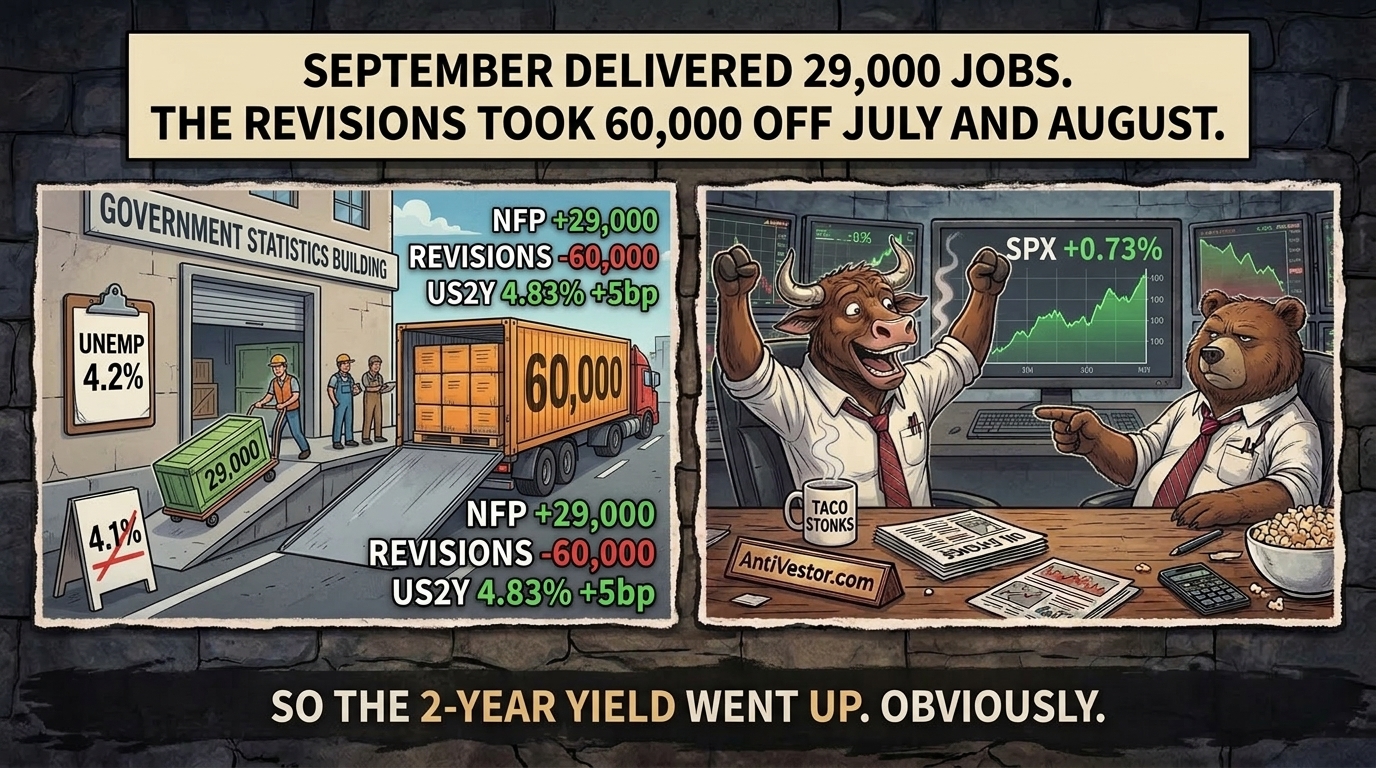
The American economy added 29,000 jobs in September. It then discovered it had overcounted July and August by 60,000, which means the statisticians took away more than twice what the month delivered. July is now a negative number. Unemployment went to 4.2%. Earnings growth slowed to 3.0% on the year.
This is a 29,000 print against a consensus near 79,000, arriving two weeks after a central bank raised rates into it.
The two-year Treasury closed at 4.83%, five basis points higher.
Not immediately, in fairness. For one five-minute bar at 08:30 the front end behaved like a market that reads: the two-year printed its session low, the ten-year printed its session low, both in the same bar, and relief was briefly the consensus. Then the afternoon arrived and handed back the entire move and roughly another one on top.
Equities, meanwhile, threw a party. The S&P added 0.73%, the Nasdaq 1.19%, the Russell 0.94%. Ten of eleven sectors rose. New 52-week lows fell from 180 to 68 and volatility closed at 15.31.
So the stock market has priced the end of the tightening cycle and the bond market has not, and neither of them told us why the afternoon went the way it did.
Three coupon auctions arrive Tuesday to Thursday. The minutes land in the middle of them.
The One That Mattered
29,000.
The tape spent Friday celebrating a labour market that produced 29,000 jobs, lost 60,000 to revision, and pushed unemployment to 4.2%. Equities read that as the hiking cycle ending. The front end read the identical release, rallied for exactly one five-minute bar, and then closed five basis points higher, which is the bond market saying out loud that it does not expect this committee to be rescued by bad news. One of those two readings is a position and the other is a forecast. The front end has been the one finishing other people’s sentences all month.
So, the open question. If 29,000 jobs will not move the front end, what will? We went down the rabbit hole in today’s Macro Edge: https://antivestor.com/macro-edge
Stock Market Edge
The Market Got the Number It Wanted and the Curve Billed It 5 basis points on the two-year, 4 on the ten, 10 of 11 sectors green
Premarket snapshot:
December E-mini S&P futures traded 7,767.50 in the five-minute bar stamped 07:30 UK, down 0.13% on a Friday settlement of 7,777.25. Nasdaq futures sit 0.10% lower, the Dow contract 0.09%, the Russell contract 0.05%. The whole complex is doing nothing in four different ways. Friday’s cash close of 7,722.72 leaves the index 76.27 points below its 13 August record.
Sector rotation:
Ten of eleven sector proxies finished higher, led by consumer discretionary at 1.13% and technology at 1.01%. Health care was the only decliner, at 0.01%, which is less a selloff than a clerical objection. Applied Digital added 5.05%, Tesla 4.65% and Super Micro 4.22%, so the session’s leadership came from precisely the names that need cheap money and a confident consumer.
Earnings or guidance:
A thin Friday. McCormick added 1.20% having lost 4.87% the day before, on a quarter where the reported figure and the circulating consensus are measured on different bases, which is a distinction worth making before anyone calls it a beat. Constellation Brands, RPM and Lamb Weston go Tuesday; PepsiCo and Progressive Thursday.
Cross-asset nuance:
The dollar index closed 101.923, down 0.12%, with sterling rather than the euro supplying the move, which is a change of author from last week. November WTI settled $91.11, down 1.90%. December gold settled $4,162.30, down 0.95%, and its aligned carry against spot, taken on a matched 14:00 ET mark, printed 25.01, outside a band that had held for ten sessions. Nothing in commodities agreed with equities either.
Crypto Market Edge
The Structural Bid Filed a Partial Return $84,489 bitcoin, two blank columns, and a shot we have to mark against ourselves
Price snapshot:
Bitcoin marked $84,489.05 at Friday’s UTC mark against $84,504.88 on Coinbase, down 0.40%, the two legs agreeing to 0.018733%. Ether marked $2,667.80, down 1.36%. Small-cap equities gained 0.94% on the same session, so whatever the coins are correlated to this week, it is not risk appetite.
Flows and positioning:
Here is one we have to mark against ourselves. On 18 September this book claimed the ETF complex follows price rather than setting it, and filed a falsifier anybody could check: cumulative US spot bitcoin net flow negative across the eleven sessions to 2 October. That window closed Friday. On the sessions we can actually mark it finished at plus $2,818.8m. Not a near miss, not an unlucky tail. The claim is dead and the ledger says so in full.
Leadership and rotation:
Strategy closed $160.01, down 0.31%, after a tour of $170.17 and $155.89. Cardano, Pengu and Fetch led the crypto board on Monday morning; bitcoin, ether, Solana and XRP were all absent from the top 25 on every board. Bitcoin’s weekly message volume rose 6.82% regardless, so the crowd is still talking, just not where the rankings look.
Catalysts and roadmap:
Strategy’s 1 October filing discloses a dividend rate on a variable-rate perpetual preferred and a semi-monthly cash payment, the second conditional on a shareholder vote later this month. Holdings are unchanged at 847,666 coins as of 27 September.
TL;DR – The Bottom Line
- September produced 29,000 jobs and revisions took 60,000 off July and August. The two-year closed five basis points higher on the news.
- The front end printed its session low inside the 08:30 payrolls bar and then handed back more than the whole move before the bell.
- Equities read the same release as relief: the S&P rose 0.73%, ten of eleven sectors gained, and NYSE new lows fell from 180 to 68.
- Volatility closed 15.31, down 6.59% and its lowest since 25 September, which is a confident forecast on a very soft employment report.
- Our own flow shot died on Friday at plus $2,818.8m against a falsifier that needed a negative number. Marked, logged, not softened.
Fun Fact
A Payroll Month Can Be Revised Across Zero July 2026 first printed as plus 21,000 jobs and now stands at minus 10,000
The first payroll estimate goes out before every surveyed employer has filed, and two later revisions follow as the rest arrive. July 2026 crossed from positive to negative somewhere in that process, which means the month everybody traded as growth had been a contraction the whole time.
Meme of the Day:
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
p.s. There are 3 ways I can help you…
- Option 1: Collect Morning Income
A complete guide to the Premium Popper system.
Written to be clear, concise, and immediately actionable.
>> Learn More Here
- Option 2: Collect Weekly Income
A complete guide to the Tag ‘n Turn system.
>> Learn More Here
- Option 3: Join the Fast Forward Mentorship
>> Join the Fast Forward Mentorship – trade live, twice a week, with me and the crew.
PLUS Monthly on-demand 1-2-1’s
No fluff. Just profits, Tag ‘n Turn Pulse bars, Poppers, and Patterns that actually work.