Two-year at a 52-week high, ten-year at 2007 levels, volatility at a monthly low
 Ahoy there, Trader! ⚓️
It’s Phil…
Nobody Told the VIX There Was a Hiking Cycle On Twelve points on the index, nine basis points on the front end, 14.81 on the fear gauge
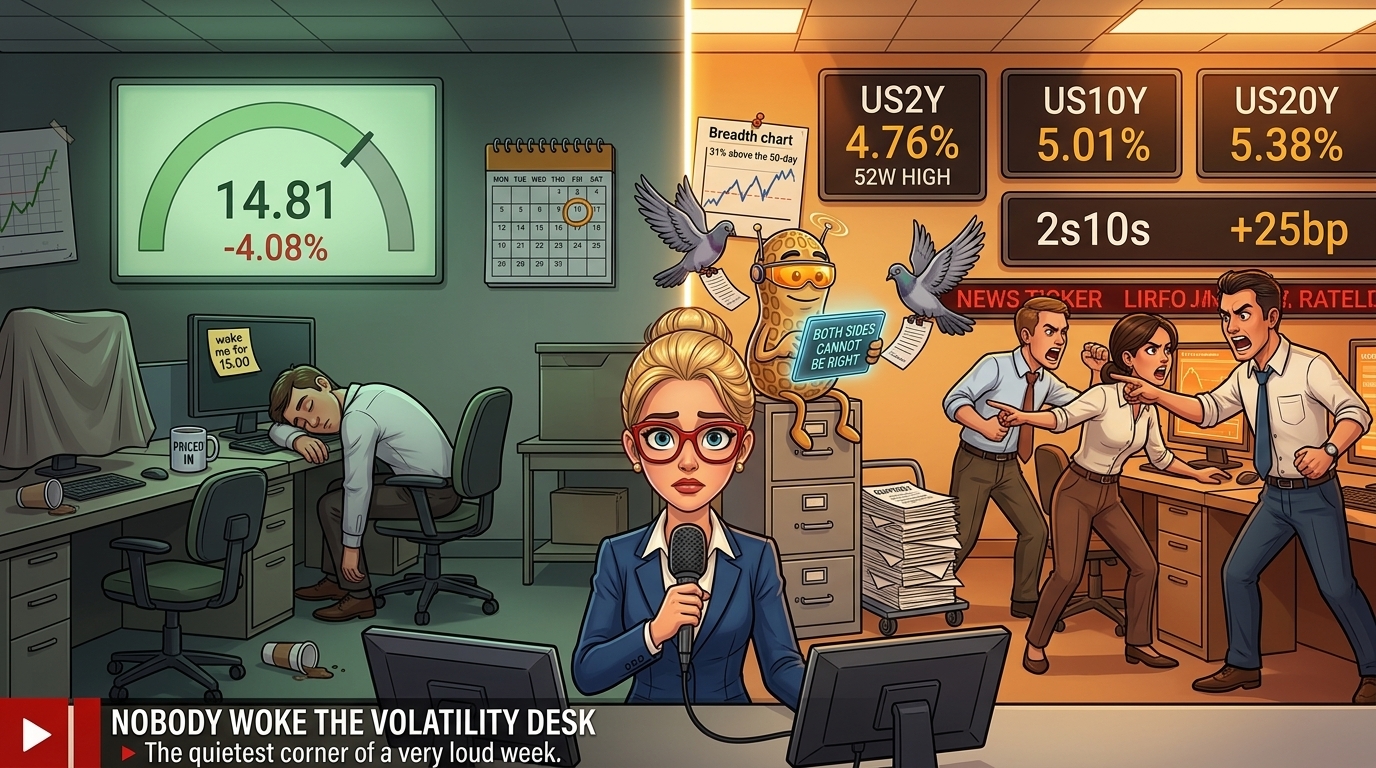
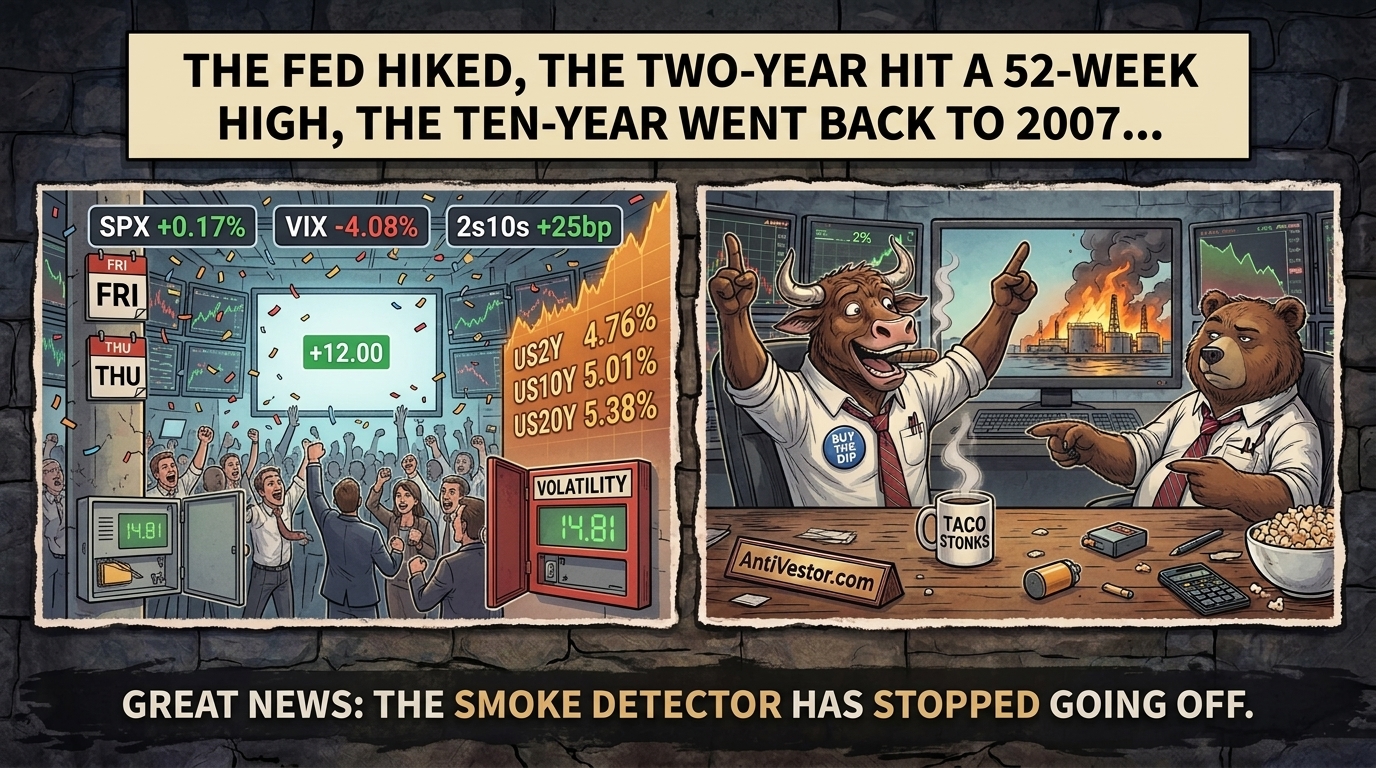
Friday was quarterly expiry, the largest options event of the quarter, two days after the Fed raised rates for the first time since 2023. The S&P 500 responded by moving 12.74 points. The two-year Treasury moved nine basis points, to 4.76%, a fresh 52-week high. The ten-year returned to 5.01%, a level it last held in 2007.
And volatility closed at 14.81, down 4.08%, its lowest print since 4 September.
One of these markets has misread the week. The bond market spent Friday pricing a central bank that has told it, in Warsh’s own words, that it merely “removed a dose of accommodation” and would be “hard-pressed to describe broad financial conditions as restrictive”. That is a chairman saying he has not started yet. The front end believed him. The volatility complex filed it under noise.
Underneath, the tape is threadbare. Just 31% of the index sits above its 50-day average, fewer than one in five above the 20-day, and new lows beat new highs fifteen to one. The index has gone 36 sessions without a 1% down day, which is the sort of streak that gets described as resilience right up until it gets described as complacency.
Xi lands Thursday. Wednesday brings flash PMIs and the first of $183bn in supply.
The One That Mattered
The tape spent Friday congratulating itself on twelve points whilst the two-year booked a 52-week high and the ten-year went back to 2007. No Fed official discussed policy that day. The front end repriced anyway, which is worse: the market has stopped waiting to be told. And into that, on the quarter’s biggest expiry, volatility closed at its lowest since 4 September with dealers short gamma and breadth at its thinnest since summer. Cheap insurance sold into a thin book has a name, and it is not confidence.
So, the open question. What is volatility at 14.81 pricing that the front end at 4.76% is not? We took it apart in today’s Macro Edge.
Collect Morning Income
– Learn More
Stock Market Edge
The Fed Said Nothing on Friday and the Two-Year Moved Anyway Nine basis points of opinion from a market that was not asked
Premarket snapshot:
December E-mini S&P futures traded 7,754.75 at 03:05 ET, up 0.55% on a Friday settlement of 7,712.50. Nasdaq futures lead at 30,159.00, up 0.81%, on a Bessent adjective. Cash closed 7,650.50, which is 1.90% under the 13 August record of 7,798.99, a gap now five weeks old.
Sector rotation:
Technology and industrials carried it. The other nine went backwards, utilities, materials and real estate doing the honourable thing and admitting yields exist. Broadcom added 2.4% and was the largest single contributor to both indices, which tells you how much of Friday was one stock wearing a trenchcoat.
Earnings or guidance:
Nucor guided to $5.55 to $5.65 against $5.99. Steel Dynamics guided to $5.34 to $5.38 against $5.60. Netflix lost 4.67% to $71.79 after Wells Fargo cut it to Underweight and removed $23 from the target. Xenon Pharmaceuticals lost 30.69% pausing Phase 3 enrolment, the session’s only honest drawdown.
Cross-asset nuance:
The dollar closed 100.22, better than 1% up on the week. The Bank of Japan raised to 1.25%, a 31-year high, on a 7-2 vote, and the yen promptly weakened through 157. A central bank tightened and its currency fell. Gold settled $4,424.90 in December futures.
📊 There’s a level on SPX I’m watching closely this morning. My full analysis briefing has it – plus what happens if we hold it, and what happens if we don’t. [Read it here →]
Crypto Market Edge
The Structural Bid Arrived Two Days After the Price Did $433m of conviction, filed immediately behind a 6% move
Price snapshot:
Bitcoin marked $81,170 at Monday’s 00:00 UTC against a mid-week low of $74,913, up roughly 6% week on week. Ether sat at $2,645, Solana led the majors at 11% on the week. The move was built entirely in Friday’s US session. The weekend traded sideways and gave a little back, the most restrained thing bitcoin has done all month.
Flows and positioning:
US spot bitcoin funds took $433.0m net on Friday, the biggest session since early September, after handing back $746.3m on the 15th and 16th. Fidelity supplied $310.7m of it on its own. Grayscale supplied nothing. Cumulative net flow since launch now reads $55,230m against $102.5bn of assets.
Leadership and rotation:
The equities beat the coins. Strategy closed up 16.39%, Coinbase up 11.66%, Robinhood up 9.1%, Circle up 7.9%. Strategy managed its best day of the quarter with its holdings unchanged at 845,050 coins for a third week, which is a neat trick: a treasury company rewarded for doing no treasury.
Catalysts and roadmap:
The SEC issued its innovation exemption on Thursday and the CFTC posted rules to the White House the same afternoon, two days after Senate cloture died 49-50. CoinDesk’s policy conference runs Tuesday with Gillibrand and Hill on the bill. The agencies have stopped waiting for Congress.
Collect Weekly Income
Learn More
TL;DR – The Bottom Line
- The index moved 12.74 points on quarterly expiry. The two-year moved nine basis points to a 52-week high. Only one of those was information.
- Volatility closed 14.81, its lowest since 4 September, two days into a hiking cycle, with dealers short gamma and breadth at its thinnest since summer.
- The ten-year is back at 5.01%, last seen in 2007, and the twenty-year at 5.38% is the highest point on the entire Treasury curve.
- Bitcoin funds took $433.0m on Friday after a regulator’s memo, having handed back $746.3m two days earlier. Structural is a strong word.
- Buffett gave up the chair at 96 with the line “Father Time always wins”, which is still the most rigorous forecast published all week.
📌 Fun Fact
The Twenty-Year Bond Spent Thirty-Four Years Off the Calendar Treasury killed it in 1986 and only brought it back in 2020
The twenty-year Treasury bond was discontinued in 1986 and did not return to the auction schedule until May 2020, a gap of thirty-four years. The sector never quite reintegrated, which is why the twenty-year currently yields more than the thirty-year and has done so every session since 10 September.
Meme of the Day:
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
p.s. There are 3 ways I can help you…
- Option 1: Collect Morning Income
A complete guide to the Premium Popper system.
Written to be clear, concise, and immediately actionable.
>> Learn More Here
- Option 2: Collect Weekly Income
A complete guide to the Tag ‘n Turn system.
>> Learn More Here
- Option 3: Join the Fast Forward Mentorship
>> Join the Fast Forward Mentorship – trade live, twice a week, with me and the crew.
PLUS Monthly on-demand 1-2-1’s
No fluff. Just profits, Tag ‘n Turn Pulse bars, Poppers, and Patterns that actually work.