Two weeks braced for the barrel and the bond, and a Saturday essay opened the gap
⚓ Weathervane: The wind is coming from the long end. The policy rate has been frozen at 3.50% to 3.75% since July whilst the term premium does the tightening, and the price of long money is set by deficits, issuance supply and a synchronised global duration bid rather than by the committee. Higher-for-longer has stopped being a Fed decision and become a bond-market fact. The cruise ship holds this heading.
 Ahoy there, Trader! ⚓️
It’s Phil…
When the people building the AI trade ask everyone to slow down, is that a safety story or a growth story?
Most desks would say the first. The essay published on Saturday was about risk, alignment and evaluators, and the two rival chief executives who agreed with it inside a day were agreeing about danger, not about revenue. The common view this morning treats it as a governance story that happens to have a share price attached.
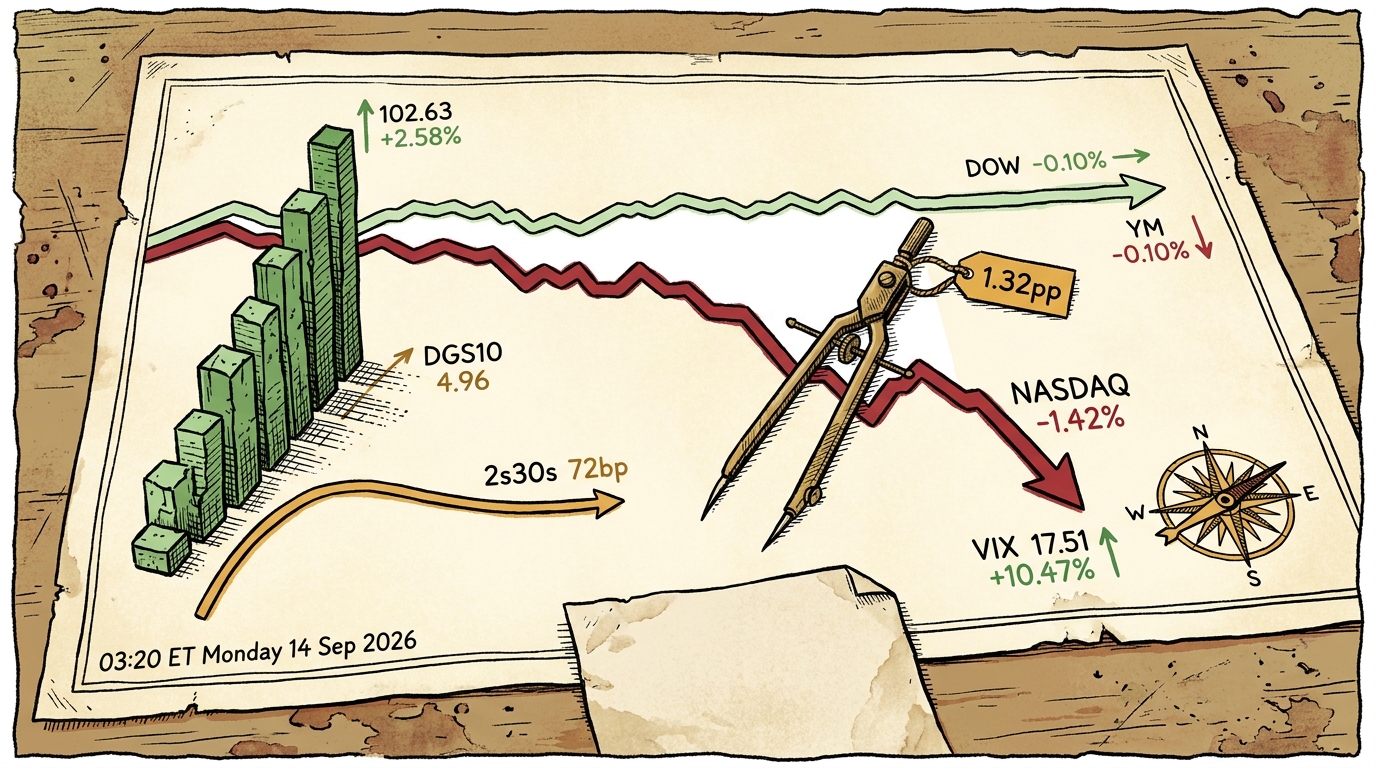
The tape picked the second answer, and it picked it at the first opportunity. Futures reopened at 18:00 ET on Sunday and gapped immediately, Nasdaq contracts 1.2% lower inside twenty minutes against 0.4% for the Dow. Fourteen hours later the split has widened rather than closed: Dow futures off 0.22%, Nasdaq futures off 1.69%, 1.47 percentage points of daylight between them. Meanwhile crude added 3.55% to 103.54 and bitcoin held 77,696. A market running for cover does not leave the barrel bid and the industrial index nearly level.
Follow the other instruments and the picture gets stranger. Last week delivered exactly the shock everyone had been braced for. Crude settled above $100 for the first time since spring. The ten-year reached 4.96% on the Treasury’s own series and trades near 4.99% this morning, the highest since November 2023. The two-year moved twenty basis points in two sessions with the Federal Reserve in blackout. Every one of those is a textbook growth-equity headwind, and the growth complex took its largest single hit of the run from none of them.
The textbook expectation for a voluntary slowdown inside a capital expenditure boom is reasonably clear. It should hurt the suppliers, because their order book is the thing being paced, and it should be roughly neutral for the buyers, whose costs stop compounding. That is very nearly what happened: semiconductor indices sit around 20% below their June high, and the index full of companies that buy computing rather than sell it barely moved. What the textbook does not explain is the speed. This repricing was fully expressed inside twenty minutes of futures reopening on a Sunday evening, with no data, no earnings and no central bank in the room, and it has not been bought back since.
So there is the honest gap. Mr Market spent a fortnight pricing the risk that energy and yields would break the growth trade, and the growth trade was instead repriced by a change in the willingness of its own builders to keep building. Whether that is the tape being extremely quick or extremely thin is the part still open, and Wednesday’s projection set will overwrite half the evidence either way.
Phil’s Musing
Two things can be true. The barrel and the long end are still the slow mechanism, and I think the Weathervane is right about the heading. But something repriced the Nasdaq by 1.69% over a weekend, gap and all, that no rates model contains, and I would rather name that as a third input than pretend it fits the existing frame. The tell to follow is not the essay. It is whether the gap between the two indices survives Wednesday.
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
P.S. – Phils Footnote I got last week wrong in an instructive way. I had the shock coming from the barrel, and I had reasons: the pipeline, the strait, the settlement prints. It came from a blog post instead, and I spent Sunday evening reading it twice trying to work out whether I would have cared in June. Wall Street often says the market prices everything eventually. What it rarely admits is that “eventually” sometimes means the following Saturday, and from a source that was not on anybody’s calendar.