A 58.7 services print repriced the whole curve. Meta went up. Almost nothing else did.
 Ahoy there, Trader! ⚓️
It’s Phil…
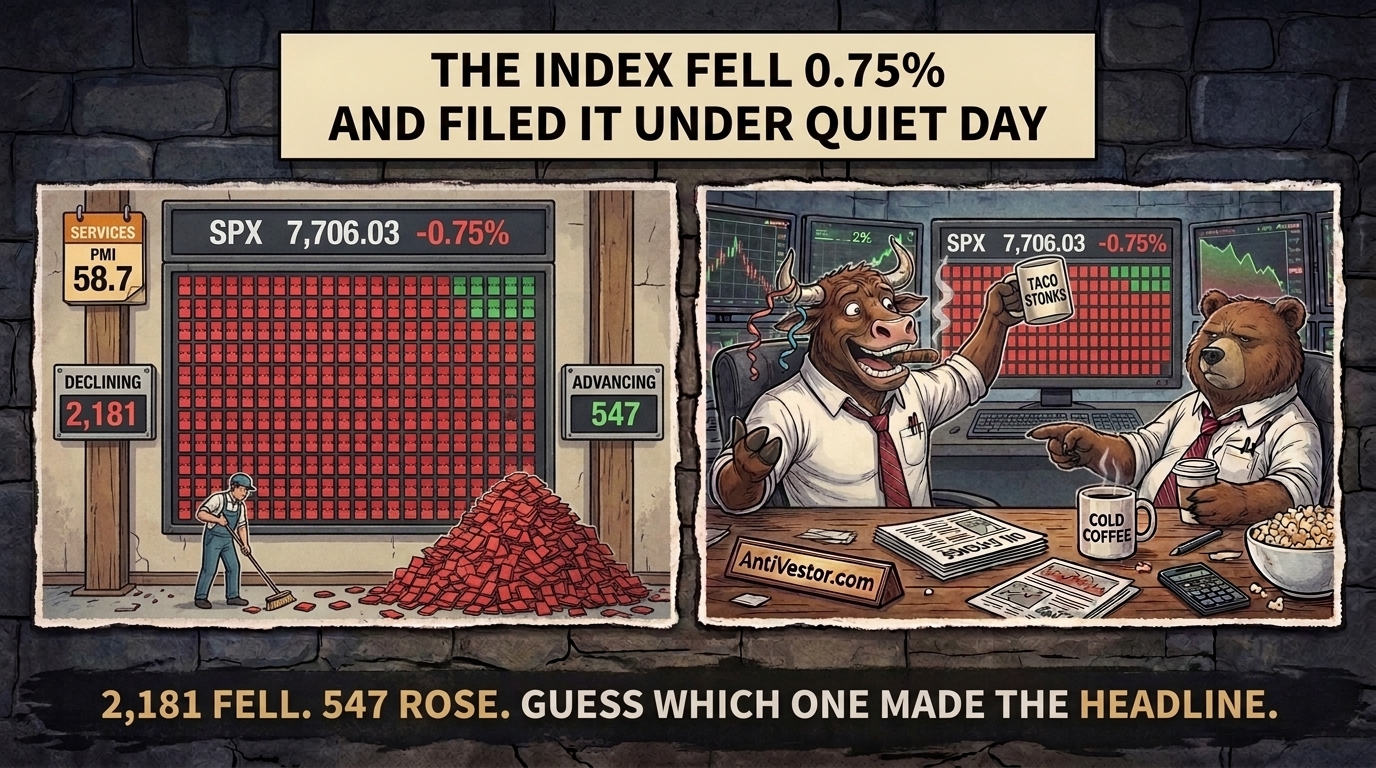
The S&P 500 fell 0.75% yesterday, which is the sort of number a market writes when nothing much happened. Nothing much happened to 2,181 NYSE issues in the way that nothing much happens to a windscreen. They fell. Five hundred and forty-seven rose. That ratio, 0.251, is the weakest in the thirty-two sessions this book holds, and it is the only reading under 0.30 in the lot.
The index did not know, because the index was not counting the same companies. The S&P 500 holds five hundred large businesses weighted by size. The NYSE tally counts every issue on the exchange, and most of those are small. Small caps lost 1.77%. And before anyone reaches for the usual explanation, the giants did not hold anything up either: Alphabet fell 3.80%, Oracle 3.11%, Broadcom 2.62%, Amazon 2.24%. Meta added 1.02% on 1.45 times average volume and Microsoft 0.52%, which between them is worth a few basis points of a 58.61 point decline. The two readings are not in conflict. They are answers to different questions.
What took it apart was a survey. US flash services activity printed 58.7 against 56.5 in August, manufacturing 57.0 against a 53.6 forecast, and the Treasury curve lifted at every tenor beyond two years. The belly moved 16 basis points. Utilities lost 1.92%, real estate 1.55%, small caps 1.77%, all of them things you value by dividing by a rate that had just gone up.
The committee hiked six sessions ago. September then turned up and made the hike look cautious.
The One That Mattered
The number was not 0.75%. It was 0.251, the ratio of NYSE stocks that rose to those that fell, and it is the weakest in thirty-two sessions. The tape spent the day congratulating itself on a modest decline whilst four stocks fell for every one that gained, which is the sort of arithmetic that only looks calm if you count the five hundred largest companies and call that the market. The index was not lying. It was answering a narrower question than the one being asked of it. So the question is which of the two was telling the truth, and who blinks first. If the index says one thing and the average stock says another, which one is describing the economy the Fed is about to keep tightening into? We went down the rabbit hole in today’s Macro Edge.
Stock Market Edge
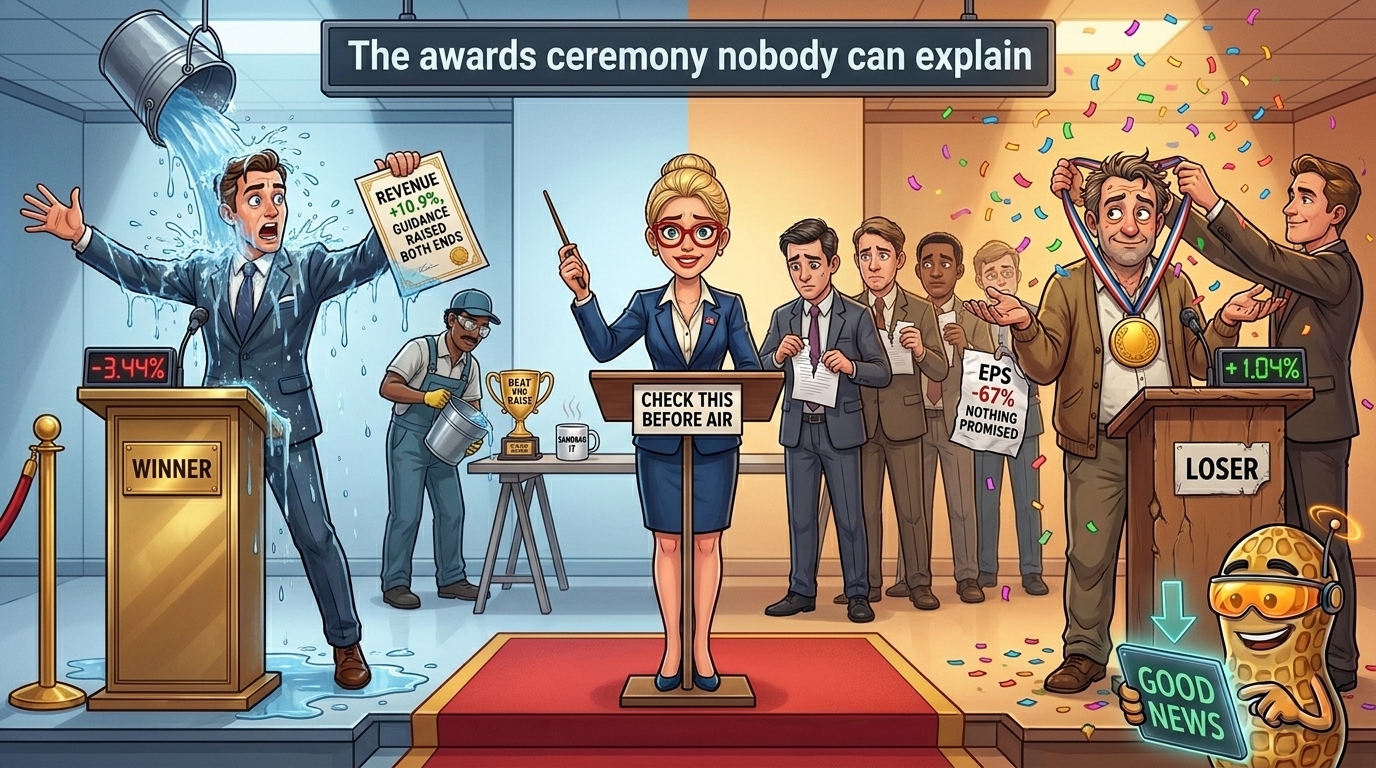
Good News Was Tried and Found Guilty 2 beat-and-raises were taken out and shot; a 67% earnings decline got a round of applause
Premarket snapshot:
At the 07:20 UK capture, 02:30 ET, December S&P futures sat at 7,744.25 and December Nasdaq futures at 30,605.50, lower by 0.36% and 0.52% from settlements of 7,772.50 and 30,764.75. Cash closed at 7,706.03 after a fall of 58.61 points. The December contract carries a basis of 66.47 points over cash, which is worth knowing before anyone compares the two and invents a rally.
Sector rotation:
Energy was the only green close on the board, up 0.96%, with November crude 1.81% higher. Everything else got measured against a discount rate that had moved. Utilities lost 1.92% on 1.30 times average volume, real estate 1.55% on 1.33 times, financials 0.47% on 1.29 times. Heavy volume in the sectors that hate rates is not indecision. It is a decision.
Earnings or guidance:
Cintas grew revenue 10.9%, posted adjusted EPS of $1.39, raised both ends of full-year guidance, and fell 3.44%. Paychex beat consensus on adjusted EPS at $1.34, raised two guidance components and cut none, and fell 8.77%. General Mills reported earnings down 67%, reaffirmed everything, and rose 1.04%. The market has decided it will pay for the absence of bad news and nothing else.
Cross-asset nuance:
The dollar took 0.57% to 101.114 and dollar-yen reached 158.347, now 1.653 away from the level the market watches for the Bank of Japan. Gold spot fell 1.62% to 4,286.97 against December futures at 4,318.40. Real yields went up, so everything you hold instead of a bond went down.
Crypto Market Edge
Bitcoin Discovered It Is a Bond With Worse Manners Down 2.10% beside gold, silver and copper, which is not the story anyone sells
Price snapshot:
Bitcoin closed 84,397.60 on the 23 September UTC mark, down 2.10%. Ether closed 2,684.71, down 2.50%. December silver fell 2.35%, December copper 1.21%, gold spot 1.62%. Four asset classes, one cause, and the one that promised to be uncorrelated came in second-worst. At the 07:24 and 07:25 UK captures this morning both were near flat.
Flows and positioning:
The flow row for 23 September is not finished. Farside shows 32.4 million dollars of net bitcoin inflow, but seven issuers including BlackRock and Fidelity show a dash where a zero would be, so anyone reading a collapse from the prior session’s 714.7 million is reading an empty cell. Cumulative shows 56,976 million dollars. This book will not mark a shot on a half-reported day, and says so before the number improves rather than after.
Leadership and rotation:
Bitcoin held first on the crypto-only board at 06:22 UTC. XRP, which sat first across all asset classes on Tuesday, was outside the crypto-only top 25 this morning at 1.51, down 6.95%, whilst its message volume went up over the same window. Rank and chatter are two different measurements and this week they disagreed.
Catalysts and roadmap:
Strategy filed nothing, so the count stays at 846,000 bitcoin. The 7-year note auction lands today and Costco reports after the close. Both reach crypto down the same wire that moved it yesterday, which is the real yield, whatever anybody says about adoption.
TL;DR
- Flash services printed 58.7 against 56.5 prior, every Treasury tenor past 2 years closed higher, and the belly led the whole move by 16 basis points.
- The S&P lost 0.75% to 7,706.03. Beneath it 2,181 NYSE issues fell against 547 that rose, the weakest ratio in thirty-two sessions held.
- Treasury sold $70bn of 5-years at 5.033%. Cover of 2.21 and indirects at 54.31% were each the lowest of the last seven of these auctions.
- Cintas raised guidance twice and fell 3.44%. Paychex beat and raised and fell 8.77%. General Mills earned 67% less and closed higher.
- Bitcoin fell 2.10% beside gold spot, silver and copper on a real-yield session. The 23 September flow row is half-reported and is not evidence of anything.
Fun Fact
The Survey That Never Asks for a Number A questionnaire containing no measurements moved the entire Treasury curve
A purchasing managers’ index is built entirely from opinion. Respondents are never asked for a figure, a volume or a value. They are asked one thing per category: whether things are better, the same, or worse than last month.
Meme of the Day:
Happy trading,
Phil
Less Brain, More Gain
…and may your trades be smoother than a cashmere codpiece
p.s. There are 3 ways I can help you…
- Option 1: Collect Morning Income
A complete guide to the Premium Popper system.
Written to be clear, concise, and immediately actionable.
>> Learn More Here
- Option 2: Collect Weekly Income
A complete guide to the Tag ‘n Turn system.
>> Learn More Here
- Option 3: Join the Fast Forward Mentorship
>> Join the Fast Forward Mentorship – trade live, twice a week, with me and the crew.
PLUS Monthly on-demand 1-2-1’s
No fluff. Just profits, Tag ‘n Turn Pulse bars, Poppers, and Patterns that actually work.